Dispatch №19

  • When Wine Breathes with Love
  • From Refugee to Football Star
  • The Brothers Who Live One Life
  • The history of a legendary American family: how they built and lavished their fortune

Amorim — When Wine Breathes with Love

Behind every good wine stands a quality cork. With these words, the Portuguese corporation Amorim Group welcomes visitors to its website. When you get to know the company better, you realize that it’s not just empty rhetoric. The Amorim family entered the business back in 1870. Over the course of 150 years, a small winery producing cork stoppers has transformed into a global industry leader. Today, Amorim Group controls 65% of the world’s natural cork market. Throughout this time, four generations have passed in leadership, yet the values remain steadfast: caring for nature and consumer comfort.

Corks are crafted from the bark of cork oak trees. The bark can only be harvested once the tree reaches 20-25 years of age. The following 10 years are dedicated to regeneration. The best-quality bark comes from a 150-year-old oak, yielding 1000 corks per tree at a time. So, the next time you discard a wine cork, it’s worth contemplating. It’s certainly worthy – if not for becoming a decorative element, then for repurposing. It could turn into things like a surfboard or a Birkenstock sole. By the way, the company itself recycles raw material leftovers, producing floors and other construction materials. But let’s return to the market.

Natural cork holds 70% of the global market share, leaving screw caps and synthetic alternatives far behind. Today, natural corks seal around 13 billion wine bottles out of a total of 20.5 billion produced annually. Amorim sells over 6 billion corks per year.

Since the beginning of our century, the company has invested over 50 million euros in research and innovation, successfully overcoming the issue of TCA contamination that affects the taste of wine. To explain simply: the cork reacts with the wine, causing the product to acquire a wet cardboard smell. Thanks to the innovative ROSA system, the risk of wine being affected by TCA has dropped from 7% to less than 1%.

Amorim went public in 1988. In 2022, for the first time in the company’s history, sales exceeded 1 billion euros. In the first six months of this year, cork sales alone increased by 5.4% (almost 424 million euros).

Cork is a renewable, zero-waste, and recyclable natural material. Cork oak forests lead in terms of biological diversity in the Mediterranean, preventing desertification, they “breathe.” However, if cork oak stops justifying its existence economically, sadly, there might be little to save it. There was a time when, due to economic reasons, cork forests in the Algarve region in southern Portugal decreased by 28%. Every time we choose wine with a natural cork, we’re choosing the health of the planet.

The Remarkable Journey of Nadia Nadim: From Refugee to Football Star

The Early Years: An Unsettled Childhood

As the sun rose over the city of Herat, Afghanistan, a young girl named Nadia Nadim was born into a world of unpredictability and strife. The year was 1988, and this was a time when Afghanistan was fraught with warfare, leaving little room for dreams, especially for a girl. Yet, Nadia was destined to shatter these norms.

She was the youngest of five girls in a family that prized education and sports. Her father, an Afghan National Army general, was a firm believer in the power of education and believed that his daughters should have every opportunity to learn and grow. But the political climate of the country was not favorable for these ideals. The rise of the Taliban regime brought an end to the dreams of many, including the Nadim family.

The unthinkable happened when Nadia was just ten years old. Her father was summoned to a meeting with the Taliban and never returned. Presumed to be murdered, his absence left a gaping hole in the family. In the midst of this despair, Nadia’s mother bravely decided to escape the oppressive regime with her five daughters. A perilous journey across borders awaited them, but the dream of a better life fueled their courage.

A New Home: Embracing the Unknown

The family made their way to Europe, initially landing in Italy. From there, they were smuggled in the back of a truck with the promise of reaching England. However, the journey ended in Denmark. While it wasn’t their intended destination, Denmark offered them something they hadn’t had in a long time – safety and the freedom to dream.

Life in a refugee center was challenging, but it also offered Nadia an unexpected gift – football. Watching boys play in a nearby field, Nadia was instantly attracted to the game. She convinced her mother to let her play, and with that, a spark was ignited. Football became her refuge, a means to navigate her new life. The game brought her joy and a sense of belonging in an otherwise unfamiliar land.

Although she didn’t know it then, football was not just a hobby for Nadia; it was her calling. She joined a local club, Gug Boldklub, where her talent was quickly recognized. From there, she swiftly climbed the ranks of Danish football, joining top-tier clubs and eventually making it to the national team. Nadia was making her mark in a big way, and she was just getting started.

Finding Success: The Rise of a Champion

In 2009, Nadia made her professional debut with the Danish Women’s National Team. Her natural ability to score goals, combined with her tenacious spirit, made her a standout player. Nadia was not just playing football; she was changing the narrative for female athletes, particularly those of immigrant backgrounds.

Her talent caught the attention of international clubs, and in 2014, Nadia signed with Sky Blue FC, marking her entry into the prestigious National Women’s Soccer League (NWSL) in the United States. She continued to impress, earning a spot with Portland Thorns FC, where she helped lead the team to an NWSL Championship in 2017.

In 2018, Nadia’s journey took another exciting turn when she signed with Paris Saint-Germain, one of the world’s most renowned football clubs. Here, she continued to shine, both on and off the pitch.

Beyond her footballing prowess, Nadia became a symbol of determination and resilience. Throughout her career, Nadia has been a vocal advocate for women’s rights and equality in football. She uses her platform to shed light on the issues that matter, challenging the status quo and pushing for change. “I hope to inspire others to believe in themselves and to fight for their dreams,” Nadia once said. A quote that perfectly captures her spirit and determination.

Facts and numbers

$26000 Nadia Nadim earns weekly at Racing Louisville, according to reports

11 languages Nadia speaks as a multi lingual: English, French, German, Dari, Farsi, Urdu, Swedish, Norwegian Parsian, Arabic and Hindi. 
Looking Ahead: Nadia’s Future Plans

After achieving so much in her football career, one might wonder what’s next for Nadia Nadim. Well, she’s not one to rest on her laurels. In 2022, Nadim fulfilled her goal of becoming a doctor, specifically in reconstructive surgery. She attended medical school at Aarhus University remotely during the football season. 

When she began playing football in Denmark, coaches at her first club offered to cover transport expenses given how far away she lived from it at the time.

These moments “had a huge impact on me,” said Nadim.
“I know as a doctor, I’ll be able to do that for other people”.
“I know the value of helping a person when they have no hope,” she told The Guardian.
“I know 100 percent that I want to be a surgeon.”

In early 2022, the dream that she had been working towards for all these years came true as she qualified to become a doctor. Nadim shared the news across her social media, saying: “For the haters, I did it again. Kicked a** and there’s nothing you can do about it!”

Lessons from Nadia Nadim’s Journey

Nadia’s life story is a testament to the power of dreams and the indomitable human spirit. Despite the numerous challenges she faced, from losing her father to navigating life as a refugee, she never let her circumstances define her. Instead, she dared to dream big, using her passion for football as a vehicle to change her life.

Nadia’s journey also highlights the importance of perseverance. Success didn’t come easily. She faced numerous setbacks and obstacles, but she never gave up. She worked hard, practiced relentlessly, and never lost sight of her goals. This resilience is a powerful reminder that success often lies beyond the challenges that seem insurmountable at the time.

Perhaps the most important lesson from Nadia’s story is her spirit of service. She used her success not just to benefit herself, but to inspire and uplift others. She became a role model for young girls and refugees, using her platform to advocate for change. This spirit of service is a reminder that success is not just about achieving our personal goals, but also about making a positive impact on the world around us.

In the end, the story of Nadia Nadim is one of courage, resilience, and determination. It’s a story that reminds us that no matter where we come from or what challenges we face, we all have the power to shape our own destiny.

Books
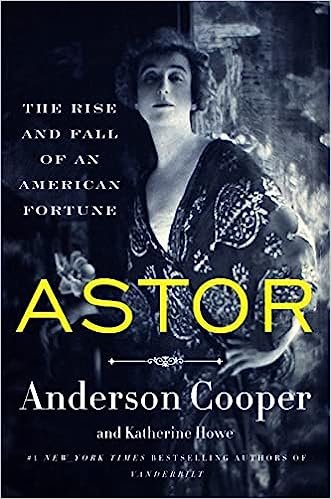
The number one New York Times bestselling authors of Vanderbilt return with another riveting history of a legendary American family, the Astors, and how they built and lavished their fortune.

The story of the Astors is a quintessentially American story—of ambition, invention, destruction, and reinvention.

From 1783, when German immigrant John Jacob Astor first arrived in the United States, until 2009, when Brooke Astor’s son, Anthony Marshall, was convicted of defrauding his elderly mother, the Astor name occupied a unique place in American society.

The family fortune, first made by a beaver trapping business that grew into an empire, was then amplified by holdings in Manhattan real estate. Over the ensuing generations, Astors ruled Gilded Age New York society and inserted themselves into political and cultural life, but also suffered the most famous loss on the Titanic, one of many shocking and unexpected twists in the family’s story.

In this unconventional, page-turning historical biography, featuring black-and-white and color photographs, #1 New York Times bestselling authors Anderson Cooper and Katherine Howe chronicle the lives of the Astors and explore what the Astor name has come to mean in America—offering a window onto the making of America itself.
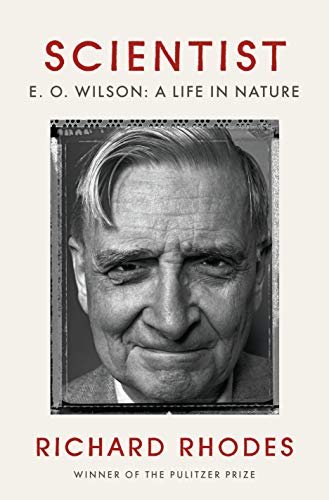
A masterful, timely, fully authorized biography of the great and hugely influential biologist and naturalist E. O. Wilson, one of the most ground-breaking and controversial scientists of our time—from the Pulitzer Prize-winning author of The Making of the Atomic Bomb

“An impressive account of one of the 20th century’s most prominent biologists, for whom the natural world is ‘a sanctuary and a realm of boundless adventure; the fewer the people in it, the better.’” —The New York Times Book Review


Few biologists in the long history of that science have been as productive, as ground-breaking and as controversial as the Alabama-born Edward Osborne Wilson. At 91 years of age he may be the most eminent American scientist in any field.

Fascinated from an early age by the natural world in general and ants in particular, his field work on them and on all social insects has vastly expanded our knowledge of their many species and fascinating ways of being. This work led to his 1975 book Sociobiology, which created an intellectual firestorm from his contention that all animal behavior, including that of humans, is governed by the laws of evolution and genetics. Subsequently Wilson has become a leading voice on the crucial importance to all life of biodiversity and has worked tirelessly to synthesize the fields of science and the humanities in a fruitful way.

Richard Rhodes is himself a towering figure in the field of science writing and he has had complete and unfettered access to Wilson, his associates, and his papers in writing this book. The result is one of the most accomplished and anticipated and urgently needed scientific biographies in years.
Chronicling 200 years of glamour, hedonism and crime, this rich and vivid history of the French Riviera features a vast cast of famous characters.

A Financial Times ‘Book to Read in 2023’

In 1835, Lord Brougham founded Cannes, introducing bathing and the manicured lawn to the wilds of the Mediterranean coast. Today, much of that shore has become a concrete mass from which escape is an exclusive dream. In the intervening years, the stretch of seaboard from the red mountains of the Esterel to the Italian border hosted a cultural phenomenon well in excess of its tiny size.

A mere handful of towns and resorts created by foreign visitors – notably English, Russian and American – attracted the talented, rich and famous as well as those who wanted to be. For nearly two centuries of creativity, luxury, excess, scandal, war and corruption, the dark and sparkling world of the Riviera was a temptation for everybody who was anybody. Often frivolous, it was also a potent cultural matrix that inspired the likes of Picasso, Matisse, Coco Chanel, Scott Fitzgerald, Cole Porter, James Baldwin, Catherine Mansfield, the Rolling Stones, Sartre and Stravinsky.

In Once Upon a Time World, Jonathan Miles presents the remarkable story of the small strip of French coast that lured the world to its shores. It is a wild and unforgettable tale that follows the Riviera’s transformation from paradise and wilderness to a pollution imperilled concrete jungle.
Discover the official story of In-N-Out Burger––how three generations have created a thriving, family-owned company, why its fans are so wildly loyal, and what led to its explosive growth and evolution into an iconic part of American culture––as told by In-N-Out Burger’s president, Lynsi Snyder.

When Lynsi Snyder’s grandparents founded In-N-Out Burger in 1948, they built it with a passion for quality and service that Lynsi embraced at a young age. After starting as a store associate at age seventeen, she then worked in other departments, gaining first-hand experience with almost every aspect of the family business until she became president in 2010. She has led the company through explosive growth––today, there are three-hundred and eighty stores and counting––and is deeply committed to the well-being of the In-N-Out Burger family.

In The Ins and Outs of In-N-Out, you’ll:

  • Gain key insights into why In-N-Out has maintained its very popular and limited menu for more than seventy-five-years and why it has refused to franchise or go public
  • Hear behind-the-scenes stories from In-N-Out Associates, including from one gentleman who worked in the very first store
  • Learn about the Snyder family’s Christian faith, including her grandmother Esther’s belief in the gospel and her uncle’s “born-again” experience that shaped his life and leadership at the company
  • Discover why Lynsi has been ranked as one of the top presidents in the restaurant industry and how her personal challenges have fortified her faith and shaped her dedication to servant leadership

In-N-Out Burger has drawn fiercely loyal fans––from professional chefs and burger aficionados to celebrities and scores of everyday customers––who not only crave the burgers, fries, and milkshakes but also come back again and again for the community.

Video

https://www.youtube.com/watch?v=WwXPZohTJ4w

Links

Dispatch №18

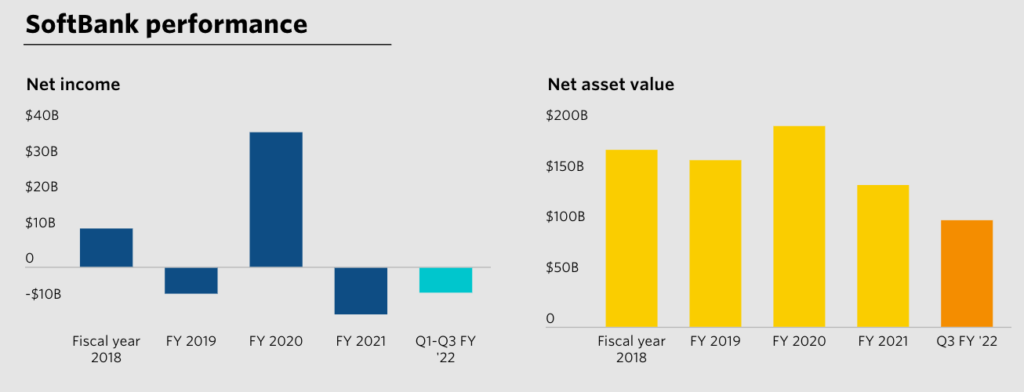
Breaking news: markets are calming down after banking turmoil as BlackRock think it’s early to relax.

Alibaba reorganization: why is it good for investors?

Fed rate peak close

Breaking news: markets are calming down after banking turmoil as BlackRock think it’s early to relax

▪️ US stocks mostly up on Monday

The S&P 500 gained 0.2%, the Dow Jones 0.6% and the high-tech Nasdaq shed 0.5%. Investors’ fears about the banking sector continue to decline. This is because regulators offer various measures to support the industry. Against this background, even the index of regional banks in America – S & P Regional Banks – rose yesterday by 0.9%.

▪️ Asia-Pacific stocks predominantly up

Asia’s broadest index (excluding Japan) MSCI AC Asia ex Japan Index rose about 0.5% today, South Korea’s Kospi added 0.6%, Singapore’s STI rose 0.4%, Hong Kong’s Hang Seng and China’s Shanghai Composite rose by 0.7% and 0.1% respectively, while the Japanese Nikkei remained virtually unchanged. All – due to the decrease in investors’ fears about the recent turmoil in the banking sector.

▪️ BlackRock: Markets are wrong about US rate cuts

The world’s largest asset manager predicts that the Federal Reserve will continue to raise interest rates. This, according to experts, will happen, even though investors, amid fears of a banking crisis, expect the opposite. BlackRock predicts a phase of slightly softer containment of inflation, but still no interest rate cuts this year. Realize market expectations, according to BlackRock, the Fed will only be able to if there is a more serious banking crisis, which is likely to cause a deep recession.

▪️ Shares of energy companies rise in price against the backdrop of rising oil prices

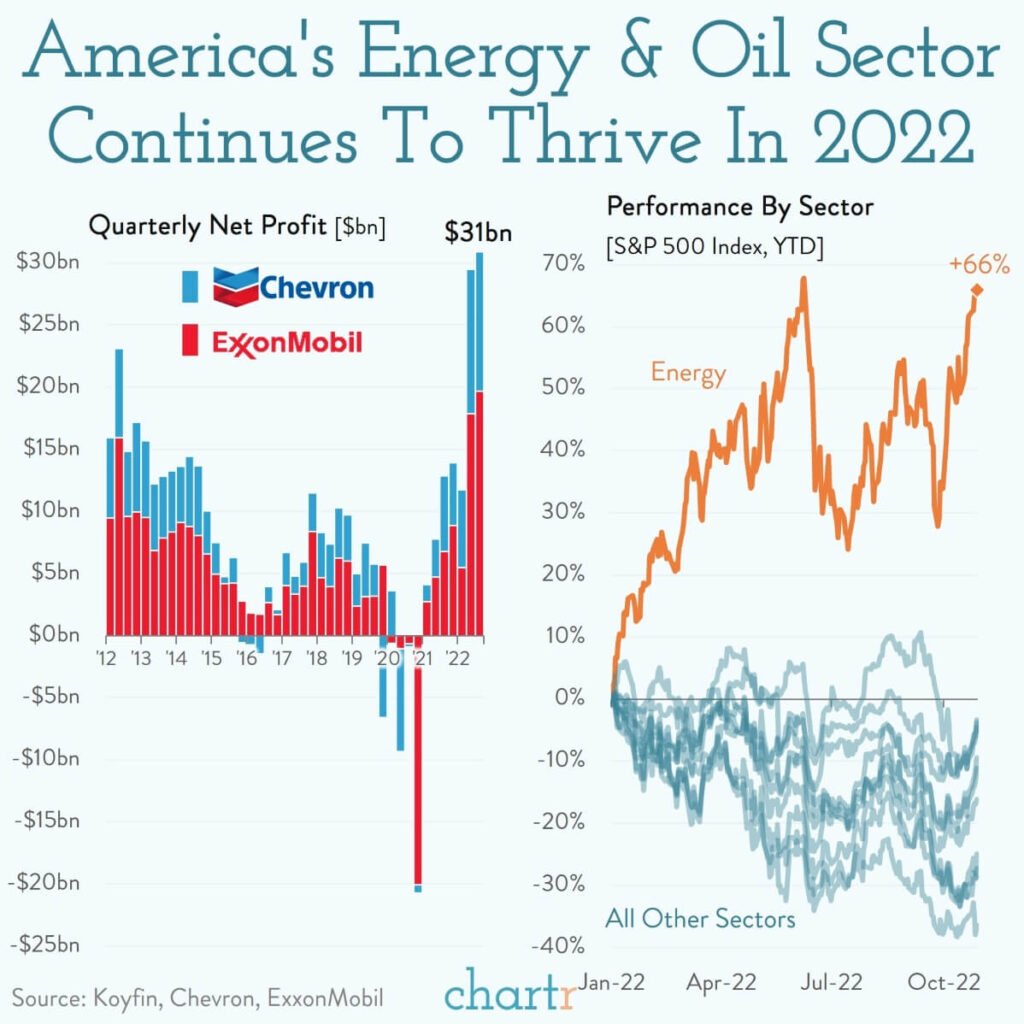
The industry index – S&P 500 Energy – rose 2.1% yesterday. Growth leaders include Schlumberger (+5%), Hess (+3.6%), Targa Resources (+3.5%), Marathon Petroleum (+3.4%) and Devon Energy (+3.2%). U.S. energy stocks traded higher on Monday as oil prices continued to rise. This was facilitated by the weakening of concerns about the banking crisis, as well as the reduction in oil exports from Iraq. As a result of yesterday’s trading, Brent futures rose 4.1% to $78.12 per barrel, while WTI contracts added 5.1% to $72.81.

▪️ Private equity deals in Asia fell 44% in 2022

In 2022, the total value of transactions in the private equity market in Asia fell to $198 billion, compared with $354 billion a year earlier, according to Bain & Company. The authors of the study attributed the decline in direct investment to a decrease in investors’ willingness to take risks against the backdrop of high inflation and geopolitical tensions. Continued macroeconomic uncertainty, along with rising costs and deteriorating financial performance of companies, will continue to weigh on investors in Asia well into 2023, according to Bain & Company.

Alibaba reorganization: why is it good for investors?

Alibaba shares are up 10% today on news that the world’s largest e-commerce player will split into 6 separate companies.

❓Why this decision was made

This announcement was preceded by the return of head Jack Ma to China. Recall that he disappeared from the public field and was shown only abroad (outside of China) after the Chinese authorities banned the IPO of his fintech ANT Group in 2020. The authorities were unhappy with the fact that large IT corporations have too wide access to the personal data of the population and create the risks of a monopoly in consumer markets. Jack Ma most likely decided to solve this problem, so he came to China, and Alibaba announced the division of business.

How the holding will be divided

We have indicated the reorganization process in the table. The public structure of Alibaba Group itself will continue to own the largest asset – Taobao Tmall Commerce Group (this includes Taobao and Tmall marketplaces). It operates in China and generates the main operating income of the holding.

The remaining 5 companies will be private, which may go on IPO in the future. Now is not the best time to enter the primary market. The only one of the 5 segments that consistently earns operating income is the cloud segment. The rest are unprofitable. However, the logistics division and the international e-commerce segment may soon become profitable, since the holding previously distributed a lot of losses to these structures, and now they will become independent. Therefore, in the future they may be attractive for investment.

❓What’s good for Alibaba and its shares

Separation of assets significantly reduces the risk of regulatory interference from the Chinese authorities. He has hung over Alibaba for the past few years and continues to threaten other major Chinese corporations. The arrival of Jack Ma is most likely connected precisely with negotiations with Chinese regulators and other large investors in Alibaba. So far, there are no legal details about the unbundling deal, but the reduction of regulatory risk will have a positive impact on the holding’s shares.

It should be noted that regulators express claims to large corporations not only in China, but also in the US and the EU. Alibaba could become the biggest asset-sharing example of the 21st century, and the practice could be followed by corporations in other countries, including the US. Therefore, the news of Alibaba’s asset split is generally positive for global equity markets.

We confirm our trade idea to buy Alibaba stock and maintain our 12-month target of 120 HKD/share. Growth potential – 29%.

Fed rate peak close

On March 22, the Fed raised the key rate by 25 bp. (up to 4.75-5%). This decision of the regulator was prompted by persistent inflationary risks. At the same time, Fed Chairman Jerome Powell said that the option of keeping the rate unchanged was also considered (against the background of the recent collapse of two American banks). He also hinted that the current promotion could be the last. Meanwhile, the reduction in the Fed’s balance sheet (quantitative tightening, QT) will continue.

❓What the regulator said about banks

The regulator reassured that the US banking system is resilient and recent events are likely to tighten credit conditions for households and businesses. This will put pressure on economic activity, hiring and inflation, which is, in essence, the equivalent of a rate hike.

❓What forecasts does the regulator give

The Fed kept the median rate forecast for 2023 at 5.1% and raised its forecast for 2024 from 4.1% to 4.3%. Expectations for 2025 have not changed – 3.1%. Thus, the regulator is planning another increase of 25 bp. and is not going to cut the rate until the end of this year.

The Fed also lowered its GDP forecast for the current year from +0.5% to +0.4% y / y, while lowering expectations for the unemployment rate from 4.6% to 4.5%. Inflation at the end of 2023 is expected at 3.3% (December forecast: 3.1%), and core inflation at 3.6% (December forecast: 3.5%).

❓How did the markets react

After the meeting, the yield on ten-year US Treasury bonds fell by 0.106 percentage points, dropping to 3.497%. The S&P 500 fell 1.6% and gold rose 1.5% to $1,970 an ounce. We still expect the growth of gold quotes as more and more regulators will be forced to move on to easing monetary policy. This year we can see gold at the level of about $2020-2040 per ounce.

❓What will happen next

The moment has come when the Fed has to simultaneously fight inflation and financial instability, which was partly caused by tightening policy. As recently as a few weeks ago, Jerome Paeull argued strongly that a rate hike above 5.25% might be needed, as economic data pointed to an acceleration in economic growth with persistently high core inflation. However, problems in the banking system have changed the situation. Now the regulator is waiting for the rate to peak at 5.25%. In turn, the market believes that the Fed rate has already reached its peak and there will be no more increases. Moreover, investors are waiting for the first rate cut at the meeting at the end of July.

We believe that the regulator will be able to quickly cope with the difficulties that have arisen in the banking system and the Fed will still bring the rate to 5.25% at the upcoming meeting in May. At the same time, we expect the regulator to start lowering the rate in the second half of 2023. So far, everything is in line with our December market forecasts for 2023.

Dispatch №17

One should fall in love with ideas, with people, or with idealism based on the possibilities that exist in this adventuresome world. The last thing to fall in love with is a particular security. It is, after all, just a sheet of paper indicating a part ownership in a corporation. Its use is purely mercenary. I learned early in my career to be skeptical and flexible, not stubborn, about a stock. I also learned to take quick, small losses rather than to get emotionally involved in a stock that was dragging me down. Some people have been extremely fortunate in the past by falling in love with something that went their way. That is not necessarily proof it will always be that way. In other words, it’s alright to be in love with a security- until it gets overvalued. Then let somebody else fall in love.

Topics of the week

What first led me to Wall Street was a desire to make money so I could buy great art and support artists. What I didn’t know when I started is that working on Wall Street can be a fascinating art in itself and one for which I was almost immediately suited.

— Roy Neuberger

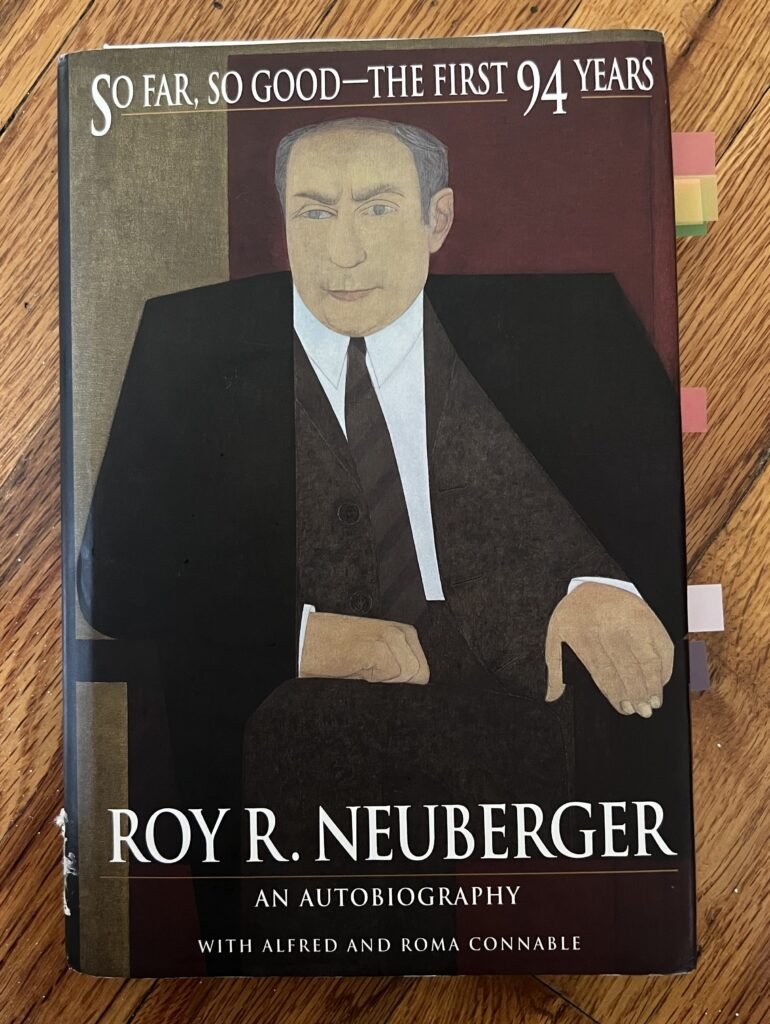
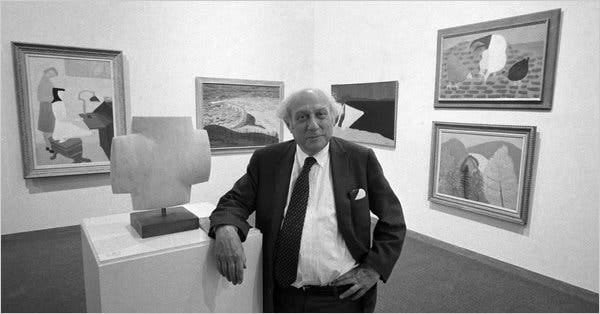
Frederik Gieschen talks about So Far, So Good — The First 94 Years, the autobiography of Roy Neuberger (co-founder of asset manager Neuberger Berman). Neuberger wrote the book in 1997, at 94 years old, while he was still working. He’d arrived on Wall Street on the eve of the crash in 1929 and was one of very few people to experience the market’s full arc from 1929 to 2008. He passed away in 2010, at age 107.

Frederik Gieschen:

Honestly, more than investment advice I was hoping for his formula for longevity. Aside from genes, what jumped out at me was his daily exercise, doing work he enjoyed, a passion that led to a rich social life, a lasting marriage, an emphasis on family, and a daily morning walk with friends.

The book is an autobiography and not an investment how-to manual. It features Neuberger’s passion for art just as prominently as his interest in the market. That said, it contains some enduring ideas about markets and life. And it’s worth pondering what someone with 68 years of experience in markets considers important: Neuberger wanted to pass on a collection of core principles, not formulas. He wanted to teach us how to think, not what specifically to do.

Neuberger came from a wealthy family and lost both his parents at a young age. He spent some time working at a department store and traveled to Europe where he discovered his love for art. He was enrolled at NYU but dropped out to work without ever getting a degree.

The book illustrates how different Wall Street was at the time. Neuberger showed up at a brokerage firm and immediately got a job as a runner delivering trade orders. He climbed the ranks and became a broker. He also had a head start by managing the accounts of wealthy relatives. Neuberger was very successful (Neuberger Berman today manages some $460bn) but it’s not a rags to riches story.

I chose Wall Street because in the 1920s, that’s where the money was.”

Neuberger was devoted to the game of markets but he placed his work in service of his true love: art.

Some people waste their lives in the constant pursuit of great wealth. As a commodity, let’s face it, money doesn’t rate as high as good health and it certainly isn’t up there with great art.

Money in and of itself has never really interested me. The driving passions of my career and my life have been the art of trading and the support of art. Money, of course, has been the by-product of trading that enabled me to purchase great art and support culture.

After reading a biography of van Gogh, who struggled to make a living during his lifetime, Neuberger dedicated himself to collecting the work of living artists. He never sold but rather donated countless works over the course of his life.

Neuberger was always clear about the higher purpose of his work on Wall Street. Accumulating wealth was never an end in itself.

I wanted to be able to buy the works of living artists, to support their work financially. … In February 1929, after returning to Paris from Berlin and Vienna, I began to make arrangements to come home to New York, determined to enter an arena about which I knew absolutely nothing: Wall Street.

Everyone knows the reply by the celebrated safecracker Willie Sutton to the question: Why do you rob banks? “Because,” he said, “that’s where the money is.” I chose Wall Street because in the 1920s, that’s where the money was.

1929 and Radio Corporation of America

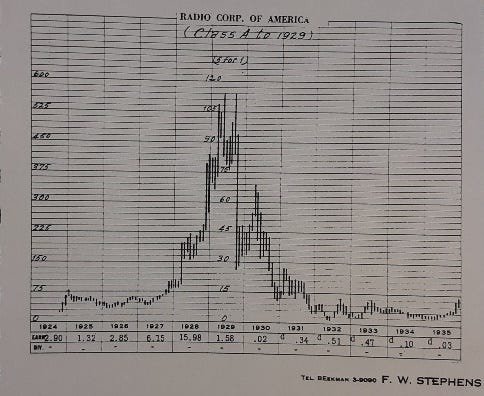
It’s funny how our first experiences with the market can shape our entire careers. Neuberger arrived on the street in 1929, during the final mad days of the bubble. One of his first big trades was to short the market darling, Radio Corporation of America or RCA. The stock was already weakening, as was the entire market, and the valuation made no sense to him.

The most actively traded stock on Wall Street at that time was Radio Corporation of America referred to as “Radio”), which evolved into RCA as we know it to-day. I studied that company more than any other. I really learned the ins and outs on a lot of different levels.

Radio Corporation of America reached a high of 574. Then it split 5 for 1. I set out to discover why the stock was so high and so active. Nothing seemed to justify the seemingly excessive price. I asked older, more experienced investors, but I received no definitive answers. People explained that we were entering the radio age-simple as that.

Neuberger shorted RCA stock worth 100% of his portfolio. It’s hard to overstate how lucky he got here. Others had shorted Radio during the bull market and been steamrolled. When the market crashed, RCA collapsed and protected Neuberger’s portfolio while those around him lost their fortunes.

This moment defined his career: Neuberger always considered himself a trader and kept hedging to protect himself — though he explicitly did not recommend shorting to his readers because one needs “a stubborn, perverse, and patient temperament.”

In many ways, the Panic shaped my current approach to the market: I am prematurely bearish when the market experiences a prolonged ascent, when everybody is pleased because they’re growing richer.

Margin leverage had been a key driver inflating the bubble and when investors around Neuberger refused to protect themselves, they could lose everything in the collapse. Neuberger drew his own conclusions:

In order to do well, you must be able to learn from the past. And you need to look at things objectively. I learned to be absolutely pragmatic and realistic during the prolonged bear market that ensued after the Panic.

I think one of the biggest problems of the 1920s was the systematic refusal by so many people to be realists. They wanted the boom to continue forever, so they failed to notice how much of it was fleeting.

Many businesses appeared to be in better shape than they actually were. Examples of failure were everywhere: The textile industry suffered a huge crash in 1924; Florida was the site of a major real estate panic in 1925 and did not recover for many years. But people refused to see the warning signs.

Simply surviving and persisting in the business proved important as well. As brokers around him left the business, Neuberger picked up their accounts.

Trader or investor?

Neuberger also reminded me of Irving Kahn, another survivor of the crash and Wall Street old-timer, who lived to be 109. They even graduated from the same high school. While Kahn was a Graham and Dodd value disciple, his style was eclectic.

“It’s impossible to reverse-engineer Irving’s investment process,” says Carl Schecter, the head of risk-arbitrage trading at Nomura Securities in New York and a long-time Kahn Brothers client. “It’s an idiosyncratic mix of top-down economic insight and bottom-up financial analysis.”

The same seems true of Neuberger who doesn’t quite fit one mold. On the one hand, he had a trader’s mindset. With his art he was happy to buy and hold forever. By contrast, “getting married to a stock can prove disastrous.”

He compared his trading style to his “youthful addiction to tennis.” You had to do your homework and be prepared to act with speed when the market presented opportunities.

You have to make fast decisions. You can’t wait to think about it overnight.

On the other hand, Neuberger discussed the importance of finding great companies that could do well over long periods of time. Unfortunately, he doesn’t offer much specific advice.

The criteria for purchase of any substantial amount of stock should remain on solid grounds that stand the test of time: (1) a good product; (2) a necessary product; (3) honest, effective management; and (4) honest reporting.

True, but not particularly helpful. Neuberger called missing Coca-Cola his ‘biggest mistake’.

Then came the biggest mistake I’ve ever made on Wall Street–a lost opportunity. I misdiagnosed the potential of a great corporation-Coca-Cola because I knew it had stiff competition from Pepsi and other soft drinks. I simply didn’t take seriously the proposition that this was a great growth company like AT&T. I am pointing out humbly that it is impossible to be right all the time on Wall Street. My perspectives on the potential of Coca-Cola were misguided, and I never should have sold it.

But he doesn’t elaborate on his analysis of Coca-Cola or other companies and business models. And holding a great company to let it compound is not consistent with one of his other principles, the stop-loss or “10%” rule:

You can’t always win on Wall Street, so you have to learn to cut losses quickly and move on gracefully. At one point, I was bullish on International Harvester.

Right after I bought it, unfortunately, it began going down, down, down and I realized I had made a mistake. I sold it the same day, lucky to take a small, quick drop rather than a big, drawn-out loss.

Getting married to a stock can prove disastrous. The 10 percent rule is sensible: If your stock starts falling, take a loss of 10 percent and start again. I take this idea very seriously, and it’s worked quite well for me. The flip side of that rule is not to be greedy with profits. Never try to guess the top.

He may have picked up this 10% stop loss rule from Gerald Loeb’s The Battle for Investment Survival, a popular post-crash trading book. “I’m inclined to say that when a new investment has shrunk by 10%, it is time to stop, look and listen,” Loeb wrote. Buy and hold seemed dead in the painful bear market that followed 1929.

My sense was that Neuberger, like other market veterans, operated with multiple mental models. He could hold a compounder like AT&T for the long run but also be a nimble trader in many other securities.

He used the stop-loss rule to protect himself from behavioral biases. Neuberger had observed too many smart people in denial in 1929. The stop-loss was a way to protect himself from that fate.

Remember how Richard Whitney watched his stocks decline in 1929 until he was wiped out? He failed to follow the 10 percent rule: If the stock is on the way down, take your loss at the 10 percent level. This rule has helped me many times. Using the money elsewhere will usually be more fruitful than maintaining a mistaken position.

One of the enduring lessons of Neuberger’s life is that nobody is bigger than the market. Ego can be absolutely deadly.

I received a real education into seeing things as they are, not as one might wish they were. I learned that the market has a rhythm of its own, like the waves of the ocean. Every few months, there is a change. Sometimes a long-term investor can ride out the ups and downs. But I’m a trader. I have to be closely attuned to the changing waves. It’s often a choppy voyage.

What we can learn from someone who survived in markets for 68 years is to be flexible, to adapt, to not let ourselves get emotional.

One should fall in love with ideas, with people, or with idealism based on the possibilities that exist in this adventuresome world. The last thing to fall in love with is a particular security. It is, after all, just a sheet of paper indicating a part ownership in a corporation. Its use is purely mercenary.

I learned early in my career to be skeptical and flexible, not stubborn, about a stock. I also learned to take quick, small losses rather than to get emotionally involved in a stock that was dragging me down.

Some people have been extremely fortunate in the past by falling in love with something that went their way. That is not necessarily proof it will always be that way. In other words, it’s alright to be in love with a security- until it gets overvalued. Then let somebody else fall in love.

A work of art

Neuberger started one of the first “no-load” mutual funds (no upfront sales commission), a novel idea at the time. Just like he was early in his focus on contemporary artists, Neuberger liked the idea of breaking with convention:

As an idealist, I don’t generally like to accept what is called conventional wisdom. I had great respect for my elders, but I learned early that everything practiced by my contemporaries was not necessarily sound.

Unsurprisingly, he considered the fund his enduring contribution to the world (like Buffett with Berkshire as his canvas).

The book is not a must-read for investors but I enjoyed it, mainly because of Neuberger’s passion, character, and the sheer magnitude of perspective and life experience he brought to the table. Its enduring message is that to master the market, you must master yourself. And if your autobiography is about a lot more than markets, that’s an indication of a rich life.

Neuberger himself pointed out not to copy what worked for him on Wall Street, that “wonderful, exciting game.” “If you do, you will go crazy,” he warns. “You have to dig for yourself, just as I do.”

It is invigorating for me to use my brain to analyze what is going on. If I have taught you how to use your brain in a different way, then I will have fulfilled the first mission of a teacher — to make oneself expendable. And you will have learned the most important lesson — how to learn.

Links to consider

Infographic

Quotes

Books that caught our attention this week

The Making of the Modern Philippines: Pieces of a Jigsaw State

by Phillip Bowring

With a fractured geography and complex identity, The Philippines is an eclectic and unique mix of culture, environment, people and politics. Known mostly for natural disasters, migrant labour and dictatorial presidents, in this book Philip Bowing shows how it is much, much more. Deftly navigating the history of this populous island republic, The Making of the Modern Philippines traces its history to define and explain its position in the modern world. Looking past the headlines of volcanoes, earthquakes and violence, it asks why has the Filipino economy lagged behind its neighbours, explores the importance of its location in geopolitics, and investigates how its deep-rooted Catholicism clashes with the Islamic consciousness of the region in which it sits. Taking the history of the Philippines from its pre-colonial era, through its Spanish and American occupations and up to the modern day, it unravels the complex politics, culture, peoples and economy of this rich and unique nation. Engaging with challenges the Filipino people face today such as federalism, revolution, Mindanao, the diaspora, capitalism and relations with China, it rediscovers the struggles, culture and history of its past to understand the present.

Amazon


Small Isn’t Beautiful

by Trevor Latimer

“Eat local” has become a popular marketing slogan in recent years, based on the idea that food grown or raised nearby is better for you and friendlier to the environment than similar products shipped in from many miles away. That slogan reflects a broader worldview suggesting that everything local, including government and knowledge, is better than what originates somewhere else. Small Isn’t Beautiful acknowledges that some things that are local are good, but denies that what’s local is always or even often better than what’s far away. “Localism” is based on an “undeserved aura of respectability, virtue, and good sense” and can produce results that are misguided or even dangerous. Particularly when it comes to public policies, decisions made at the local level are rarely superior and are sometimes unjust. Small Isn’t Beautiful exposes the supposed “virtue” of localism as a hodgepodge of weak arguments and misleading hunches. Trevor Latimer’s engagingly written and provocative book will appeal to all readers who want to understand localism beyond slogans and marketing.

Amazon


How Big Things Get Done: The Surprising Factors That Determine the Fate of Every Project, from Home Renovations to Space Exploration and Everything In Between

by Bent Flyvbjerg, Dan Gardner

Nothing is more inspiring than a big vision that becomes a triumphant, new reality. Think of how the Empire State Building went from a sketch to the jewel of New York’s skyline in twenty-one months, or how Apple’s iPod went from a project with a single employee to a product launch in eleven months. These are wonderful stories. But most of the time big visions turn into nightmares. Remember Boston’s “Big Dig”? Almost every sizeable city in the world has such a fiasco in its backyard. In fact, no less than 92% of megaprojects come in over budget or over schedule, or both. The cost of California’s high-speed rail project soared from $33 billion to $100 billon—and won’t even go where promised. More modest endeavors, whether launching a small business, organizing a conference, or just finishing a work project on time, also commonly fail. Why? Understanding what distinguishes the triumphs from the failures has been the life’s work of Oxford professor Bent Flyvbjerg, dubbed “the world’s leading megaproject expert.” In How Big Things Get Done, he identifies the errors in judgment and decision-making that lead projects, both big and small, to fail, and the research-based principles that will make you succeed with yours.

Amazon

Video of the week

Vanguard – The 8 Trillion Dollar Financial Empire | 2023 Documentary

**

Getting Rich Is Super Easy | Jeff Bezos

**

The Fake Chip Scourge

**

The Netherlands is Controlling China, And Trying To Takeover The World Economy…

[/arm_restrict_content]

Dispatch №16

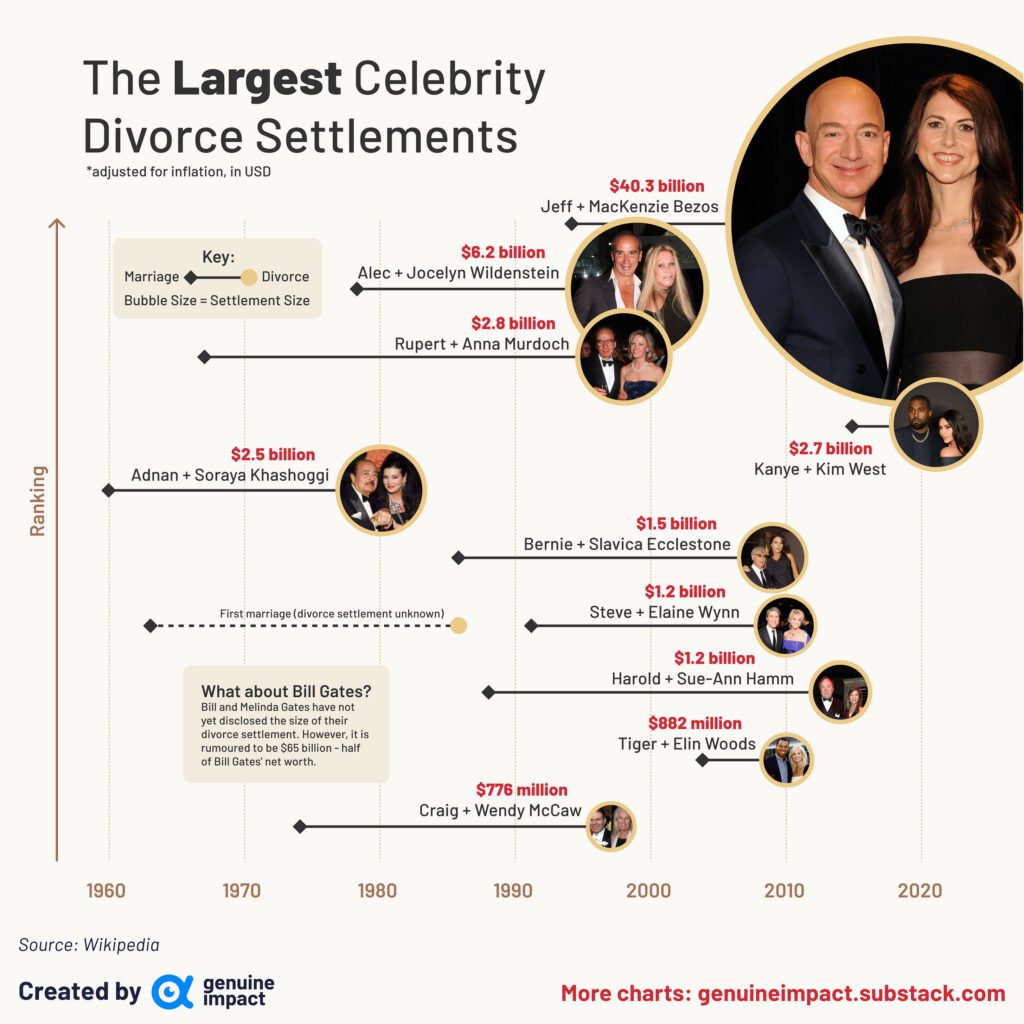
Many individuals are curious about where millionaires keep their wealth, and for good reason. By gaining insight into the financial habits of the wealthy, we can learn from their success and potentially improve our own financial situation. The data shows that millionaire households allocate approximately 25% of their wealth to their primary residence and 15% to business interests, with the remaining 60% invested in stocks, bonds, and cash. However, as households become even wealthier, the proportion invested in stocks, bonds, and cash tends to decrease, with business interests becoming the dominant source of wealth.
Topics of the week

Where Do Millionaires Keep Their Money?

Nick Maggiulli, Chief Operating Officer for Ritholtz Wealth Management LLC., published a great post.

If you’ve ever wondered, “Where do millionaires keep their money?” then you’re not alone. Many people are curious about the financial habits of the wealthy, and for good reason. Having a better understanding of how millionaires manage their money can help us learn from their successes and potentially improve our own financial well-being as well. We’ve touched on this before in one of the previous Dispatches. In his blog post, Nick dives deeper and explores the various options available to millionaires for storing and growing their wealth. From traditional asset classes to more exotic investments, we’ll take a closer look at the strategies millionaires employ to protect and grow their fortunes. Whether you’re a millionaire looking for new ways to manage your money or just someone who wants to learn from the best, this post has something for you. Here we go.

How Do Millionaires Invest Their Money?

To figure out how millionaires invest their money, I will be examining the three primary investment decisions that impact their returns (according to the late pioneer of institutional asset management David Swensen):

  1. Asset allocation: What asset classes do millionaires invest in.
  2. Market timing: When do millionaires buy/sell those assets.
  3. Security selection: How do millionaires choose which securities to buy within an asset class.

To do this, I will primarily be relying on Vanguard’s 2020 How America Invests study, which examines how affluent households (those with at least $500,000 in investable assets at Vanguard) invest their money. While not all of the households in this study are millionaires, the vast majority of them are. The median household in the study has over $1 million with Vanguard and those below the median have assets outside of Vanguard (i.e. real estate, non-Vanguard accounts, etc.) that make most of them millionaires as well.

With that being said, let’s address the first part of how millionaires invest—their asset allocation.

What Asset Classes Do Millionaires Own?

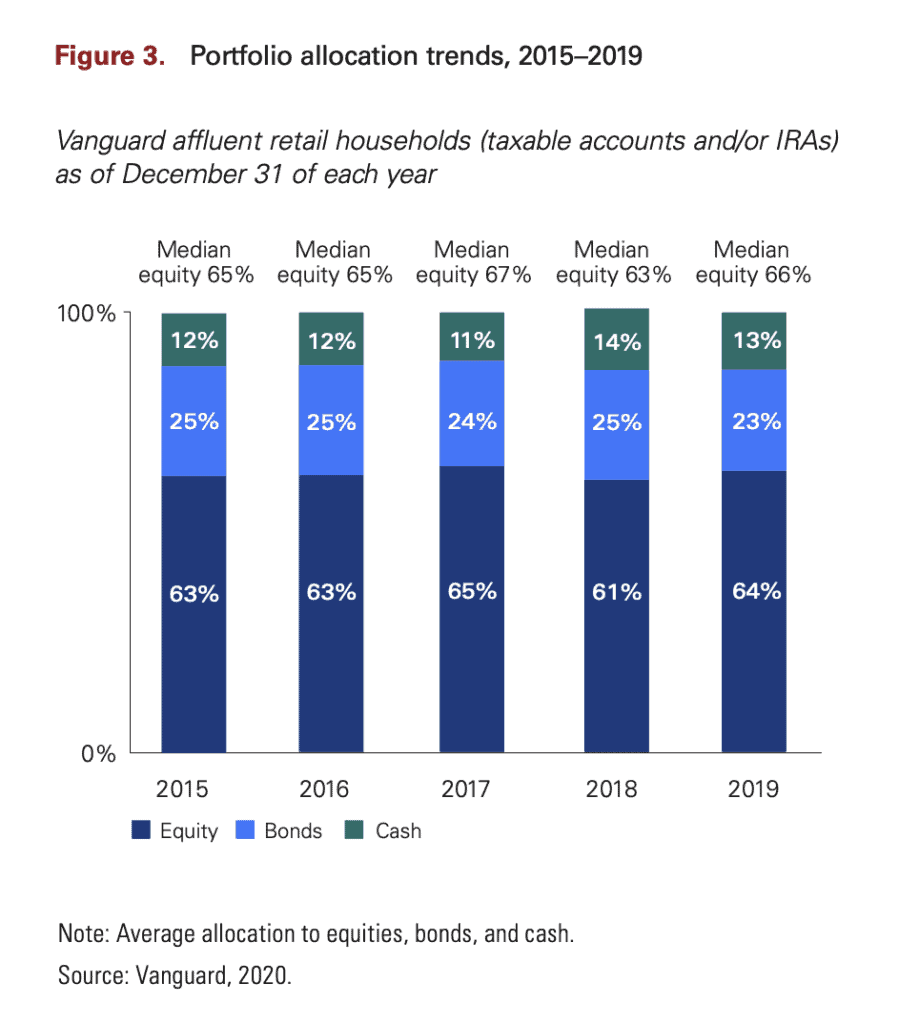
According to Vanguard, the asset allocation of a typical millionaire household is:

  • 65% Stocks (Equity)
  • 25% Bonds (Fixed income)
  • 10% Cash

As you can see in the chart below, this allocation has been relatively stable over time as well:

This gives us a good idea of how millionaires tend to invest their money within their investment accounts on average. However, it doesn’t tell us anything about how those allocations change over time within households. Since the chart above is the aggregate allocation across all households, we don’t get to see any age-related allocation changes.

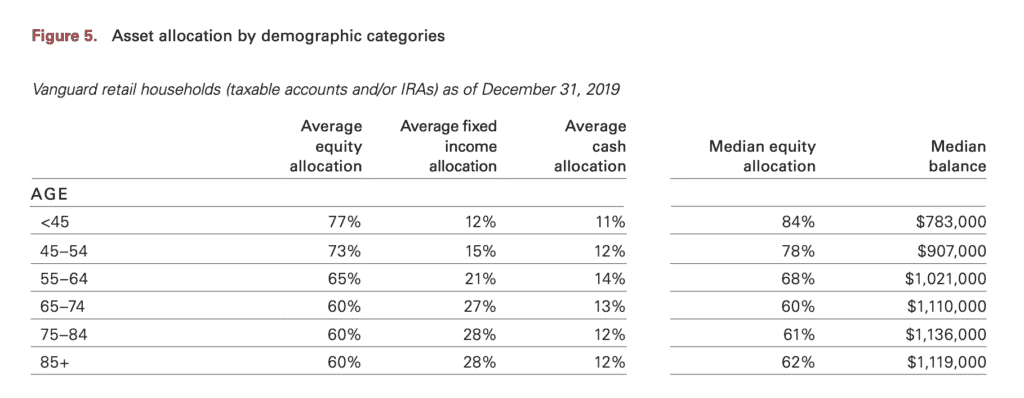
Fortunately, Vanguard provides a breakdown of allocation by household age in their study as well. We can see this in the table below which shows that households under 45 tend to allocate around 75% of their portfolios to equities, while households older than 65 allocate around 60% to equities:

What happens to the money that comes out of equities as these affluent households age? It goes into fixed income.

From the table above, we can see that the fixed income allocation of affluent households nearly doubles from age 50 to age 80. In other words, affluent households tend to go from 15% bonds to 30% bonds as they enter retirement.

But, what about other asset classes? Don’t millionaires invest a lot of money outside of stocks, bonds, and cash? According to the 2017 U.S. Trust Insights on Wealth and Worth, the answer is “Not really.”

As their study shows, high net worth households (those with over $3 million in investable assets) had the vast majority of their wealth in stocks, bonds, and cash, with less than 7% of their investable assets in alternatives:

This suggests that what we see in the Vanguard’s How America Invests study is representative of how the typical millionaire household allocates their money. They own typical asset classes and not all these exotic investments like the financial media might have us believe.

Of course, these studies exclude personal real estate and ownership of an individual business, both which can be significant. As Thomas J. Stanley and William D. Danko stated about the typical millionaire household in The Millionaire Next Door:

On average, 21 percent of our household’s wealth is in our private business.

Once we include ownership of private businesses and real estate, the typical millionaire household’s allocation to traditional asset classes like stocks and bonds is a bit lower that what has been advertised above.

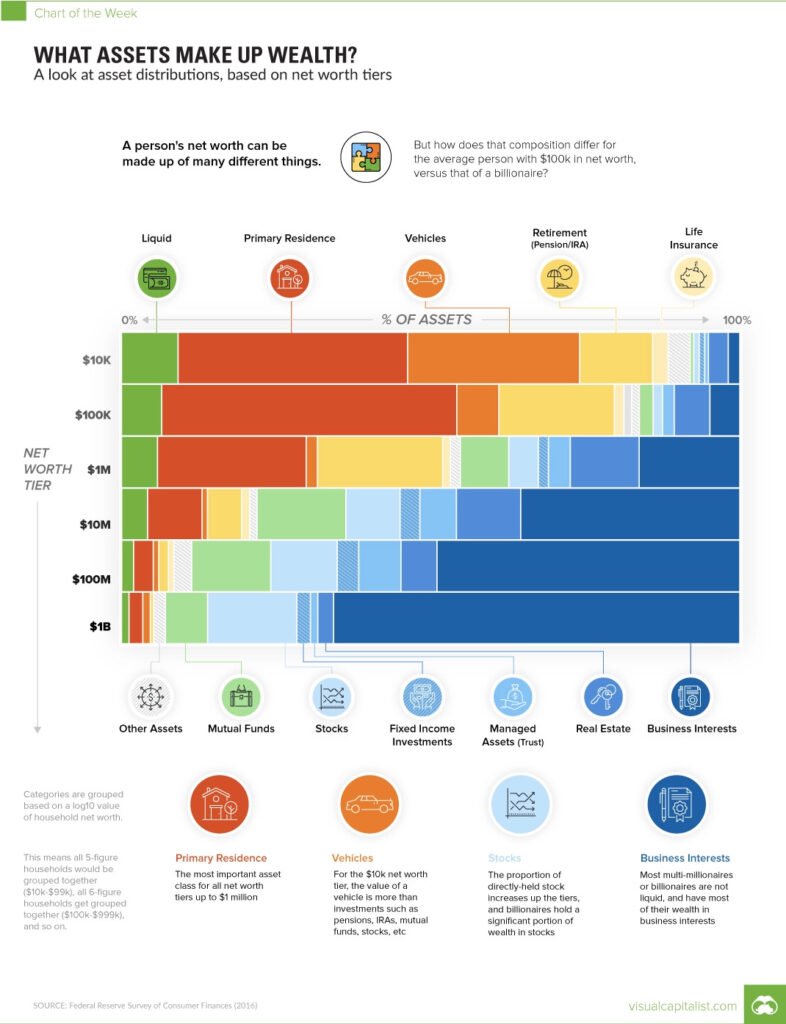
We can see this more clearly if we look at the chart below (from VisualCapitalist), which highlights how household net worth is broken out across different wealth tiers. In it we can see the percentage allocated to a primary residence, vehicles, business interests, and much more:

As you can see, millionaire households have about 25% of their wealth in their primary residence and 15% in business interests (trust me I measured the bars). This implies that the typical millionaire has a 60% allocation to stocks, bonds, and cash. More importantly, this percentage seems to decline as households get wealthier. Once you become a decamillionaire or centimillionaire, business interests began to dominate most of your wealth.

Now that we have a rough idea of how millionaires allocate their assets, let’s look at their buy and sell decisions.

Do Millionaires Try to Time the Market?

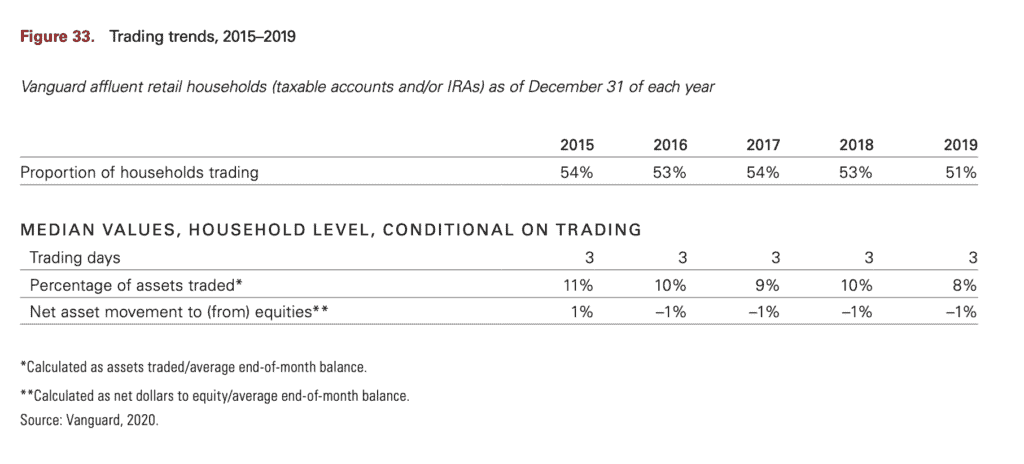
When it comes to trying to time the market, affluent households are quite tame. As the table below (from Vanguard) illustrates, a little over half of all affluent households traded their accounts within a year, and when they did they only traded about 10% of their total assets:

This suggests that millionaire households aren’t trying to time the market. And this isn’t just an artifact of the relatively calm market stretch from 2015-2019. During the market crash of March 2020, only 11% of Vanguard investors made any active trades.

And this isn’t just a Vanguard thing either. The Millionaire Next Door comes to a similar conclusion when describing the typical millionaire household (emphasis mine):

We hold nearly 20 percent of our household’s wealth in transaction securities such as publicly traded stocks and mutual funds. But we rarely sell our equity investments.

From what I’ve seen between these two data sources, it seems clear to me that most millionaires aren’t trying to time the market in any meaningful way. They invest and let it ride.

Now that we have looked at market timing, let’s examine how millionaires pick which securities to buy within an asset class.

How Do Millionaires Pick Securities Within an Asset Class?

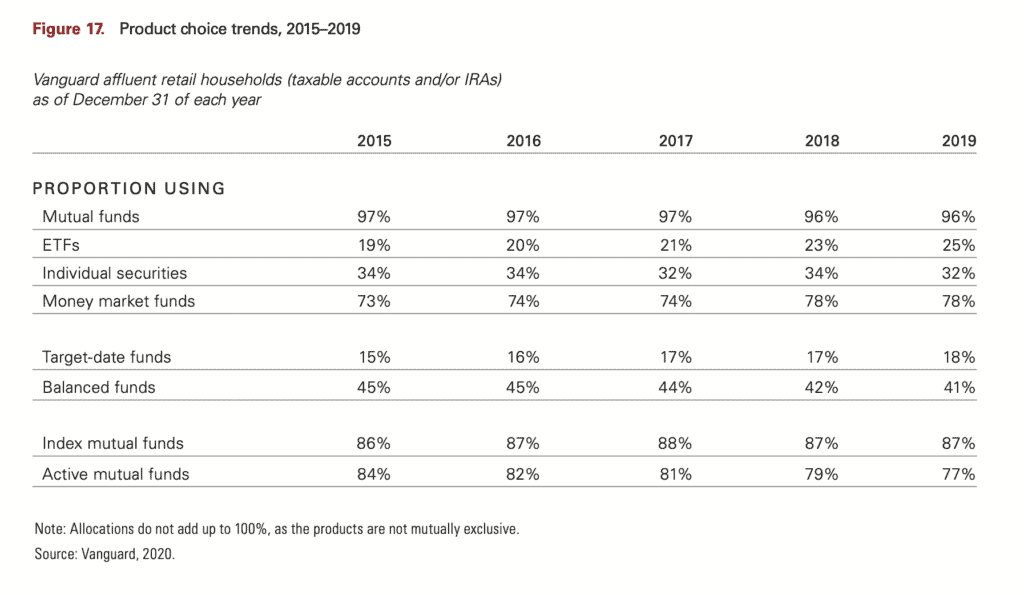
When it comes to how millionaires pick securities within an asset class, the answer is—diversification. If you look at the investment product choices that affluent households make, you will see that the vast majority use mutual funds (which tend to be diversified), with only one third of them owning any individual securities (i.e. individual stocks):

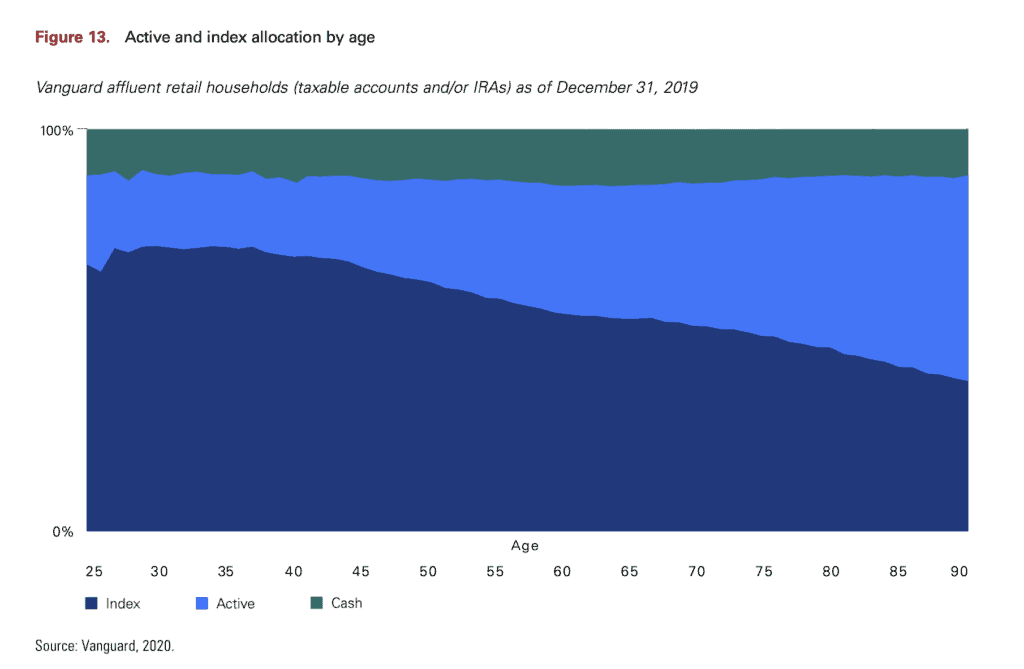
While the vast majority of affluent households diversify through mutual funds, they are not all passive investors. Though the shift to passive funds accelerated from 2015 to 2019, 77% of affluent households still owned an active mutual fund in 2019.

This might surprise you, but this phenomenon is mostly being driven by older households who tend to have more of their wealth in active strategies:

As German scientist Max Planck once said:

Science advances one funeral at a time.

Well, the same seems to be true with passive investing. Older investors, who didn’t grow up in the age of mass indexing, don’t seem to have taken to passive in the same way as younger investors as a whole. Therefore, as these older investors pass on, we should see even further adoption of passive investing in the future.

Now that we have looked at the asset allocation, market timing, and security selection decisions of millionaire households, let’s examine whether wealthier millionaires invest the same as their less fortunate counterparts.

Do Wealthier Millionaires Invest Differently?

So far I have focused our analysis on households that are right above the millionaire threshold. But, what about households that have more than just a few million dollars to their name? Do they invest differently than the typical millionaire household?

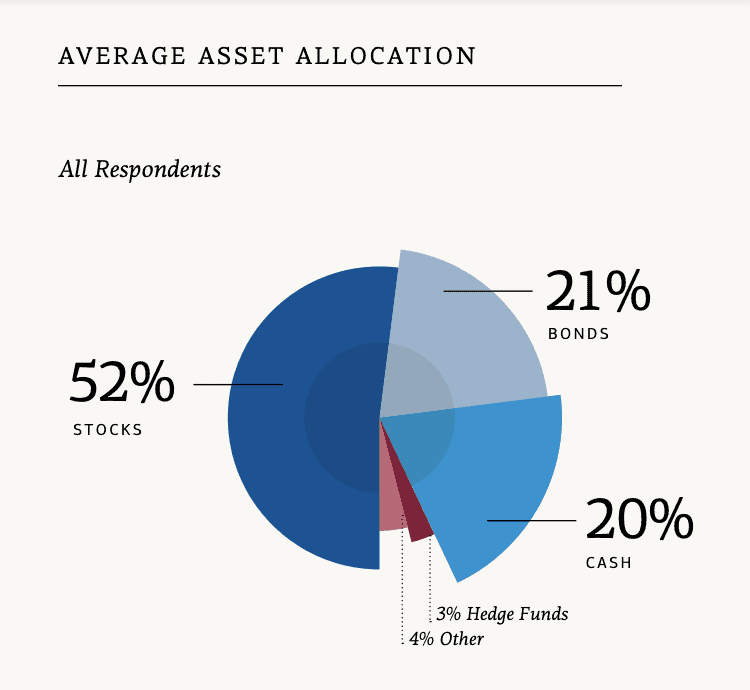
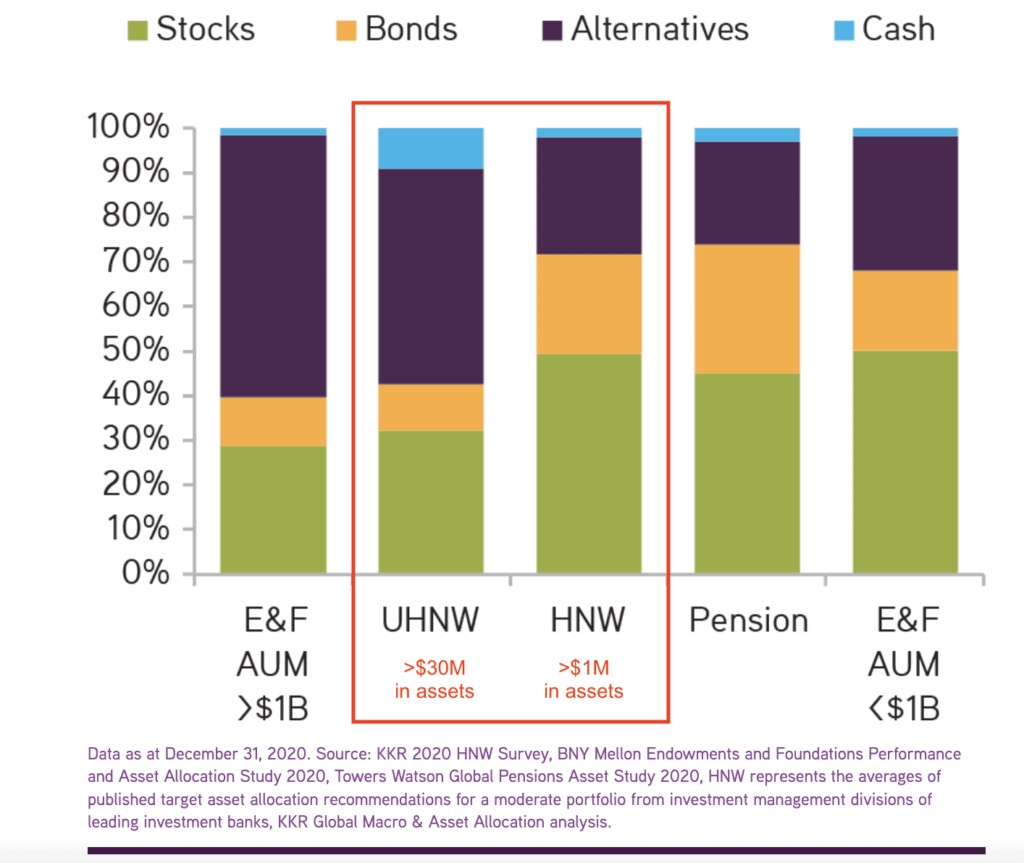
The evidence suggests that they do. This report from KKR demonstrates that ultra-high net worth investors (those with >$30 million in assets) invest more money into alternatives (i.e. private equity, hedge funds, etc.) and cash than high net worth investors (those with >$1 million in assets).

As you can see in the chart below, ultra-high net worth (UHNW) investors allocated 30% to stocks, 10% to bonds, 50% to alternatives, and 10% to cash while high net worth (HNW) investors allocated around 50% to stocks, 20% to bonds, 25% to alternatives, and 5% to cash:

I can’t necessarily explain why UHNW investors have more money in alternatives, but I have a few theories. One of them is that, as wealth increases, households tend to invest based more on status than returns. Alternative investments like private equity and hedge funds offer a sense of exclusivity that you can’t get with a Vanguard index fund.

Another possibility is that wealthier households invest in alternatives because they are the only ones that can access them anyway. While anyone with a few thousand dollars (sometimes less) can buy an index fund, you need to have serious capital to get into many of these alternatives.
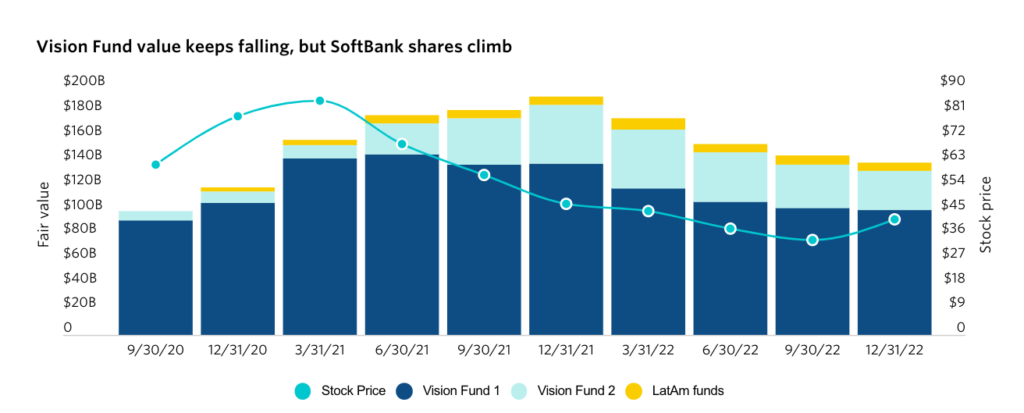
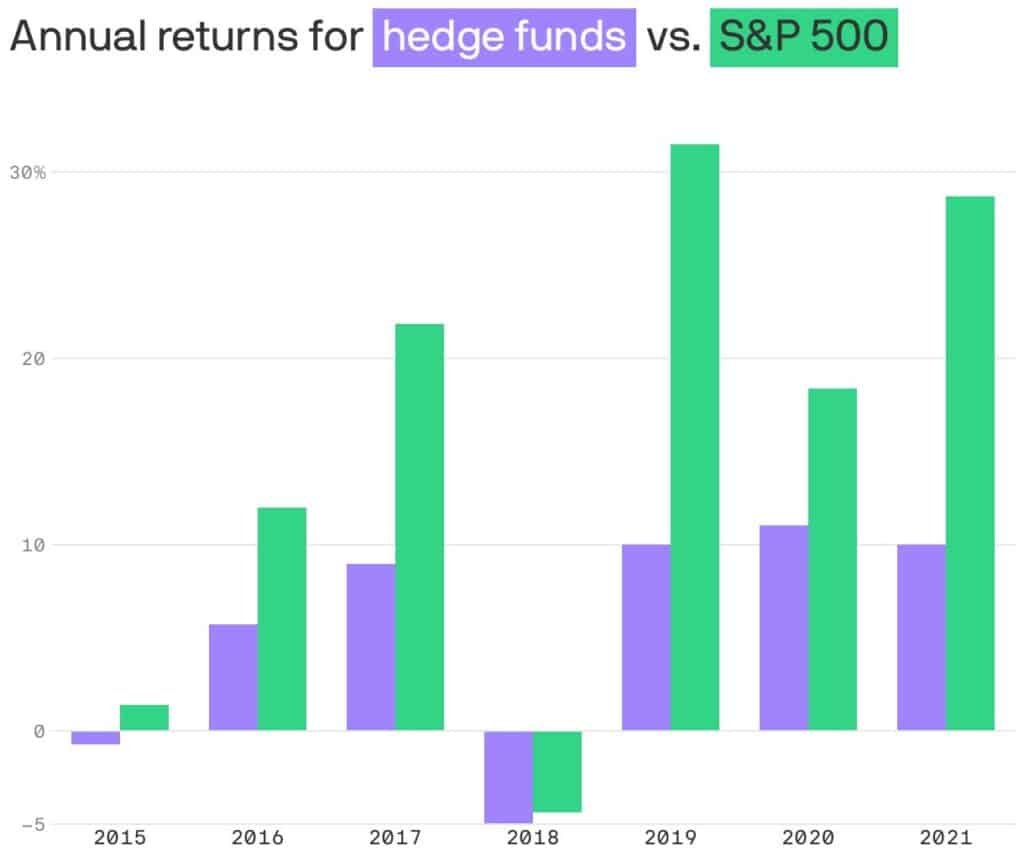
Fortunately, retail investors (i.e. you and I) don’t need alternatives to successfully build wealth. In fact, there’s a decent amount of evidence showing that public investment strategies tend to outperform private strategies, especially after fees are taken into account. For example, the chart below shows the returns generated by hedge funds and the S&P 500 from 2015 to 2021:

As you can see, the S&P 500 outperformed a basket of hedge funds in every year from 2015-2021. This is even true in 2018, the only down year during this time period! For all those hedge fund defenders that like to say, “But hedge funds will outperform in a down market!” please explain 2018.

Either way, my point stands. There is no evidence that the typical retail investor needs alternatives to build wealth. While investing in alternatives can be nice to brag about at dinner parties, I’m not in the business of bragging. I’m in the business of trying to make you richer.

With that being said, let’s conclude by discussing why investing like a millionaire won’t necessarily make you into one.

Why Investing Like a Millionaire Won’t Necessarily Make You a Millionaire

Throughout this article we have assumed that by emulating how millionaires invest their money, you too will one day become a millionaire. But this isn’t necessarily the case. Why? Because most millionaires don’t become millionaires solely based on their investment decisions. They also tend to have a high income, a high savings rate, or both. And the further you go up the wealth spectrum, the more apparent this becomes.

If you want to become a typical millionaire, like the affluent households in Vanguard’s 2020 How America Invests study, buying a diverse set of income-producing assets and earning 7% a year will work just fine.

However, if you want wealth that is orders of magnitude higher, the S&P 500 ain’t gonna cut it. To obtain extreme levels of wealth you need:

  1. A very high income (i.e. famous musician/actor/athlete, successful business owner, C-Suite executive, etc.), or
  2. A huge liquidity event (i.e. sell your business, startup equity IPO, etc.)

Possibly a bit of both. Of course, I don’t know which path will be right for you. But, I do know that investing like a millionaire won’t necessarily make you into one.

Source

Links to consider

Infographics

Quotes

Books that caught our attention this week

The Connections World: The Future of Asian Capitalism

by Simon Commander and Saul Estrin

A central feature of modern Asia that trumps differences in economic and political systems is the web of close relationships running between and within business and politics; the connections world. These networks facilitate highly transactional interactions yielding significant reciprocal benefits. Although the connections world has not as yet seriously impeded Asia’s economic renaissance, it comes with significant costs and fallibilities. These include the creation and entrenchment of huge market power and the attenuation of competition. They in turn hold back the growth in productivity and innovation that will be essential for further development. The connections world also breeds massive inequalities that may culminate in political instability. The authors argue that if Asia’s claim to the 21st century is not to be derailed, major changes must be made to policy and behaviour so as to cut away the foundations of the connections world and promote more sustainable economic and political systems.

Amazon


All-in On AI: How Smart Companies Win Big with Artificial Intelligence

by Tom Davenport and Nitin Mitta

Written by bestselling author Tom Davenport and Deloitte’s Nitin Mittal, All-In on AI looks at artificial intelligence at its cutting edge from the viewpoint of established companies like Anthem, Ping An, Airbus, and Capital One. Filled with insights, strategies, and best practices, All-In on AI also provides leaders and their teams with the information they need to help their own companies take AI to the next level. If you’re curious about the next phase in the implementation of artificial intelligence within companies, or if you’re looking to adopt this powerful technology in a more robust way yourself, All-In on AI will give you a rare inside look at what the leading adopters are doing, while providing you with the tools to put AI at the core of everything you do.

Amazon


China’s Rise in the Age of Globalization: Myth or Reality?

by Jianyong Yue

This book deconstructs a series of myths surrounding China’s economic rise. The first myth is that globalization led directly to China’s rise; the second is that China is another East Asian developmental state; the third that China’s market reform had been implemented in an incremental way; and fourth that China’s ‘resilient authoritarianism’ has been effective in ensuring the country’s economic and political transformation. Yue argues that the China model is one of ‘crony comprador capitalism’ that has hindered the country’s attempts at economic and political modernity. It is argued that the United States’ strategy of integrating China into the international system is self-defeating in the long run; not because such an approach has created a ‘restless empire’ capable of challenging US primacy, but because the Chinese ‘miracle’ has subsequently backfired on the liberal order created after World War Two. Covering the entire reform period from the end of the Cultural Revolution in 1976 to the present day, the author calls for readers to rethink globalization and leave more policy space for China and the developing nations to pursue national development through internal integration, which is more conducive to democratic transition and global peace.

Amazon


Dinner with the President: Food, Politics, and a History of Breaking Bread at the White House

by Alex Prud’homme

Some of the most significant moments in American history have occurred over meals, as U.S. presidents broke bread with friends or foe: Thomas Jefferson’s nationbuilding receptions in the new capital, Washington, D.C.; Ulysses S. Grant’s state dinner for the king of Hawaii; Teddy Roosevelt’s groundbreaking supper with Booker T. Washington; Richard Nixon’s practiced use of chopsticks to pry open China; Jimmy Carter’s cakes and pies that fueled a détente between Israel and Egypt at Camp David. Here Alex Prud’homme invites readers into the White House kitchen to reveal the sometimes curious tastes of twenty-six of America’s most influential presidents, how their meals were prepared and by whom, and the ways their choices affected food policy around the world. And the White House menu grew over time— from simple eggs and black coffee for Abraham Lincoln during the Civil War and celebratory turtle soup after and squirrel stew for Dwight Eisenhower, to jelly beans and enchiladas for Ronald Reagan and arugula for Barack Obama. What our leaders say about food touches on everything from our nation’s shifting diet and local politics to global trade, science, religion, war, class, gender, race, and so much more.

Amazon

Video of the week

Vitalik on Starting New Countries and Improving Yourself | The Network State Podcast with Balaji #1

**

Marc Andreessen – AI, Crypto, Elon, Regrets, Vulnerabilities, & Managerial Revolution

**

Intro to American Dynamism

**

AI is Creating Massive Entrepreneurial Opportunity W/ Emad Mostaque | EP #16 Moonshots and Mindsets

**

Japan’s EUV Failure

**

Why China is losing the microchip war

**

The World In 2030

Time to Evolve

Executive Summary:

The wealth industry is on the cusp of the next evolution stage towards “Wealth Management 3.0”. To tap into the substantial revenue pools across wider wealth brackets and customer segments, wealth managers need to diversify and modularize their service and operating models, taking full advantage of technology. This will help address the fundamental growth and profitability challenges the industry faces.

For over a decade many wealth managers have put their growth focus on the ultra high net worth (UHNW) and higher high net worth (HNW) segments, thus not prioritizing less wealthy clients. In their home markets, wealth managers also had propositions for “affluent” clients, but in practice they mainly focused on the lower HNW segment. Only players with a premium brand or strong investment banking capabilities have been able to profitably grow in the highest wealth band segments, as the UHNW market as a whole is both hard to scale and highly competitive. At the other end, the lower HNW and affluent segments have been undervalued and underinvested in, which has limited value creation at the industry level. Wealth managers are increasingly realizing that they are leaving money on the table in the lower segments. Indeed, we see a revenue pool of ~$230BN in the lower HNW and affluent segments.

We believe the next decade will be about the transformation to a scalable and modular wealth management proposition. Facilitated by technology, wealth managers can make superior financial advice and investments accessible to a more diverse client base at lower, differentiated costs to serve. Clients can pick and choose different modules of advice, products and services to create their own, personalized solution. Wealth managers will support their clients along the journey through different channels, from human- to digital led. Digital solutions will also form the base layer to cater to more traditional, higher wealth bracket clients, who increasingly expect enhanced digital experiences along with traditional human led bespoke service offerings.

For many wealth managers, this will require significant change and investment in their coverage and service models as well as operating models and technology in order to win market share profitably in the future. Leading firms which are accelerating the transition to Wealth Management 3.0 have been investing a high single-digit percentage of their revenues in this transformation effort and are planning to continue to do so for the next 3 to 5 years.

For asset managers, the wealth management channel becomes ever more important. We expect the share of the wealth and retail client segment of total assets under management (AuM) to grow from 58% to 64% in the next 5 years. Asset managers face fundamental choices: partner and distribute through wealth managers, build captive digital-led wealth management distribution solutions, or establish open platforms geared towards this segment. A combination thereof may also work for some. Each model comes with benefits and drawbacks, but they all require re-architecting the wealth channel and associated operating model.

Macroeconomic and geopolitical regime shifts to accelerate transformation

After a decade-long bull market across asset classes (supporting ~9% CAGR of industry AuM), the market outlook is much more uncertain and muted (we see ~4-5% CAGR over the next 5 years). There is a considerable risk of sustained inflation and much tighter liquidity disrupting economic growth. Moreover, the war in Ukraine raises the prospect of a new era of geopolitical escalation and deglobalization, not only in terms of supply chains but also asset allocation.

This regime shift will accelerate the transformation of service and operating models, as complexity, margin and cost pressures intensify. At the same time, client demand continues to evolve rapidly towards new products and features such as ESG, private markets and digital assets, more personalization, and seamless digital and hybrid experiences. As a result, technology will play an ever more critical role in this transformation.

Substantial opportunities and challenges for both wealth and asset managers

We see “Wealth Management 3.0” as this next stage of evolution triggered by the paradigm and regime shifts outlined above. Over the last couple of decades, wealth managers have successfully moved to more digitalized, data- and IT-driven models (“Wealth Management 2.0”) from their brick & mortar, paper-based, white-glove only origins (“Wealth Management 1.0”). The next stage will be defined by substantial modularization and diversification of offerings, service models and operating models, allowing lower, more differentiated costs to serve – all facilitated by technology.

Wealth Management 3.0 is the amalgamation of trends across these key areas: The client scope is broadening to include client segments in lower wealth bands as well as segments with more diverse needs. Channels and coverage models are diversifying and more clearly differentiating into digital-led propositions, hybrid models with pooled advisors and specialists, and the traditional human-led approaches. The product universe is continuing to broaden, encompassing alternatives and private markets, ESG and digital asset investments. Wealth managers’ solutions and service offerings continue to be modularized, enabling better customization to specific client needs. To lower and differentiate costs to serve across models, wealth managers need to continue investing in more efficient operating models and technology, streamlining and automating key client journeys, processes and value chain steps front-to- back. They will move from monolithic legacy core banking systems to more modular architectures centered on an aggregation layer that leverages capabilities from legacy as well as new, third-party and partner components. Advanced technology such as Cloud and API, and potentially distributed ledger technology (DLT), will need to be leveraged for fast deployment and better interaction across the wider wealth management ecosystem.

Wealth managers: three priorities in Wealth Management 3.0

We see three priority investment areas for wealth managers to accelerate their transition:

1. Coverage and service model: Introduce full omni channel capabilities, complementing human-led with distinct hybrid and digital-led interaction models.

2. Delivery model: Make delivery more flexible, differentiate and lower costs to serve clients through operating model and tech transformation. A wealth manager’s costs to serve an average client today in the traditional UHNW/HNW bracket is $8-20K (and we expect this to remain rigid for traditional human-led premium propositions), but this can drop to $2-8K in a hybrid model and $0.5-2K in a digital-led model.

3. Value management: Create transparency on client-level economics, develop a systematic approach to measure, manage and communicate value creation with the support of digital dashboards with real-time information. This will enable dynamic management of revenues, costs and profit- ability at the product, advisor and client level.

The future success of wealth managers will be determined by exe- cuting on these priorities while keeping sight of their primary pur- pose of protecting and building clients’ wealth in a more uncertain environment. We acknowledge that several wealth managers have already started on the path to Wealth Management 3.0, by offering digital-led service models to affluent clients or hybrid propositions.
Asset managers: from intermediation to integration

As the wealth channel becomes more dominant and wealth man- agers transform their service and delivery models, asset managers need to rethink their positioning with wealth managers and ultimately the end clients. We expect a significant shift in the way they interact, from a simple intermediated distribution between an asset manager’s wholesale team and the wealth manager’s fund selection team towards a deeper technical integration. This will support delivery of more customized content, products and solutions, enabling a more personalized end-client experience at lower costs. We expect a few asset managers will create their own end-to-end wealth ecosystem with direct captive or open digital investment and wealth management platforms.

Despite the opportunity for direct distribution models, we expect intermediated channels via wealth managers to dominate. A strategic priority of asset managers will be refining the interface with wealth managers and adapting their operating models accordingly. We see three emerging themes that asset managers need to address to succeed:
1. Increased importance of integration and customized con- tent: In selecting asset managers, wealth managers will place increased weight on the ability to build technical integrations with their own operations to streamline content delivery, facilitate development of customized products and outcome-oriented solutions. Enhanced end-to-end client experience through more tailored experiences and reporting capabilities will also matter.

2. Technological adoption and sophistication as drivers of economics: Technological capabilities are becoming more important than pure scale as a driver of operational efficiency, allowing smaller players to compete more effectively against scale players. Asset managers need to invest into optimizing the application landscape, employing cloud-optimized technology infrastructure, creating a lean, flexible data environment, and renewing focus on identifying opportunities for outsourcing and managed services across the value chain. Scale advantages we expect will remain critical when distributing and servicing the global wealth management players in the medium term (e.g. to engage and explain products to stakeholders across continents), though we see a possible opportunity for tech savvy managers to narrow this advantage by deploying these new technological capabilities.
3. Supercharging advisors and clients: As end-clients inWM 3.0 need more (digital) guidance on a broad suite of products and a higher quality digital customer experience, asset managers must develop the (digital) content capabilities that truly elevate their advisor partnership. Tailored market insights, data and analytics, and better access to investments through digital- and human-led channels and portals will enable advisors to deliver value to their clients across the full lifecycle.

The Wealth Report 2022 | Knight Frank

Not with standing uncertain times, have still seen substantial wealth creation globally with the number of people with net wealth of US$30 million or more increasing by almost 10% last year. We offer our perspective on current trends and opportunities and look to the future to help guide clients through evolving real estate markets. What has become clear during the pandemic is that wealth cannot exist in a bubble. We need to be cognisant that inequality levels are increasing, and that the battle against climate change has reached what many now regard as a tipping point.

I am therefore pleased that this edition of the report features some incredibly thought-provoking contributions from those at the forefront of the struggle against what are arguably some of the biggest issues facing the world today. From the CEO of Prince William’s ground-breaking Earth shot Prize initiative to one of the earliest female technology pioneers and philanthropists, to mention just two,

I hope you find their insights as inspiring as I did. Technology moves forward ever more rapidly and we try to keep up with this by reporting on the brave new world of the metaverse and the opportunities offered by a raft of new crypto investments.

Knight Frank also continues to move forward. We are delighted to have expanded our Private Office network into New York and Singapore to work alongside our London and Dubai private client teams, established a new commercial alliance in the

US and set ourselves an ambitious net zero target. If we can help you achieve any of your targets or aspirations, please do get in touch. The Private Office and wider Knight Frank network would love to be of assistance.

Rory Penn,

Head of Knight Frank Private Office

Latin America Digital Transformation Report 2022

Cautious optimism. Curiously, our mixed emotions about the current state of the market mirror how tech founders and workers are feeling this year. Our optimism is rooted in the conviction that digitalization is a secular force transforming Latin America for decades to come. Whether we are drunk at the peak (last year) or hungover in the trough (this year), when we zoom out from the cycle of the day, the trendline is clearly up and to the right.

As our Digital Transformation Index shows, the region’s technology ecosystem stands to grow by an order-of-magnitude as it catches up to the likes of India, China, and even the US, all of which began their journeys long before us. Value creation from tech in LatAm will be measured in the trillions of dollars.

The foundation for long-term growth is rock solid: LatAm is ahead of China in internet penetration and leads globally in digital adoption for most internet services and digital media. Capital, long a barrier to growth, is no longer scarce even after a halving of venture funding from 2021 peaks. Despite the market downturn, human capital still flocks to tech, with students at top schools reinforcing their preference to work in tech above all other fields.

Perhaps most striking is how the pandemic-sparked digital boom has persisted in Latin America, representing a permanent leap forward while more developed markets like the US are now reverting to pre-pandemic trendlines. This great leap forward in digital adoption goes beyond e-commerce and food delivery and is seen across all areas of society – from digital banking usage to telemedicine.

After experiencing the future, for Latin Americans there is no going back to waiting in line at the bank branch or at the doctor’s office.
If there’s a reason why optimism runs through our veins as entrepreneurs, there is equally good reason for the caution with which such optimism should be tempered. As Tom Jobim warned us, “Brazil is not for beginners,” and, in this year’s market downturn, neither is the rest of the world.

After years of pumping steroids into the veins of the world economy, Central Banks pressed the brakes as inflation finally reared its head. Asset prices worldwide adjusted abruptly, and tech companies were no exception – with cash flows further into the future, they felt the pain especially severely as investors questioned the unwinding of this economic adjustment. Venture funding eased up and founders that the market encouraged to grow at all costs only six months ago are now told to focus on margins.

Our research shows that founders are tightening their belts, but most likely not enough given the uncertain global and regional backdrop. Yet, encouragingly, historic data shows that a pot of gold (or bitcoin) may await us at the end of the rainbow if we exercise enough caution to make it there.

The data shows that businesses that survive and get funded in bear
markets like these are significantly more likely to become large,
independent public companies. But ensuring survival is far from an easy feat and finding balance is key this year.

Amidst all the dynamism, this year we found ourselves drawn to explore three different areas of opportunity: for Fintech, Latin America’s world-class performance continues. A rising tide for B2B innovation accelerated by infrastructure buildout and record-breaking adoption of Brazil’s instant payment system Pix define this continued success. Moreover, a new wave of entrepreneurs is breaking barriers for SMB digitalization in Latin America, bridging the gap between the abnormally high number of SMBs in the region and the equally shy value they create for the economy. Finally, for Crypto and web3, while it’s still early days, Latin America is perhaps the most fertile
ground for the application of successful use cases.

We are excited to have you join us in this third edition of the Report.
Enjoy the ride!

The art of AI maturity

In fewer than 70 years, artificial intelligence (AI) has evolved from a scientific concept to a societal constant.

Computer scientist John McCarthy coined the term “artificial intelligence” in 1955, proposing that, “every aspect of learning … can in principle be so precisely described that a machine can be made to simulate it.”

Today, so much of what we take for granted in our daily lives stems from machine learning. Every time you use a wayfinding app to get from point A to point B, use dictation to convert speech to text, or unlock your phone using face ID … you’re relying on AI. And companies across industries are also relying on—and investing in—AI to drive logistics, improve customer service, increase efficiency,
empower employees and so much more.

Despite these ever-expanding use cases, when it comes to making the most of AI’s full potential and their own investments, most organizations are barely scratching the surface.

In fact, only 12% of firms have advanced their AI maturity enough to achieve superior growth and business transformation, according to Accenture’s extensive analysis of approximately 1,200 companies globally. We call them the “AI Achievers.”

Another 25% of firms are somewhat advanced in their level of AI maturity, while the remaining 63% (the majority) are still
mostly testing the waters.

This journey to AI maturity has been in high gear for years. Pre-pandemic (2019), AI Achievers already enjoyed 50% greater revenue growth on average, compared with their peers. And in 2021, among executives of the world’s 2,000 largest companies (by market capitalization), those who discussed AI on their earnings calls were 40% more likely to see their firms’ share prices increase—up from 23% in 2018, according to analysis by Accenture.

ESG: A key driver to build business resilience & competitive edge

Data-driven Quarterly insights Highlighting Key Trends in ESG.

Filings Analytics

ESG emerged as the top theme in company filings. There has been a rising focus on SDG 16 (Peace Justice and Strong Institutions) amidst current geopolitical tensions and sustainability-driven investments.

Job Analytics

Leading sectors with the highest active jobs in ESG include aerospace and defense, automotive, banking and payments, construction, and
consumer. Companies are actively looking to establish ESG-related expertise and alignment with external best practices.

Deals

The VC funding is primarily directed towards sustainable packaging, energy consumption optimization, employee communication solutions, residential energy storage, decarbonization of buildings, and carbon capture. US and Germany lead the ESG-related investments.

Social Media Analytics

EVs, food security, biofuels, and sustainable businesses are some of the trending social media topics. ESG discussions were led by key events such as a federal judge ruling to revoke Gulf of Mexico oil & gas, the energy transition debate at the World Economic Forum event, and the concern over the increasing consumption of fossil fuels.

Patents & Innovations

The VC funding is primarily directed towards sustainable packaging, energy consumption optimization, employee communication solutions, residential energy storage, decarbonization of buildings, and carbon capture. US and Germany lead the ESG-related investments

Road to Next

Last year saw record-breaking tallies, and dealmaking this year has been unexpectedly resilient: At $12.9 billion across 461 deals per PitchBook, 2022 so far is not on pace to match last year’s record dealmaking numbers, but it compares favorably to previous years.

Digitalization is imperative: Life sciences executives are
renovating their tech stacks and implementing the latest tools
to achieve efficiencies, cost reductions, and innovation.

Current market conditions are not insurmountable but may
require more complex strategies: Fundraising efforts are still
succeeding for some of the bestprepared enterprises, and even
though liquidity is largely on hold due to the slowdown, life sciences
companies are forging ahead with an eye on longer-term outcomes.