
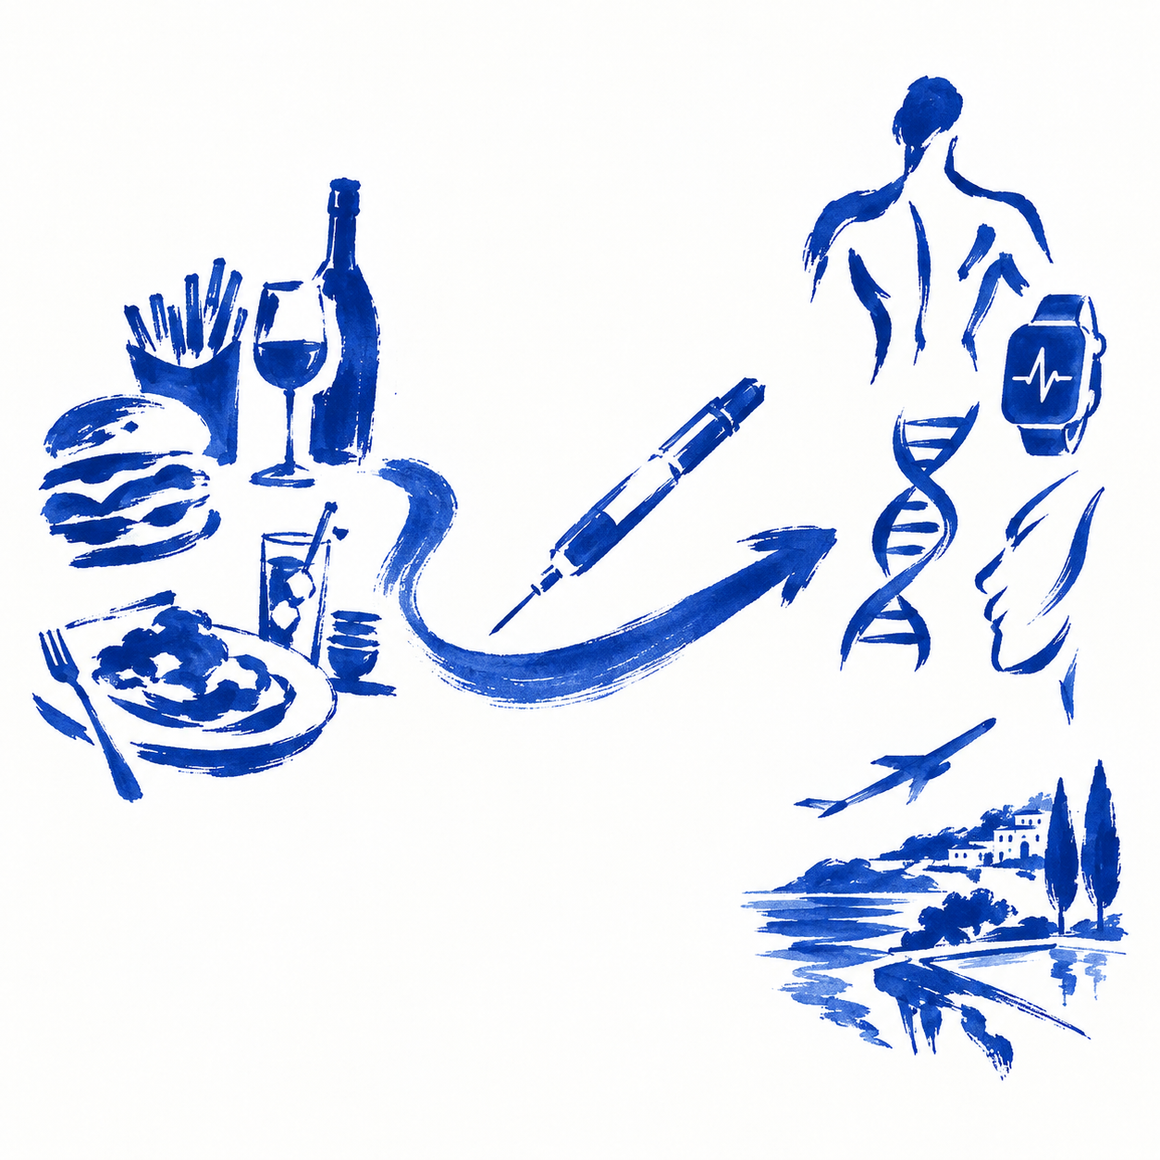
The global expansion of GLP-1 therapies — such as Ozempic, Wegovy, and Mounjaro — is vastly misunderstood. This is not a pharmaceutical headline about weight loss or a clinical story — it is a $200 billion structural reallocation of global consumer capital. As biological hunger is systematically moderated across affluent markets, household expenditure is undergoing a permanent portfolio reset. Capital is fleeing volume-driven indulgence — processed foods, mass dining, and bulk alcohol — and compounding into a high-margin “longevity stack” centered on muscle preservation, real-time health intelligence, regenerative aesthetics, and vitality-focused luxury travel.
Investment bank modeling projects massive global market penetration over the coming decade:
- J.P. Morgan forecasts that the global incretin market will reach US$200 billion by 2030, with up to 30 million Americans actively taking GLP-1 treatments.
- Morgan Stanley projects that the global GLP-1 market for obesity and type 2 diabetes will reach US$190 billion by 2035, assuming nearly 30% of the eligible population in the US and 10% in international markets adopt these therapies.
- PwC UK (Strategy&) research indicates that UK adoption is on track to increase two-and-a-half times from 5% (c.3 million adults) to 13% (c.7.4 million adults) by 2027, accelerated by the regulatory approval of oral pill formulations.
- EY-Parthenon modeling shows that in Australia, where 10% of adults currently report using GLP-1 medications, long-term adoption could expand to over seven million Australian adults (30.1% of the adult population) by 2036 under a broad clinical coverage scenario. UNSW clinical tracking already confirms a baseline of at least 500,000 Australian adults regularly taking GLP-1s monthly.
The underlying economic mechanism is not simply that consumers eat less; it is that discretionary household capital is moving out of volume-based consumption and compounding into high-margin wellness, performance, and longevity sectors.
In the US, research by PwC found that after 6 to 8 months on GLP-1 medication, average household grocery expenditure declines by 6% while apparel spending increases by 10%. Furthermore, consumer data reveals that 28% of GLP-1 users treat their treatment and lifestyle routine as a protected discretionary expense that they refuse to cut even under macroeconomic pressures.
As Brian Man, Retail and Consumer Industry Leader at PwC Australia, explains regarding this fundamental consumer shift:
“The traditional approach to health was episodic, reactive, and led by industry. Now it is a daily priority that’s proactively managed, personalised, and driven by the consumer and data. Today’s consumers live in a world of constant feedback about their nutrition, fitness, and rest. This has allowed them to judge their wellbeing through a broader set of indicators, and redefined how we shop, eat, exercise and recover. In the pursuit of sustained results, consumers are no longer thinking about health in silos. GLP-1s are an example of how one treatment can lead to wider changes in lifestyle. The medication becomes a trigger for them to reconsider other everyday choices from the foods they buy, to their workout routines, the clothes they wear, and the beauty products they use.”
The Wellness Stack: Reallocating Household Capital
When appetite drops by roughly 20%, discretionary household budgets do not contract uniformly—they undergo a distinct portfolio reallocation. Capital previously spent on impulse snacks, high-calorie dining, and bulk alcohol purchases is redirected into a personalized “wellness stack” spanning high-density nutrition, fitness coaching, aesthetic care, and sleep optimization.
A national study of 500 US adults by The Consumer Collective reveals a stark divergence in health spending:
- Consumers taking GLP-1 medications spend an average of US$449 per month on fitness across categories—nearly four times the US$120 per month spent by non-users.
- 81% of GLP-1 users maintain paid gym memberships, compared to just 43% of non-users.
- 63.4% of users buy new clothing as a direct result of body composition shifts, with over two-thirds dropping at least two sizes.
In the grocery aisle, total food volume drops, but basket value is supported by premiumization. PwC UK data shows that while 60% of GLP-1 users buy less total food, 30% actively trade up to higher-quality branded items and 20% trade up to premium private-label lines. Specifically, 51% of users increased consumption of nutrient-dense foods, 54% increased high-protein purchases, and 70% increased overall healthy food intake. Concurrently, 41% increased spending on vitamins and supplements, 42% spent more on apparel, and 34% increased fitness expenditure.
This consumerization marks a total transformation in how health therapies are evaluated. Jacqueline Windsor, Strategy& Partner and UK Head of Retail at PwC, emphasizes:
“GLP-1 is the most consumerised medication today. People are shopping for GLP-1s as they would everyday items with a focus on brand, value, efficacy, convenience and trust.
Given c.70% of users are accessing the medication privately, this results in a new kind of healthcare consumer. People undergoing treatment expect their GLP-1 experience to feel less like a pharmacy transaction and more like a modern retail one, with optional wrap-around services.
Inge Cajot, Strategy& Partner and Consumer Markets Leader, adds that generational identity dictates basket composition:
“Generational identity – not the medication itself – is the strongest predictor of how these shoppers behave. GLP-1s may be changing appetite but it’s the generation that’s shaping what goes in shopping baskets.
For younger generations, it’s a wellness story that sits in a wider repertoire of products, apps and routines. For middle generations, it’s a health investment to manage weight, energy, and conditions.
Muscle Preservation, Protein Density, and Companion Nutrition
One of the most critical clinical developments accompanying rapid GLP-1 weight loss is the risk of lean muscle mass depletion and micronutrient deficiencies. Clinical meta-analyses of 20 randomized trials confirm that lean mass represents a significant portion of weight lost on incretin therapies unless counteracted by structured resistance training and high-protein intake.
This biological reality has birthed a rapidly expanding industry: GLP-1 companion nutrition. Data from Innova Market Insights demonstrates that product launches making explicit GLP-1 companion claims have grown at a 124% CAGR.
ADM consumer research reveals that 74% of GLP-1 users report feeling fuller faster, 73% prioritize portion control, and 69% say they value nutrition more now than before starting treatment.
Alicia Humpert, Global Marketing Director for Microbiome at ADM, outlines the formulation requirements for this market:
“Products with ingredients that help minimize common side effects of anti-obesity medications, such as biotics for digestion, alternative hydration solutions, and alternative proteins that support muscle health, can benefit the growing market. Metabolic health and weight maintenance support, along with satiety, are areas where brands can provide solutions for those stopping medication… As GLP-1 usage continues to grow, brands should view these medications as a lasting shift instead of a short-term trend. Users represent a distinct consumer segment influencing the broader weight management sector.”
Evelien Bikker, Marketing Manager for Performance and Active Nutrition at FrieslandCampina Ingredients, details the nutritional gaps created by reduced food volume:
“Studies show that GLP-1 users eat around 20% less, yet calorie distribution — including from protein — often falls short, leaving gaps in essential micronutrients. As a result, the body may lack the nutritional building blocks needed to preserve muscle during rapid weight loss… Evidence shows that when consumers discontinue GLP-1 agonists, weight regain can occur rapidly — often with a higher proportion of fat relative to muscle. This underscores the opportunity for compact, high-protein, and fiber-rich formats that support body composition and metabolic health both during and after GLP-1 usage.”
Maggie McNamara, Vice President of Global Marketing at Saanroo, highlights the strategic shift from weight loss to holistic companion support:
“Over the next three to five years, we anticipate increasing demand for ingredients that help brands create complementary and supportive solutions, rather than products positioned as alternatives to prescription therapy. Nutritional ingredient suppliers will shift focus to support ‘companion products’ that are high in protein, fiber, and fortified with nutrients to help manage side effects of reduced caloric intake, such as muscle loss and digestive issues. Demand for ingredients will move from ‘weight loss’ to supporting the overall health of the GLP-1 user.”
Nutritional research also flags specific hidden deficiencies. Silvia Pisoni, Global Operational Marketing Director at Gnosis by Lesaffre, notes:
“Recent data show that the majority of GLP-1 receptor agonist users fail to meet the recommended intake for vitamin K2… In the US, almost 70% of people have lower vitamin K intake than recommended. This means that many GLP-1 users likely start treatment already with low vitamin K2 status. Based on human clinical research demonstrating the link between vitamin K2 and bone status, low intake can amplify concerns relevant to GLP-1 users, such as preservation of bone density and arterial flexibility.”
Luxury Hospitality and Travel: Re-Engineering Restorative Vitality
For the luxury travel sector, GLP-1 adoption is accelerating a profound shift: affluent travelers increasingly evaluate luxury by how a trip makes them feel and function, rather than how much food and alcohol they can consume.
Data from Forbes Travel Guide shows that GLP-1 users consume 40% fewer total calories, 80% fewer desserts, and 33% less alcohol while increasing expenditure on spa, body contouring, recovery, and aesthetic services.
Leading global properties are re-engineering guest experiences around these physical priorities:
- Sensei Lanai (A Four Seasons Resort) and The Broadmoor in Colorado have redesigned dining room services to offer portion-calibrated, high-protein gastronomy presented with uncompromised aesthetic elegance.
- The Miami Beach EDITION has expanded high-protein menu architecture and non-alcoholic adaptogenic cocktail pairings.
- Four Seasons Hotel Los Angeles at Beverly Hills has introduced a clinical GLP Body Preservation Infusion in partnership with wellness specialists, directly addressing guest concerns regarding hydration, energy, and muscle retention.
- InterContinental Coogee Beach Sydney and Halcyon House have introduced contrast therapy (sauna and ice bath facilities) and floating sound bath treatments focused on sleep optimization and stress reduction.
Alaina Sweeney, General Manager at the St. Regis Washington, D.C., reflects on this operational evolution:
“Luxury hospitality has always been about anticipating what’s next and evolving guest expectations rather than simply responding to them. It’s a core part of service excellence. Our guests expect us to evolve alongside their lifestyles and are looking for hotels that make it easy to sustain the habits and routines that matter to them while away from home. Wellness has become an increasingly important factor in travel decisions and continues to redefine luxury travel. It’s our responsibility to deliver that experience with elegance and personalization.”
The Beverage Reset and Retail Transformation
The alcoholic beverage and fashion retail industries provide a clear window into how commercial categories shift when purchasing drivers move from volume to intentionality.
In the alcohol sector, EY-Parthenon research reveals that 70% of GLP-1 users report a decreased desire for alcohol, resulting in a 41% overall reduction in alcoholic beverage consumption. In the UK, PwC data indicates that alcohol abstainers among GLP-1 users rise from 16% pre-treatment to 25% during treatment, while heavy drinking (4+ times per week) more than halves from 18% to 8%.
Concurrently, US sales of low- and no-alcohol beverages are expanding at a 13.6% CAGR, compared to just 2.1% CAGR for traditional alcohol.
Sean Harapko, EY Americas Consumer Products Growth and Beverage Sector Leader, describes this retail aisle transformation:
“Step into any store in 2026 and the alcohol aisle tells a new story. Bulk purchases are less common. Premium single serves and lighter options are now taking center stage. Today’s drinkers are not simply cutting back; they are making more intentional choices. GLP-1 medications have accelerated this change, turning gradual trends into lasting habits. In response, beverage companies are rethinking how they create value, focusing less on frequency and more on the quality of each drinking occasion.”
In commercial retail and beauty:
- Apparel Expansion: EY research shows 67% of GLP-1 users report an increased motivation to refresh their wardrobe, with 57% spending more on clothing. PwC UK data confirms that 40% of users increase clothing spend, with activewear and occasion wear benefiting most.
- Functional Beauty: 53% of GLP-1 users report increased focus on skincare and grooming, while 39% report that shopping for beauty products has become noticeably more enjoyable as they address skin elasticity and volume loss.
Lisa Nijssen-Smith, EY Regional Consumer Products & Retail Leader for Oceania, summarizes these multi-sector impacts:
“GLP-1 users surveyed said they were dining out 44 per cent less, which means hospitality venues may need to think differently about value, experience and the role food plays in a night out. The survey also points to a clear shift in alcohol demand, with 70 per cent of GLP-1 users saying they were less likely to want alcohol and reported alcoholic beverage consumption falling by 41 per cent… More than two-thirds of GLP-1 users surveyed (67 per cent) said their motivation to refresh their wardrobe had increased since starting treatment and 57 per cent had increased their spending on clothes… Supermarkets and food manufacturers are likely to face some of the most direct impacts as consumers become more selective about what they eat and buy. They are buying more fresh, protein-rich and health-oriented foods, and less alcohol, snacks and processed products.”
Emma Burton, Director at PwC Strategy& UK, frames the corporate imperative:
“GLP-1 started as a medication, but it is becoming a catalyst for business transformation. As usage scales, companies will need to respond to dynamic demand patterns – reshaping propositions, mitigating category specific risks and building new partnerships across the consumer health ecosystem.”
Indulging the Trend: How Affluent Readers Can Invest in Themselves
For private wealth owners, business leaders, and sophisticated investors, adopting this cultural shift is not about restriction—it is an exercise in biological optimization and high-performance living. Having solved the mechanics of capital accumulation, affluent individuals are applying the same rigorous, data-driven approach to their physical baselines.
In PwC’s national wellness survey, longevity ranked as the single highest priority (21%), followed by improved sleep (15%) and stress reduction (13%). 82% of respondents actively use wearables, smartwatches, or continuous devices to track health metrics, while 63% utilize AI digital tools for proactive health research before consulting credentialed specialists.
Dr. Nicola Lynch, Health Industry Leader at PwC Australia, notes how digital tools merge with expert human care:
“AI and apps can be powerful pathways to support earlier intervention and prevention, helping patients navigate initial questions and concerns. Many Australians are no longer waiting for a single clinical interaction to start thinking about, or acting on, their health. But in the age of information overload and conflict, the value of credentialed expertise is increasing, and Australians still seek professional advice to make safe decisions.”
To indulge this shift and maximize personal vitality, wealth owners can structure their personal health investments around four core pillars:
- Prioritize Muscle Mass and Bone Density: Pair any metabolic or GLP-1 protocol with coach-led, evidence-based resistance training and high-density companion proteins (whey, casein) to preserve lean body mass and baseline metabolic rate.
- Fortify Against Micronutrient Gaps: Incorporate targeted companion supplements—specifically prebiotic fibers for gut microbiome stability and Vitamin K2 for arterial flexibility and bone density support.
- Integrate Real-Time Health Intelligence: Deploy continuous glucose monitors, smart wearables, and AI-assisted health triage to establish personalized benchmarks for sleep architecture, heart-rate variability (HRV), and systemic recovery.
- Curate Experiential Travel Around Vitality: Select luxury hospitality properties that offer DEXA body diagnostics, bio-available high-protein gastronomy, contrast recovery suites, and restorative sleep environments over legacy high-calorie amenities.