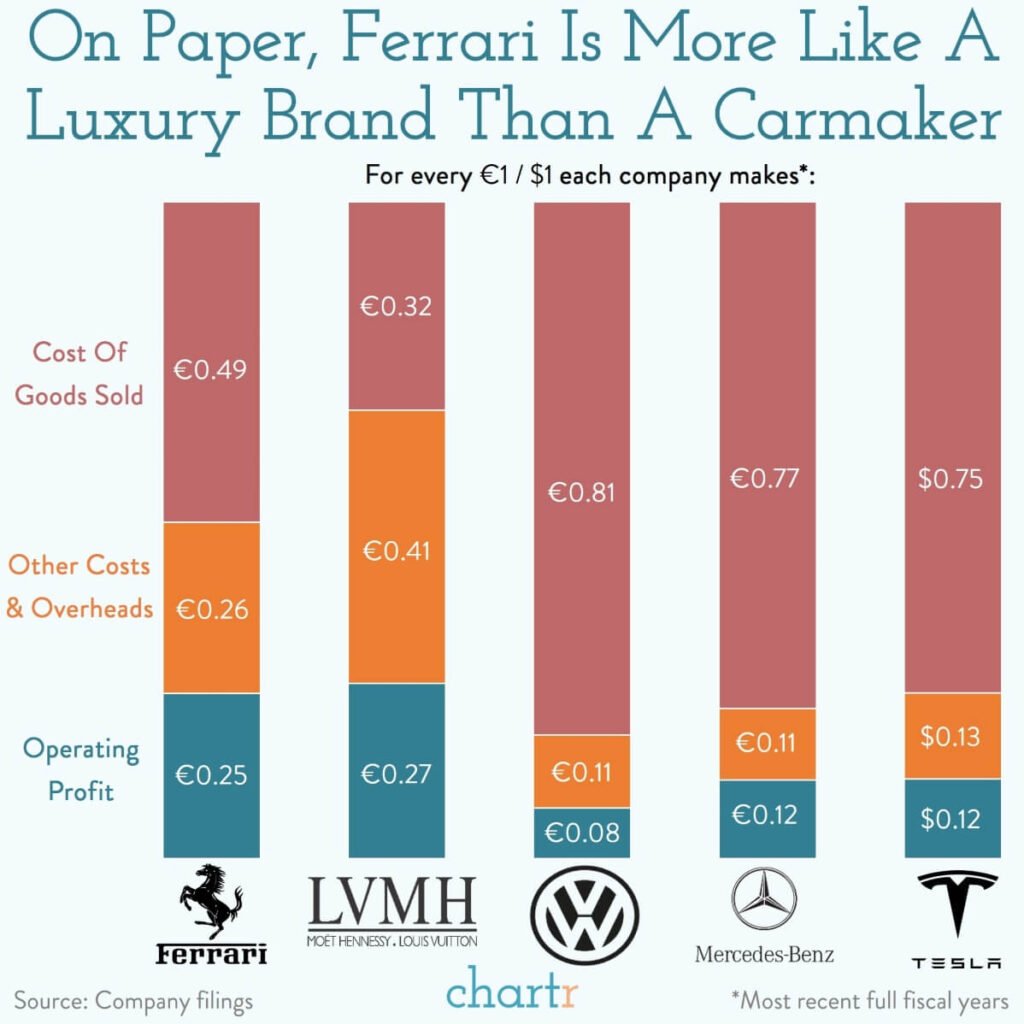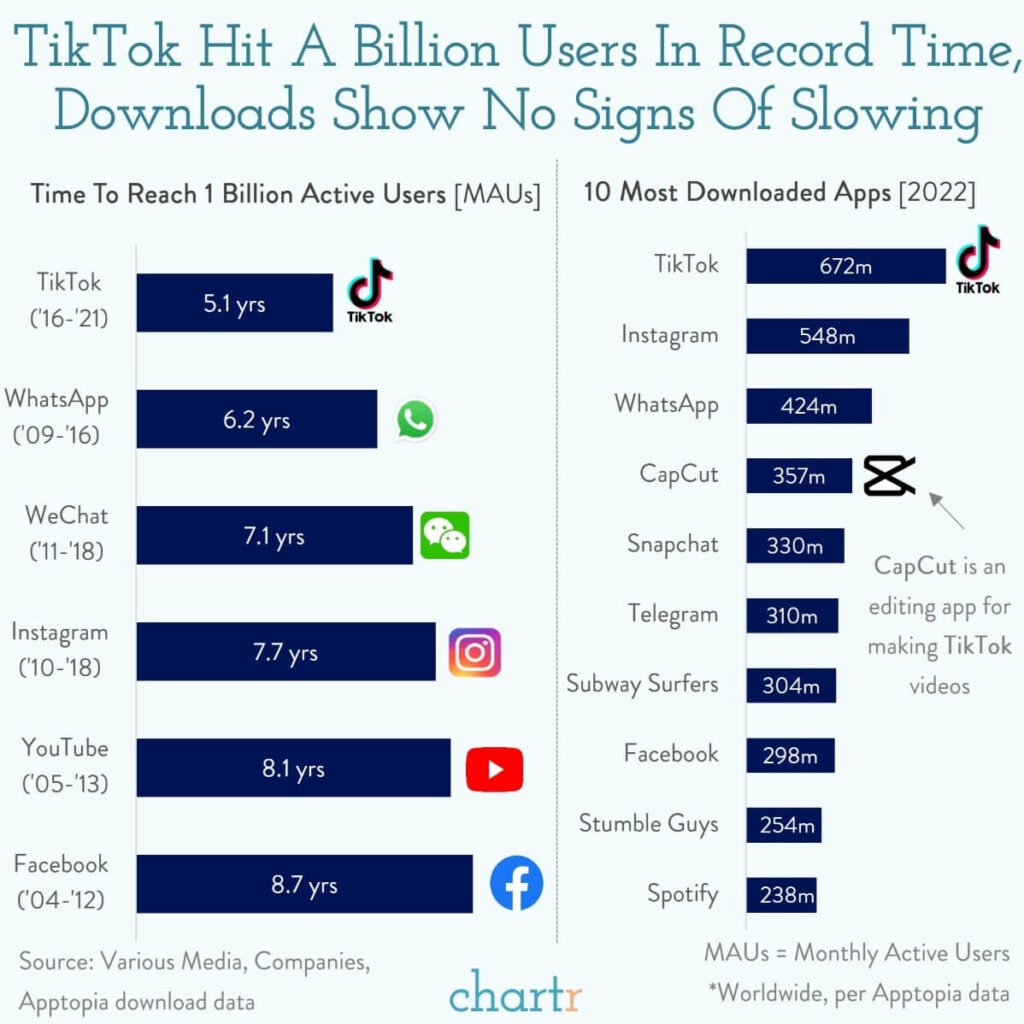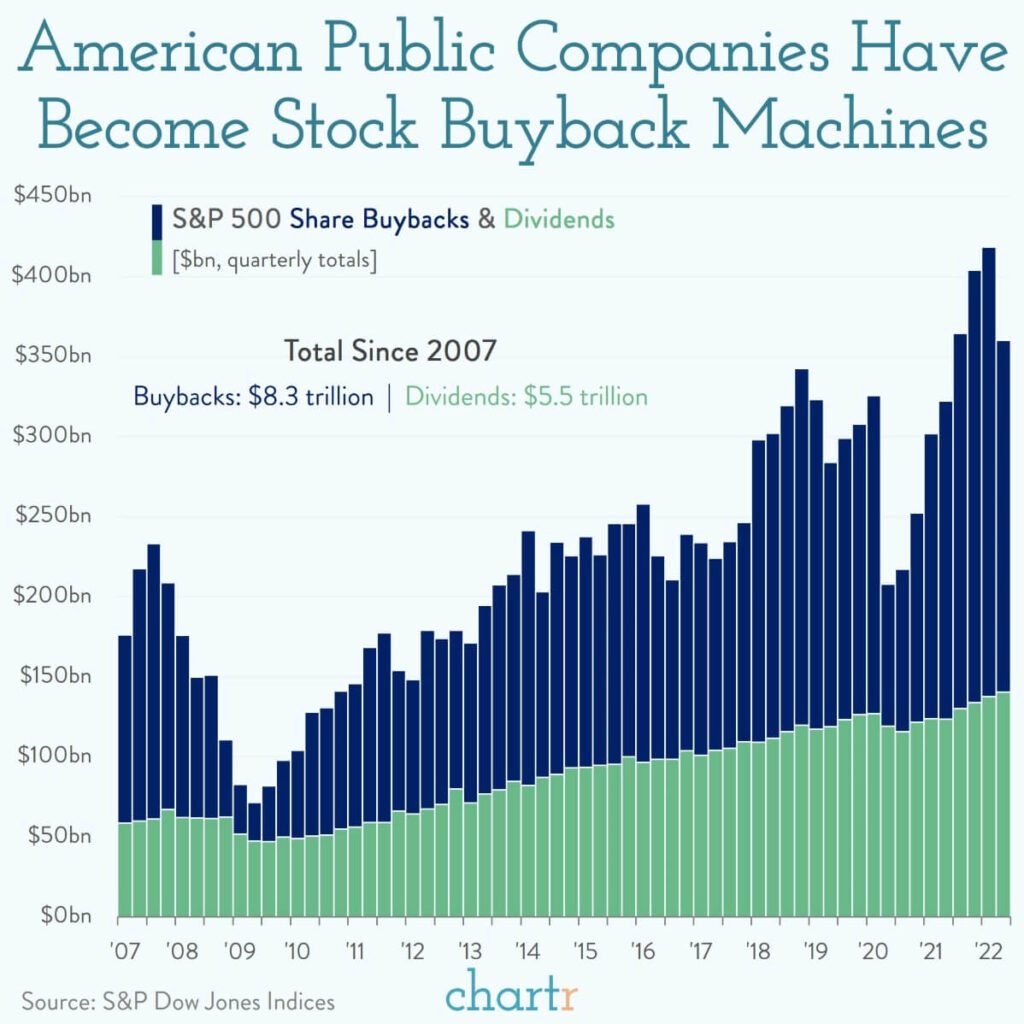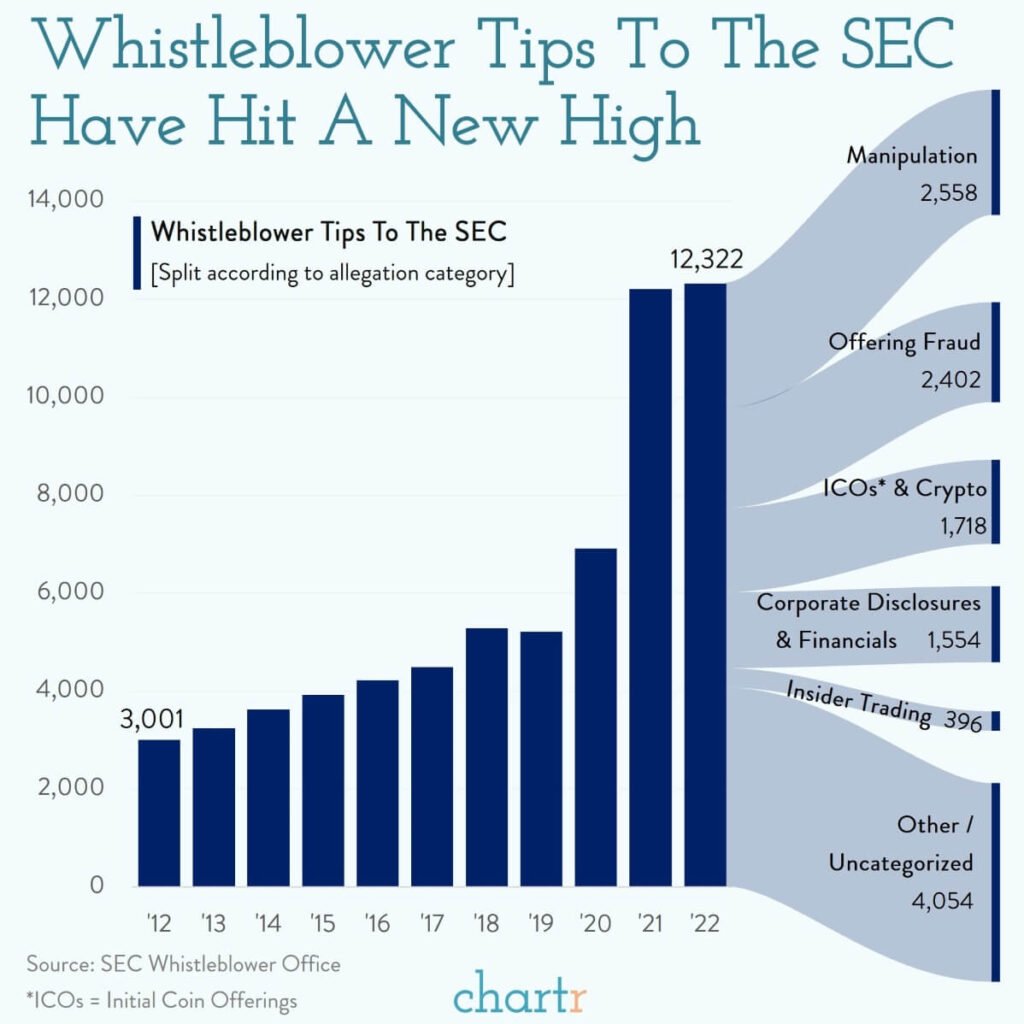
Dispatch №15

Behavioral finance is widely recognized, but most attention is given to investment behavior. Spending money can reveal deep insights into a person’s values, relationships, career choices, and social aspirations. While there is a science to budgeting and finding bargains, there is also an art to spending that varies from person to person and cannot be quantified. Money is considered a revealing indicator of character and values. Unlike investments, spending behavior is highly visible, providing a more comprehensive understanding of a person’s character. The lack of clear-cut rules and the individuality of spending habits make this topic fascinating.

Topics of the week

The Art and Science of Spending Money by Morgan Housel is so good that we think you should read it and re-read it all over again and again.

Former General Electric CEO Jack Welch once nearly died of a heart attack. Years later he was asked what went through his mind while he was being rushed to the hospital in what could have been his last moments alive.

“Damn it, I didn’t spend enough money,” was Welch’s response.

The interviewer, Stuart Varney, was puzzled, and asked why in the world that would go through his mind.

“We all are products of our background,” Welch said. “I didn’t have two nickels to rub together [when I was young], so I’m relatively cheap. I always bought cheap wine.”

After the heart attack Welch said he “swore to God I’d never buy a bottle of wine for less than a hundred dollars. That was absolutely one of the takeaways from that experience.”

“Is that it?” Varney asks, stunned.

“That’s about it,” says Welch.

Money is so complicated. There’s a human element that can defy logic – it’s personal, it’s messy, it’s emotional.

Behavioral finance is now well documented. But most of the attention goes to how people invest. Welch’s story shows how much deeper the psychology of money can go. How you spend money can reveal an existential struggle of what you find valuable in life, who you want to spend time with, why you chose your career, and the kind of attention you want from other people.

There is a science to spending money – how to find a bargain, how to make a budget, things like that.

But there’s also an art to spending. A part that can’t be quantified and varies person to person.

Money is “the greatest show on earth” because of its ability to reveal things about people’s character and values. How people invest their money tends to be hidden from view. But how they spend is far more visible, so what it shows about who you are can be even more insightful.

Everyone’s different, which is part of what makes this topic fascinating. There are no black-and-white rules.

But here are a few things about the art of spending money.

1. Your family background and past experiences heavily influences your spending preferences.

I love this Washington Post headline from June, 1927 – the Roaring ‘20s, the last hurrah before the Great Depression:
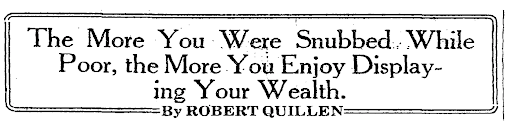
This is timeless, and explains so much.

After Covid lockdowns there was the concept of “revenge spending” – a furious blast of conspicuous consumption, letting out everything that had been pent up and held back in 2020.

Revenge spending happens at a broad level, too. The most stunning examples I’ve seen of this are wealthy adults who grew up poor – and were heckled, bullied, and teased for being poor as kids. Their revenge spending mentality can become permanent.

If you dig into it, I think you’ll see that a disproportionate share of those with the biggest homes, the fastest cars, and the shiniest jewelry, grew up “snubbed” in some way. Part of their current spending isn’t about getting value out of flashy material goods; it’s about healing a social wound inflicted when they were younger.

Even when “wound” is the wrong word, the desire to show the world that you’ve made it increases if you grew up snubbed out of what you wanted. To someone who grew up in an old-money affluent family, a Lamborghini might be a symbol of gaudy egotism; to those who grew up with nothing, the car might serve as the ultimate symbol that you’ve made it.

A lot of spending is done to fulfill a deep-seated psychological need.

2. Entrapped by spending: Rather than using money to build a life, your life is built around money.

George Vanderbilt spent six years building the 135,000-square-foot Biltmore house – with 40 master bedrooms and a full-time staff of nearly 400 – but allegedly spent little time there because it was “utterly unaddressed to any possible arrangement of life.” The house nevertheless cost so much to maintain it nearly ruined Vanderbilt. Ninety percent of the land was sold off to pay tax debts, and the house was turned into a tourist attraction.

In 1875 an op-ed said socialites “devote themselves to pleasure regardless of expense.” A Vanderbilt heir responded that actually they “devote themselves to expense regardless of pleasure.”

The Vanderbilt’s are obviously extreme, but that is a common trait among more ordinary people.

The devotion to expense regardless of pleasure.

Part of this is the belief that spending money will make you happier. When it doesn’t – either because it never will or because you haven’t discovered purchases that bring joy – your reaction is that you must not be spending enough, so you double down, again and again.

I’ve often wondered how many personal bankruptcies and financial troubles were caused by spending that brought no joy to begin with. It must be enormous. And it’s a double loss: not only are you in trouble, but you didn’t even have fun getting there.

I have an old friend who buried himself in credit card debt to go skiing in Europe and loved every second of it. I can wrap my head around that decision, even if I wouldn’t recommend it. He’s in control of his finances.

But what about those whose spending is driven by the belief that money is to be spent, regardless of what pleasure it brings? Money has them by the neck; they are held in captivity by its influence.

3. Frugality inertia: a lifetime of good savings habits can’t be transitioned to a spending phase.

I think what many people really want from money is the ability to stop thinking about money. To have enough money that they can stop thinking about it and focus on other stuff.

But that ultimate goal can break down when your relationship with money becomes an ingrained part of your personality. You struggle to break away from focusing on money because the focus itself is a big part of who you are.

If you develop an early system of savings and living well below your means – congratulations, you’ve won. But if you can never break away from that system, and insist on a heavy savings regimen well into your retirement years … what is that? Is it still winning?

A lot of financial planners I’ve talked to say one of their biggest challenges is getting clients to spend money in retirement. Even an appropriate, conservative amount of money. Frugality and savings become such a big part of some people’s identity that they can’t ever switch gears.

I think for some people that’s actually fine. Watching money compound gives them more pleasure than they would get spending it.

But those whose ultimate goal is to stop thinking about money are stuck. Refusing to recognize that you’ve met your goal can be as bad as never meeting the goal to begin with.

4. An emotional attachment to large purchases, particularly a house.

My wife and I pride ourselves on making unemotional financial decisions. But a few years ago we were in the market for our first house. We found one online that we liked, and as we headed out for a tour we promised ourselves we wouldn’t do anything rash – this was just gathering information.

Then we pulled into the driveway and my wife gasped, “I love it!” I did too. We had an infant son – our first – and there was a kids’ tree swing in the front yard. Perfect.

And that was it. Emotion was involved and there was nothing we could do about it.

We have zero regrets – the house really was great. But no one should pretend that you can make life-changing decisions that will massively impact you and your family and treat it like a math problem.

Jason Zweig of The Wall Street Journal once wrote about his mom selling her longtime home:

I have no emotional attachment to the house; I never liked it physically,” Mom told us. “But everything important that ever happened in our life as a family is here, and I can’t just leave all that behind.”

If I said, “How much are the memories with your kids worth?” you’d say it’s impossible to attach a dollar figure. But if I said, “How much is the home where you formed memories with your kids worth?” or “How much does staying in your local town impact your salary?” you could probably spit out a dollar figure with ease.

Understanding the difference between those two helps explain a lot of spending decisions.

5. The joy of spending can diminish as income rises because there’s less struggle, sacrifice, and sweat represented in purchases.

In his 1903 book The Quest for the Simple Life, William Dawson writes:

The thing that is least perceived about wealth is that all pleasure in money ends at the point where economy becomes unnecessary. The man who can buy anything he covets, without any consultation with his banker, values nothing that he buys.

Consider how you felt when you got your first paycheck from your first job. If you celebrated with as little as a milkshake from Denny’s you probably had a joyous feeling of, “I did this. I bought this. With my own money.” Going from not being able to buy anything to able to buy something is an amazing feeling. The gap between struggle and reward is a big part of what makes people happy.

Contrast that with later in your career, when (hopefully) savings have been built and paychecks have grown. It’s not that spending won’t make you happy – but it won’t be as thrilling and adrenaline-inducing as it was when there was more struggle behind each dollar.

I know a guy with a private chef. He’s served 5-star meals three times a day, an arrangement he’s enjoyed for years. It’s amazing; I’d lie if I said I wasn’t jealous. But I also wonder if the joy diminishes over time. He doesn’t have to struggle to get these meals – there’s no anticipation, no looking forward to a restaurant reservation, no contrasting gap between a “normal” meal and his daily delicacy.

There’s a saying that the best meal you’ll ever taste is a glass of water when you’re thirsty. All forms of spending have that equivalent.

Let me end with a wise quote from, of all people, Richard Nixon:

The unhappiest people of the world are those in the international watering places like the South Coast of France, and Newport, and Palm Springs, and Palm Beach. Going to parties every night. Playing golf every afternoon. Drinking too much. Talking too much. Thinking too little. Retired. No purpose.

So while there are those that would disagree with this and say “Gee, if I could just be a millionaire! That would be the most wonderful thing.” If I could just not have to work every day, if I could just be out fishing or hunting or playing golf or traveling, that would be the most wonderful life in the world – they don’t know life. Because what makes life mean something is purpose. A goal. The battle. The struggle – even if you don’t win it.

6. Asking $3 questions when $30,000 questions are all that matter.

There’s a saying: Save a little bit of money each month, and at the end of the year you’ll be surprised at how little you still have.

Author Ramit Sethi says too many people ask $3 questions (can I afford this latte?) when all that matters to financial success are $30,000 questions (what college should I go to?)

Historian Cyril Parkinson coined a thing called Parkinson’s Law of Triviality. It states: “The amount of attention a problem gets is the inverse of its importance.”

Parkinson described a fictional finance committee with three tasks: approval of a $10 million nuclear reactor, $400 for an employee bike shed, and $20 for employee refreshments in the break room.

The committee approves the $10 million nuclear reactor immediately, because the number is too big to contextualize, alternatives are too daunting to consider, and no one on the committee is an expert in nuclear power.

The bike shed gets considerably more debate. Committee members argue whether a bike rack would suffice and whether a shed should be wood or aluminum, because they have some experience working with those materials at home.

Employee refreshments take up two-thirds of the debate, because everyone has a strong opinion on what’s the best coffee, the best cookies, the best chips, etc.

Many households operate the same.

7. Social aspiration spending: Trickle-down consumption patterns from one socioeconomic group to the next.

Economist Joseph Stiglitz once wrote: “Trickle-down economics may be a chimera but trickle-down behaviorism is very real.”

There is no such thing as an objective level of wealth. Everything is relative to something else. People look around and say, “What’s that person driving, where are they living, what kind of clothes are they wearing?” Aspirations are calibrated accordingly.

I spoke with Wired magazine founding executive editor Kevin Kelly last week. He brought up an interesting point: If you want to know what lower-income groups will aspire to spend their money on in the future, look at what higher-income groups exclusively do today.

European vacations were once the exclusive playground of the rich. Then they trickled down.

Same with college. It was once reserved for the highest income groups. Then it spread.

Same with investing. In 1929 – the peak of the Roaring ‘20s bubble – five percent of Americans owned stocks, virtually all of them the very wealthy. Today, 58% of households own stocks in some form.

Same with two-car households, lawns, walk-in closets, granite countertops, six-burner stoves, jet travel, and even the entire concept of retirement.

Part of the reason these products spread to the masses is that they got cheaper. But the reason they got cheaper is because there was so much demand from the masses – hungered by their aspirations – that pushed companies to innovate new ways of mass production.

People like to mimic others, especially those who appear to be living better lives. Always been like that, always will be.

8. An underappreciation of the long-term cost of purchases, with too much emphasis on the initial price.

It’s common to find someone who bought their home in, say, 1974, for something like $60,000. Today it’s worth perhaps $350,000. The owners no doubt feel they have made the investment of their lives.

But those numbers above equate to an average annual return of 3.75%. Property taxes tend to average roughly 1%, so that brings our real return to 2.75% per year. Maintenance and repairs vary greatly, but spending 1% – 3% of your home’s value per year on upkeep should be expected.

Where does that leave our long-term returns? Ah, quite dim.

Price is easy to calculate. It’s just whatever you paid initially and sold for eventually.

Cost is harder to figure out. They tend to be a slow drip over time, which are easy to ignore but add up quickly.

Same for cars, boats, and hobbies. You can even say the cost of smoking cigarettes is the price of a pack plus the long-term cost of medical care associated with the habit. One is easy to calculate, the other is very difficult.

9. No one is impressed with your possessions as much as you are.

When you see someone driving a nice car, you rarely think, “Wow, the guy driving that car is cool.” Instead, you think, “Wow, if I had that car people would think I’m cool.” Subconsciously or not, this is how people think.

There is a paradox here: people tend to want wealth to signal to others that they should be liked and admired. But in reality those other people often bypass admiring you, not because they don’t think wealth is admirable, but because they use your wealth as a benchmark for their own desire to be liked and admired.

I wrote a letter to my son the day he was born. It says, in part:

You might think you want an expensive car, a fancy watch, and a huge house. But I’m telling you, you don’t. What you want is respect and admiration from other people, and you think having expensive stuff will bring it. It almost never does – especially from the people you want to respect and admire you.

Now, I like nice homes and nice cars as much as anyone. The point here is not to shoo you away from nice things.

It’s just a recognition that no one is as impressed with your stuff as much as you are. Or even that no one is thinking about you as much as you are. They’re busy thinking about themselves!

People generally aspire to be respected and admired by others, and using money to buy fancy things may bring less of it than you imagine. If respect and admiration are your goal, be careful how you seek it. Humility, kindness, and empathy will bring you more respect than horsepower ever will.

10. Not knowing what kind of spending will make you happy because you haven’t tried enough new and strange forms of spending.

Evolution is the most powerful force in the world, capable of transforming single-cell organisms into modern humans.

But evolution has no idea what it’s doing. There’s no guide, no manual, no rulebook. It’s not even necessarily good at selecting traits that work.

Its power is that it “tries” trillions upon trillions of different mutations and is ruthless about killing off the ones that don’t work. What’s left – the winners – stick around.

There’s a theory in evolutionary biology called Fisher’s Fundamental Theorem of Natural Selection. It’s the idea that variance equals strength, because the more diverse a population is the more chances it has to come up with new traits that can be selected for. No one can know what traits will be useful; that’s not how evolution works. But if you create a lot of traits, the useful one – whatever it is – will be in there somewhere.

There’s an important analogy here about spending money.

A lot of people have no idea what kind of spending will make them happy. What should you buy? Where should you travel? How much should you save? There is no single answer to these questions because everyone’s different. People default to what society tells them – whatever is most expensive will bring the most joy.

But that’s not how it works. You have to try spending money on tons of different oddball things before you find what works for you. For some people it’s travel; others can’t stand being away from home. For others it’s nice restaurants; others don’t get the hype and prefer cheap pizza. I know people who think spending money on first-class plane tickets is a borderline scam. Others would not dare sit behind row four. To each their own.

The more different kinds of spending you test out, the closer you’ll likely get to a system that works for you. The trials don’t have to be big: a $10 new food here, a $75 treat there, slightly nice shoes, etc.

Here’s Ramit Sethi again: “Frugality, quite simply, is about choosing the things you love enough to spend extravagantly on—and then cutting costs mercilessly on the things you don’t love.”

There is no guide on what will make you happy – you have to try a million different things and figure out what fits your personality.

11. The social signaling aspect of money, on both things you buy for yourself and charity given to others.

There’s a saying that if you get public recognition for donating money, it’s not charity – it’s philanthropy. And if you demand recognition, it’s not even charity – it’s a business deal. There’s a clear social benefit to you, the giver, in addition to the recipient. I don’t mean that in a negative way: Good donations to worthy causes would plunge if donors didn’t get recognition.

Most forms of spending have two purposes: To bring some sort of utility to the owner, and to signal something to other people.

Homes, cars, clothes, jewelry, obviously fit into that category. But even travel does as well – how many vacation destinations are picked at least in part by what you think will make a good Instagram picture, or just that it sounds cool. (My guess is most Bali vacations fall into that category).

Psychologist Jonathan Haidt says people don’t communicate on social media; they perform for one another. Spending money is like that, too.

It’s not always a bad thing. If you’ve merely thought about what clothes you’ll look best in before you leave in the morning, you’ve engaged in signaling. And it’s not always about looking the best: intentionally dressing casually to a formal meeting sends a powerful message about who holds the power. Before being caught as a sham, Sam Bankman-Fried said he intentionally didn’t wear pants to create a mystique.

The thing to recognize is that spending money “on yourself” is often done with the intent of influencing what other people think.

That should spark three questions: Whose opinion are you trying to influence, why, and are those people even paying attention?

12. The social hierarchy of spending, positioning you against your peers.

An old joke is about two hikers who come across a grizzly bear in the woods. One starts to run, and the other yells, “Are you crazy, you can’t outrun a bear!” The runner replies: “I don’t have to be faster than the bear. I only have to be faster than you.”

All success is simply relative to someone else – usually those around you.

That’s important for spending money, because for so many people the question of whether you’re buying nice things is actually, “are your things nicer than other peoples’ things?” The question of whether your home is big enough is actually, “is your home bigger than your neighbor’s?”

Not only is the urge to one-up your peers, but you may feel the need to continually surpass your own spending. Is this year’s vacation more expensive than last year’s? Is the next car fancier than the old one?

Money to some people is less of an asset and more of a social liability, indebting them to a status-chasing life that can leave them miserable.

It’s a dangerous trap if you don’t recognize the game and how it’s played. Montesquieu wrote 275 years ago, “If you only wished to be happy, this could be easily accomplished; but we wish to be happier than other people, and this is always difficult, for we believe others to be happier than they are.”

13. Spending can be a representation of how hard you’ve worked and how much stress went into earning your paycheck.

Someone who works 100 hours a week and hates their job may have an urge to spend frivolously in an attempt to compensate for the misery of how their paycheck was earned.

Never have I seen money burn a hole in someone’s pocket faster than an investment banker receiving their annual bonus. After 12 months of Excel modeling until 3am, you have an urge to prove to yourself that it was worth it, offsetting what you sacrificed. It’s like someone held underwater for a minute – they do not take a calm breath when they surface; they gasp.

The opposite can hold true. I can only back this up with anecdotal experiences, but those most capable of delayed gratification are often those who enjoy their work. The pay might be good, but the urge to compensate for your hard work with heavy spending isn’t there.

Spending money to make you happy is hard if you’re already happy.

Inforgraphics
Links to consider

Books that caught our attention this week
The Business Reinvention of Japan: How to Make Sense of the New Japan and Why It Matters

by Ulrike Schaede

After two decades of reinvention, Japanese companies are re-emerging as major players in the new digital economy. They have responded to the rise of China and new global competition by moving upstream into critical deep-tech inputs and advanced materials and components. This new “aggregate niche strategy” has made Japan the technology anchor for many global supply chains. Although the end products do not carry a “Japan Inside” label, Japan plays a pivotal role in our everyday lives across many critical industries. This book is an in-depth exploration of current Japanese business strategies that make Japan the world’s third-largest economy and an economic leader in Asia. To accomplish their reinvention, Japan’s largest companies are building new processes of breakthrough innovation. Central to this book is how they are addressing the necessary changes in organizational design, internal management processes, employment, and corporate governance. Because Japan values social stability and economic equality, this reinvention is happening slowly and methodically, and has gone largely unnoticed by Western observers. Yet, Japan’s more balanced model of “caring capitalism” is both competitive and transformative, and more socially responsible than the unbridled growth approach of the United States.
Amazon


The Economic Rise of East Asia: Development Paths of Japan, South Korea, and China

by Linda Glawe, Helmut Wagner

In light of the growing global economic importance of East Asia, this book analyzes and compares the extraordinary development paths and strategies of Japan, South Korea, and China. It examines both the factors that enabled these countries’ prolonged periods of high-speed economic growth, and the reasons for their subsequent “cool-downs.” In addition, the book illustrates how their development strategies served as role models for one another, and what current and future developing countries can learn from the East Asian success stories. This book will appeal to scholars and students of economics and development studies with an interest in the East Asian development model.
Amazon


The Aftermath: The Last Days of the Baby Boom and the Future of Power in America

by Philip Bump

Philip Bump, a reporter as adept with a graph as with a paragraph, is popular for his ability to distill vast amounts of data into accessible stories. THE AFTERMATH is a sweeping assessment of how the baby boom created modern America, and where power, wealth, and politics will shift as the boom ends. How much longer than we’d expected will Boomers control wealth? Will millennials get shortchanged for jobs and capital as Gen Z rises? What kind of pressure will Boomers exert on the health care system? How do generations and parties overlap? When will regional identity trump age or ethnic or racial identity? Who will the future GOP voter be, and how does that affect Democratic strategies? What does the Census get right, and terribly wrong? Writing with a light hand and deft humor, Bump helps us navigate the flood of data in which our sense of the country now drowns. He fits numbers into a narrative about who we are (including what “we” really means), how we vote, where we live, what we buy—and what predictions we can make with any confidence. We know what will happen eventually to the baby boomers. What we don’t know is how the boomer legacies might reshape the country one final time.

Amazon

Video of the week

Peter Thiel: Technology Entrepreneur and Venture Capitalist | Address and Q&A | Oxford Union

**

Why Technology Still Matters with Marc Andreessen

**

The ASML of DNA Sequencing

**

Hershey: The Real Life Willy Wonka
[/arm_restrict_content]

Dispatch №14

Over the past decade, institutional investors have increasingly allocated their capital to private markets, more than any other asset class. This has led to a significant growth in assets under management for private capital fund managers, reaching over $10 trillion, an increase of 200% from 2011 to 2021. However, with economic challenges arising, the future of the private capital market is uncertain. The private market is currently facing increased scrutiny, due to factors such as potential new regulations, high valuations, market conditions, and macroeconomic challenges. The future of the private capital industry will be shaped by investor demand and the performance of current funds. A significant amount of attention is currently directed towards the private asset management industry, which has the potential to be worth trillions of dollars.

Private Capital and growth in AUM

Globally, institutional investors have put more of their incremental capital to work in private markets over the last decade than any other asset class. Coupled with increasing allocation targets and strong performance, private capital fund managers have accumulated well over $10 trillion in assets under management (AUM), a growth of more than 200% from 2011 to 2021. However, with macroeconomic headwinds surfacing, the question is, what does the future hold for private capital? 

Private markets have never been under as much scrutiny as they are now. Between the potential for new regulatory red tape, questionably high valuation marks, the denominator effect, and macroeconomic headwinds, the next chapter for private capital will shape its future. A multi-trilliondollar spotlight is on the private asset management business, and the growth of the industry will depend on continued investor appetite in addition to the performance of funds active today. 

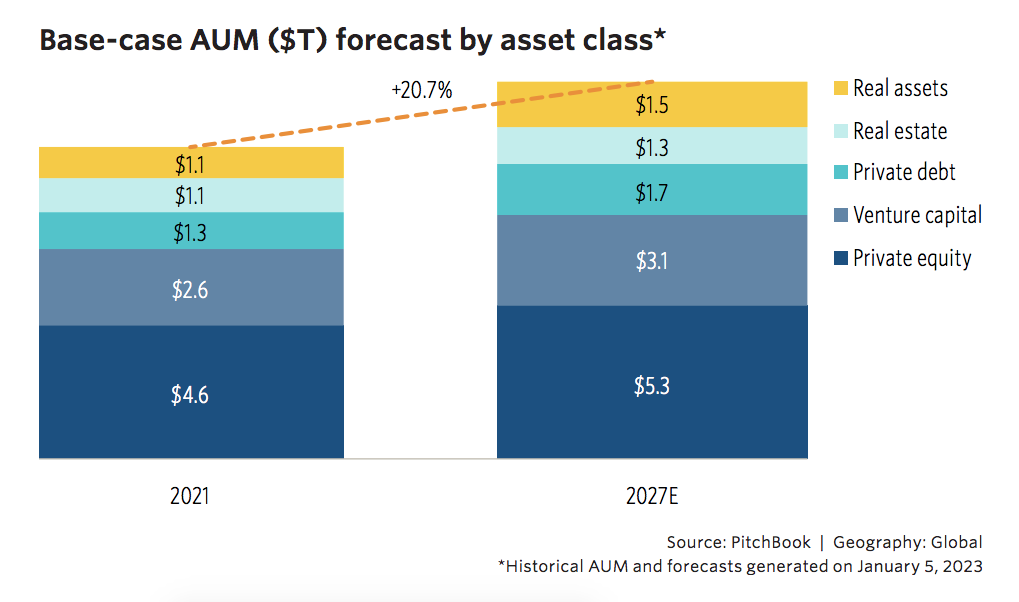
PitchBook’s analysts project private capital global AUM to grow sizably but at a more muted pace compared with the prior five years. Analytical models suggest a cumulative growth of 20.7% to $13.0 trillion in total AUM by 2027.

However, the estimate varies widely. The potential for an economic downturn and a new inflationary regime could have long-term implications for private markets. Asset growth from fund performance and future fundraising are the two most important variables in our estimates, and they are also the most sensitive to the macro climate. To capture the uncertainty of future economic conditions, we have created three scenarios: a good case featuring a return to economic expansion, a base case involving a moderate downturn followed by recovery, and a bad case leading to more pronounced NAV markdowns across private fund holdings. 

Different asset classes within the private capital umbrella will also be impacted in different ways.

Private equity 

In many ways, the era following the global financial crisis (GFC) can be seen as the golden age for PE fund managers. Steady economic growth and persistently low benchmark interest rates acted as rising tides for flagship buyout funds across most geographies. Low interest rates juiced up returns by lowering financing costs and increasing discounted valuations, especially for the increasingly hot technology sector. As a result of strong performance and increasing LP allocations, the asset class reached a total AUM of $4.6 trillion by the end of 2021. However, Pitch Book expects growth in PE assets to slow over the next five years. With the exit window narrowing from macro headwinds, Pitch Book models weaker distributions to LPs, which will reduce the amount of money recycled into future commitments. Fund NAVs will need to be reevaluated as well, even in the rosiest of scenarios. Pitch Book forecasts indicate a base case of $5.3 trillion in AUM by 2027, representing a cumulative growth of 15.8% from 2021. This is a marked slowdown from the last decade, when AUM more than doubled.

Venture capital 

No other asset class saw the benefits of cheap capital and sectoral tailwinds over the last decade quite like VC. The maturation of the industry since the GFC saw AUM reach $2.6 trillion by the end of 2021. As a result of fundraising records and valuation markups, the $2.0 trillion currently invested in fund NAV is at risk of further cuts as 2022 figures continue to come in. An expected slowdown in consumer spending and overall business activity will squeeze top-line numbers for startups, increasing the need for cost-cutting to extend runways to profitability or exit. Additionally, the startups that are nearing the end of their available cash and are yet to have a clear path to profitability may find it difficult to raise any capital in the current environment. While Pitch Book expects the asset class to recover, a healthy reset will be painful for some VC fund managers caught up in the euphoria of 2021’s growth-at-all-costs mindset. Pitch Book forecasts AUM to decline through the end of 2023 before rebounding to $3.1 trillion by 2027, representing a cumulative growth of 18.1%. 

Private debt 

Current investor appetite for private debt has been supported by the asset class’s solid performance amid global central bank rate hikes and attractive yields. Floating rate credit was one of the few bright spots for returns in 2022, in contrast with fixed-rate credit, which was battered by its duration exposure. Lending opportunities have surfaced as banks have pulled back from the leveraged loan market, and private credit has been swift to fill the gap. Fueled by growing interest from LPs, private debt fund AUM reached $1.3 trillion by the end of 2021, a sizable 202.7% growth over the past 10 years. Defaults and distress ratios have remained low through early 2023, indicating resilience for the asset class in the face of economic headwinds and likely encouraging new LP commitments as a result. However, with a looming economic recession, the increasing cost of debt, and the prevalence of covenant-lite terms over the past several years, the risk of missed payments is worth watching closely. Pitch Book forecasts that new inflows and relative insulation from an economic downturn will help AUM grow to $1.7 trillion by 2027, reflecting an annualized growth rate of 4.4%.

Real estate

Since the popping of the real estate bubble during the GFC, global fundraising for finite-life, closed-end funds has remained relatively muted. Fundraising for the asset class reached $152.3 billion in 2007, topping this number only in 2019 and hovering near it through 2020 and 2021.7 Cap rates at historically low levels will not be sustainable if risk-free government bonds trade near similar levels. The expectations for high rent growth in industrial and residential sectors that have justified low cap rates will likely need to be pulled back, resulting in a reset in valuations. Likewise, a retraction in the business cycle would lead to headcount reduction, further culling demand for commercial office space. Despite these risks, the present economic headwinds are not born out of the real estate sector. Therefore, markdowns are likely but are probably lighter compared with those during the GFC, and a rebound when the cycle turns is likely to buoy real estate investment demand should inflation persist above 2% targets. Within closed-end vehicles, global AUM for the asset class surpassed $1.1 trillion in 2021, with private NAVs showing little signs of devaluations like those seen in public REIT securities. Recently, cracks have begun to show, with private REIT redemption requests hitting mandated limits. While fund returns in 2022 so far have not moved south, Pitch Book expects the sell-off in public REITs and negative sentiment for the real estate sector to hit fund returns in 2023. As we look to this year and beyond, upcoming reappraisals of fund properties will likely hamper total assets in the short term before a return to growth brings AUM to $1.3 trillion in 2027 in Pitch Book base-case forecast.

Real assets 

Real assets funds have seen healthy but shifting investor appetite recently, with oil & gas funds suffering a pullback by institutional investors conscious of environmental, social & governance criteria. Total global fundraising for real assets funds reached more than $136.2 billion in 2021, and the first two quarters of 2022 saw strong new commitments to these funds. While this trend slowed in the latter half of 2022, real assets fundraising for the year is on track to surpass the average over the past decade, driven by substantial commitments from national governments and institutions to infrastructure, an attractive subcategory of real assets funds that provide more durable yield-generating returns in times of inflationary pressure. This trend is likely to persist as Western governments refocus efforts on building resiliency with their energy sources and telecommunications projects have a long road ahead in the postdigital age. Global AUM for the asset class topped $1.1 trillion in 2021, on par with private debt and real estate AUM. Pitch Book expects real assets AUM to reach $1.5 trillion by 2027, representing a cumulative growth of 37.1% from 2021.

Attitudes survey by Knight Frank:
How are UHNWI creating wealth in 2023?

1

Global movement has been tempered by the pandemic, but the desire to be mobile is proving resilient. Some 13% of UHNWIs are planning to apply for a second passport or new citizenship, down from the 15% recorded in last year’s report.

2

Globally, a third of total wealth is allocated to UHNWI’s primary and secondary homes. More than a quarter is held outside their country of residence, on average. UHNWIs in the Middle East (41%) have the highest global footprint.

3

The average UHNWI owns 4.2 homes globally. UHNWIs in Asia have the greatest appetite, owning an average five homes each. This demonstrates the unwavering global appeal of residential property

4

Higher interest rates will temper demand for residential property in 2023. Some 15% of UHNWIs are looking to purchase a residential property this year, down from 21% in the previous year’s survey. Appetite is highest amongst Middle Eastern UHNWIs

5

The US, UK and Spain are the top three locations for purchasing homes. Australia and France round out the top five.

6

UHNWIs are increasingly diverse, both by geography and asset class. More than a fifth of our respondents’ investable wealth is directly invested in commercial property and a similar proportion is held overseas.

7

Real estate was identified as a top opportunity, both for direct and indirect investment. One in five UHNWIs are planning to invest directly in 2023, with 13% looking for indirect opportunities. This is broadly in line with the 20% of last year’s survey, indicating the attraction of property as a haven during economic uncertainty.

8

Healthcare, logistics/industrial and offices are the top target sectors for UHNWIs in 2023. The private rented sector (PRS) and hotels/leisure complete the top five. Around a third of respondents are interested in each of the top five sectors in 2023.

9

Energy source (57%), opportunity for refurbishments (33%) and materials used/the embodied carbon footprint (30%) are increasingly being looked at by UHNWIS when purchasing investment property.

10

Art is set to remain the most sought-after investment of passion in 2023 with 59% of UHNWIs likely to make a purchase. Watches come in second, with 46% looking to purchase, followed by wine with 39%. In terms of how much they will spend – art is again at the top, followed by classic cars and wine.

Links to consider

Books that caught our attention this week

Up Close and All In: Life Lessons from a Wall Street Warrior

by John Mack

In Up Close and All In, Mack traces his personal journey from a one-stoplight North Carolina mill town to a fortieth-floor corner office on Wall Street—and shares the life lessons he learned along the way. He developed a titanium-strength stomach for risk, stress, and competition while landing accounts early in his career, as investment banks fought like wolfpacks to take advantage of new deregulation, fielding business raids, booms, and busts. As he rose through the ranks, he never forgot where he came from, relying on his instincts, doing what was right, and listening to his people on the front lines. This culture of trust and collaboration helped Morgan Stanley anticipate future trends before other firms, adapt quickly, and achieve record profits. This gripping memoir includes both humbling lows—like when Mack made the difficult decision to leave Morgan Stanley in 2001—and exhilarating highs—such as when he made an eleventh-hour agreement with the Japanese bank Mitsubishi to save the company during the 2008 financial crisis, having refused to give in when top regulators pressured him to sell the firm for $2 per share.

Amazon


Investing Amid Low Expected Returns: Making the Most When Markets Offer the Least

by Antti Ilmanen

Investing Amid Low Expected Returns: Making the Most When Markets Offer the Least provides an evidence-based blueprint for successful investing when decades of market tailwinds are turning into headwinds. For a generation, falling yields and soaring asset prices have boosted realized returns.  However, this past windfall leaves retirement savers and investors now facing the prospect of record-low future expected returns. Emphasizing this pressing challenge, the book highlights the role that timeless investment practices – discipline, humility, and patience – will play in enabling investment success. It then assesses current investor practices and the body of empirical evidence to illuminate the building blocks for improving long-run returns in today’s environment and beyond. It concludes by reviewing how to put them together through effective portfolio construction, risk management, and cost control practices.

Amazon


When the Heavens Went on Sale: The Misfits and Geniuses Racing to Put Space Within Reach

by Ashlee Vance

Through his trademark immersive reporting, Ashlee Vance follows four pioneering companies—Astra, Firefly, Planet Labs, and Rocket Lab—as they build new space systems and attempt to launch rockets and satellites into orbit by the thousands. While the public fixated on the space tourism being driven by the likes of Jeff Bezos and Richard Branson, these new companies arrived with a different set of goals: to make rocket and satellite launches fast and cheap, thereby opening Earth’s lower orbit for business—and setting it up as the next playing field for humankind’s technological evolution, where we can connect, analyze, and monitor everything on Earth. Vance has had a front-row seat and singular access to this peculiar and unprecedented moment in history. When the Heavens Went on Sale travels through private company headquarters, labs, and top-secret launch locations around the world, including California, Texas, Alaska, New Zealand, Ukraine, India, and French Guiana. He chronicles it all in full color: the private jets, communes, gun-toting bodyguards, drugs, espionage investigations, and multimillionaires guzzling booze to dull the pain as their fortunes disappear.

Amazon

Video of the week

The Untold History of Warren Buffett | 2023 Documentary


Who Is REALLY Making Billions From ChatGPT


Everyone Has It All Wrong With OpenAI | Chamath Palihapitiya

https://www.youtube.com/watch?v=yjo1i3_WRiA

TikTok C.E.O. Shou Chew on China, the Algorithm and More


Can China still become the world’s largest economy? | Business Beyond


Fireside Chat: Reid Hoffman, w/ Elad Gil (AI, Big Tech, & Startups)


Preparing for Global Challenges: In Conversation with Bill Gates


Dennis Whyte: Nuclear Fusion and the Future of Energy | Lex Fridman Podcast

Dispatch №13

“My greatest legacy will be to get people to invest in wealth generation. If you are going to buy stocks in the market now, the first thing is to define a focus, a guideline, and be aware that they will only make money in the medium and long term. The other thing is to create criteria. My most important criterion is that of priority. If someone comes to me saying that he wants to sell me a Mercedes, I will say no, because it is not my priority. My priority is to grow my monthly income portfolio. I go on exorcising everything that is not my priority. I don’t do anything on impulse.

And in the market you will only win if you don’t consider yourself a minority shareholder. Consider yourself a small owner, because the minority shareholder can sell the shares, the small owner won’t sell, because the bigger owner won’t sell either”.

Brazilian Warren Buffett

If you don’t see a future in stock investing because you think it is too late or you have too little money to invest, you need to know this story. And if this is your case, don’t feel bad. It is the case for most Brazilians and billions of other people. Stories like the one you are about to read can change your perception once and for all.

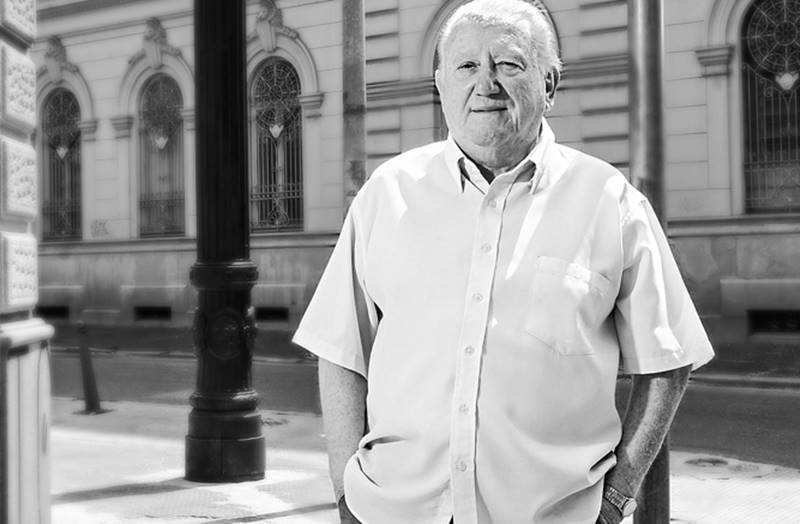
Luiz Barsi (São Paulo, March 10, 1939) is an economist, lawyer and the largest individual investor in Brazil. People call him “Brazilian Warren Buffett”. He is one of the most influential figures in the Brazilian stock market and has accumulated about $735.7 million in assets.

The son of an immigrant, Barsi lost his father of Italian origin when he was only one year old. His mother was one of the “middle” daughters of a family of more than ten siblings who came from Spain as children, after losing everything in a big flood in the city where they lived. She worked as a washerwoman and she and her son Luiz lived in a tenement in Brás districts in the downtown of São Paulo. Life was hard: the boy took his first bath in hot water only when he was over five years old.

To help his mother, he started working at the age of seven, shining shoes, which he did until he was a pre-teen. Barsi also worked as a candy salesman in a movie theater, and later as an apprentice tailor alongside his mother, who had opened a small store. The apprentice took the knowledge with him: to this day, he sews the falling buttons and torn clothes of his family.

The family lacked everything in Barsi’s childhood, except education. Since he could not complete his education, his mother made sure that the boy did not miss any school – and always on a full stomach, to concentrate only on what the teacher was saying. Barsi also inherited from his mother a tireless work ethic – working up to three jobs at a time – and a “hard-line” style of financial management.

His education opened the door to the stock market and at the age of 14 he began working in a brokerage house, where he learned everything that made him what he is today: a millionaire, financially free, successful. In a brokerage firm he would be encouraged to pursue technical training in accounting. There, his interest in studying company balance sheets was born, something he does meticulously until today. After his technical degree, Barsi would graduate in Actuarial Science and complete two other higher education courses: Law, at the Law School in Varginha (MG) and Economics at the School of Economics, Finance and Administration in São Paulo, two courses considered essential for the analysis of balance sheets, companies, and the economic and political scenario that he still does today.

At 16, Barsi had already been working for a long time. He helped support the household and had a pretty hard life for a teenager. However, persistence did not let him get discouraged, and the future millionaire already had his dreams very concrete.

After graduating, Barsi went on to teach classes on balance sheet structure and analysis. But his education would also open the way for a job as an auditor and make him doubt the sustainability of Social Security in Brazil.

Before he turned 30, Barsi began to do what few young people do even today: worry about their retirement. Barsi didn’t want to get rich, but “never to be poor again, not in that miserable condition.

In analyzing the national social security system, Barsi drew two main conclusions: 1) the system was heading for collapse; 2) he depended only on his work to guarantee his retirement.

Barsi also realized that two groups of people didn’t need to worry about retirement: public employees, who would receive a full salary even after they stopped working, and businessmen, who could continue to receive the profits from the companies they created.

Since he had no interest in working for the government, he chose to become a businessman. But, in his own words, instead of owning a small business, he preferred to be a partner in several large businesses. This reasoning would lead him to buy his first shares.

As an auditor, he had a lot of contact with company balance sheets. In 1970 he began to study stocks and prepared the study “Stocks Guarantee the Future”, with a careful evaluation of all sectors and their level of “perenniality”. Thus, he came to the conclusion that there were some sectors of the economy with greater chances of enduring, such as food, sanitation, energy, mining, and finance.

After listing the areas considered most promising, Barsi then went on to list all the publicly traded companies that made up each of these sectors and started “mining” companies, separating those with the greatest chances of long-term success.

After sorting the companies by outcome, he arrived at what would be the best company to invest in: Anderson Clayton, a foreign-owned company, with a price of 50 cents per share and paying a dividend of 12 cents.

But here Barsi found a flaw in his project: although the company was healthy, was in the food sector – considered perennial – and paid good dividends, its long-term success was uncertain for a twofold reason: the two ladies over 80 who owned the company were increasingly finding it difficult to deny buyout offers from other companies. And the one who alerted them to the problem was the company’s own vice president.

The warning was enough to make Barsi change his strategy of investing in Anderson Clayton – and also to show how important it was to know deeply the company in which he intended to invest.

Barsi had to settle for the company that was second on his list: Companhia Energética de São Paulo (CESP). His argument for choosing the company was simple: no matter what you do with a property, you will have to pay the electricity bill. His first goal was to own 100,000 shares in Companhia Energética de São Paulo (CESP) with the intention of receiving dividends. The company was chosen because it paid a minimum priority and mandatory dividend of 10% on the par value, which today would be worth R$1.00, distributed every six months. At the time, his goal was to accumulate the equivalent of US$ 5 thousand, according to his own calculations, less than a popular car. It was a modest and attainable goal, which was later broken down into smaller goals. The idea was to buy 1,000 shares a month. Barsi then started saving everything he could from his auditor’s salary to buy stock in the company. When he reached 100,000, shortly after he started, he celebrated his first achievement as an investor who was only looking for a complementary pension with stocks.

From that moment on, the goals started to grow – and were continuously achieved. Barsi started to apply the reinvestment technique: he used the money he received from dividends to buy more shares of the company and increase his position in the company.

The rest is history.

In the early 1970s, Barsi also owned a brokerage house, Cruzeiro do Sul. He spent 18 years working as an economics editor at the Diário Popular newspaper – a period that helped him get to know even more deeply the companies in which he would like to invest.

Another way to get to know the companies better and ask questions was by calling the Investor Relations center. “I would make my recommendations, basing on what I interpreted from company meetings, which I would go and visit. I visited all the publicly traded companies at the time. And I was creating a much more reliable perception of what the company was,” he said in an interview.

After leaving the Diário Popular, Barsi pursued his journalistic career in parallel with his investments, and was Capital Markets editor of Marketing Magazine between 1989 and 1992.

He developed his own method known as the “precautionary stock portfolio,” concentrating capital and investing in securities of companies that guarantee good dividends. It took only him only 10 years before he had enough money for his retirement. Within 10 years, the strategy had guaranteed enough income that Barsi no longer needed to work. But he kept investing.

Barsi summarizes all his experience in one piece of advice: “Anyone can get rich with stocks. All you have to do is to buy cheap stocks, negotiated below the asset value, choose good payers of dividends, and wait”. The problem with the method is in its application, especially the last part, waiting. The strategy he created is simple, but time-consuming: buy 1,000 shares of the same company every month for 30 years. After the eighth month, according to Barsi, the dividends received are enough to reinvest and it is no longer necessary to take money out of your pocket.

The strategy, according to Barsi, can be followed by anyone, but it requires a lot of discipline and patience. Because, more than investing in stocks, Barsi invests in business projects with prospects for success.Buying stocks, for him, is just a way to participate in these projects. His intention is not to resell the papers in the future, but to receive part of the profits, as a small shareholder. “Anyone who invests in companies with fundamentals, without being in a hurry to sell, will make money. But if you do it with a good strategy for the proceeds, you become a millionaire”. But for that, you have to manage your anxiety.

For example, in 2019 alone, he received R$4 million in profits from Eletrobras, equivalent to a monthly “salary” of R$300,000. And this came from just one of the many companies that make up his portfolio. Yes, throughout his career as an investor, Barsi made some mistakes, such as investments in Banco do Progresso and Banco Nacional. “They were three losses that I had to sustain, but they didn’t shake me up because I continued with the other shares. I never lost anything because I started from scratch and what was taken from me was part of what I gained from the market,” he says. But he also accumulated other excellent hits. One of his best moves was with Banco Santander’s shares. Barsi started buying the shares when they were worth R$0.50. Many years later, in January 2020, the shares he had bought, of the preferred type (SANB4), were trading at R$25.35. Today, about 15 companies are part of Santander.

The megainvestor’s portfolio is focused almost 85% on dividends. Today, about 15 companies are part of his portfolio. All of them are from sectors considered perennial, such as banking, electricity transmission and distribution, and pulp and paper. In the long term, such companies generate cash flow and a positive profit. Some of them have been in his portfolio for more than 30 years.

In some circumstances, Barsi invests in other companies “outside” his pension portfolio – he has a separate amount just for these investments of opportunity – but he uses this method only to leverage himself and then sell the shares to inject more money into his 12 core portfolio companies.

To get into his portfolio, the company needs to “score” well in his analysis, which takes into account whether the products and/or services are consumed for long periods of time; whether the company’s corporate rules are well defined; the quality of management; the financial health and profits; and the regularity of dividend distribution.

For those new to the market who ask for tips, Barsi repeats three basic rules: 1) don’t put in the stock market money that may be needed, as an emergency reserve (although Barsi himself doesn’t follow this advice, since he has 100% of his investments in the stock market); 2) invest only in well-founded companies and not in “tips” from friends or colleagues; and 3) never sell shares out of necessity.

A constant critic of fixed income – which Barsi usually calls “fixed loss” – the investor guarantees that all his money is invested in stocks or, as he prefers to say, in projects of electric power, cellulose, financial sector, chlorine and soda. He also does not invest in the futures market, saying he does not buy “wind”. “I don’t know anyone who got rich speculating on the stock market, buying options, or with leverage strategies.”, says Barsi.

Always focusing on profitable companies that pay good dividends, his strategy has remained the same for decades.

And he says he doesn’t invest in stocks because they are just stocks. He invests in business projects with prospects of being successful, and the shares are the means of participating in these projects. In this way, he guarantees more security and effectiveness in his investments. “Today, I can state without mistake that shares guarantee the future”. He says he doesn’t give a damn about his wealth, which, according to him, only feeds his ego, and what he really cares about is the dividends paid by the companies in which he invests.

The recipe for success seems simple, but it is exactly what transformed the shoeshine boy into one of the biggest investors in Brazil.

And he is not even today considering changing stock positions he has carried for years. The largest individual investor in Brazil has positions in the following securities: Banco do Brasil (BBAS3); IRB Brazil (IRBR3); Klabin (KLBN11); Suzano (SUZB3); Unipar (UNIP6); Taurus Armas (TASA4); Isa Cteep (TRPL4); Taesa (TAEE11); Paranapanema (PMAM3); Santander Brasil (B3:SANB11) and Cemig (CMIG4).

One of his relatively new positions, reinsurer IRB Brasil RE, “just needs a boost” after shares fell 90% following the discovery of an accounting fraud in early 2020. “It’s like a locomotive – it’s on the rail but not running. It needs fuel, and that fuel is capitalization,” he said. In July 2022 his youngest daughter, Louise Barsi, was elected to join the reinsurancer’s audit committee.

Bruno Monsanto, a partner at RJ Investimentos, says that Barsi has two merely speculative positions: the mentioned IRB Brasil and Paranapanema. The first company has fallen more than 90% in the last three years and is now worth less than R$1, “and as it is not a company with a perennial income stream the investor believes that the company will have a strong recovery in the future”, says Monsanto. Paranapanema, on the other hand, has fallen by about 80% in the last five years – in 2019 it was worth more than R$40, and today it costs around R$5. “Even with the judicial recovery, the shareholder also believes that the company will recover”, also says the partner of RJ Investimentos.

One of Barsi’s biggest concerns is that the new Brazilian government, which takes office this January, will tax dividends paid by companies on the stock exchange. Still, he remains optimistic that the tax will not exceed 15%, even though a 30% to 40% rate could erode shareholder profits.

As far as cryptocurrencies are concerned, 2023 should be another year where Barsi continues with his sharp strategy, i.e. out of the market. Asked if he plans to invest in the sector, Luiz Barsi stated that “exorcise the cryptocurrencies“. It is worth remembering that exorcism is a practice in which some religious perform a ritual to expel evil spirits. This is not the first time Barsi has taken a stand against cryptocurrencies. Recently, he stated that “cryptocurrencies are fantasies of people who are easy to deceive”, which does not fit his profile.

The so-called intellectual assets are those created by companies for their business, which may or may not give them a competitive advantage in the market. And according to Luiz Barsi, cryptocurrencies also fit the definition, indicating that because they have no physique, they have no credibility. Finally, in addition to exorcising cryptocurrencies, Luiz Barsi stated that he will never buy a digital currency, stamping his foot that he will remain steadfast against financial technology in 2023.

When asked if money is the main item for success in investments, the great investor goes further: “Money is important, but it doesn’t take you far. Discipline does! It is an extremely important factor for the following reason: every individual who intends to invest must follow a basic rule, which is never spend more than he earns. Simple and obvious”.

And today by the way he lives not that much differently today than he did in his early adulthood. Barsi still takes the subway, works several hours a day, wears simple clothes, and lives a life without ostentation. Anyone who sees the gentleman with the white hair combed back, wearing a short-sleeved shirt and his glasses, and using his special free Single Ticket for seniors in the São Paulo subway, might not know that he is one of the country’s biggest investors. A father of five children, Barsi still works at a brokerage firm’s office twice a week – where he goes often accompanied by his youngest daughter Louise, who follows in her father’s footsteps and has created a program to train investors.

Louise, who is not 30 yo yet, has an enviable résumé: she is a certified investment analyst for the brokerage Elite Investimentos, holds a seat on the fiscal councils of AES Tietê, Klabin and Santander, is a substitute member of the board of Unipar Carbocloro and a member of the board of Eternit. From an early age, Louise was groomed to take over her father’s business. As a teenager she did not receive pocket money, but dividends (about R$300 per month) from a portfolio her father had put together especially for her. On her birthday she would ask for shares as a present and follow in her patriarch’s footsteps, reinvesting almost everything. She, along with two partners, created the company Actions Guarantee the Future, the same name as the project developed by Barsi in the 1970s, which gave origin to his way of investing. Louise hopes to help people build a portfolio of stocks for retirement and carry on her father’s legacy.

“If anyone researches anything about my father in the 1970s they won’t find anything. People only came to believe him when he became a winner, decades later. My idea is to try to convince people, as soon as possible, of the importance of investing. For me, it is an honor to be able to continue his legacy,” said the daughter of the “king of the stock market”.

But not even Louise takes all her father’s advice to the letter. She says that even she, who already considers herself a “young retiree,” cannot give up fixed income – called by both of them a fixed loss.

“He actually has 100% of his capital in variable income because he has such a large position that his cash is the proceeds. Obviously, those who are not there yet, which is the case of 99% of investors, like me, have to have a portion in fixed income. The purpose is as a reserve. For the average investor, these resources can’t go to variable income at all”.

Despite his calm, Barsi doesn’t spare any criticism. He pokes fun at economists, politicians, banks, funds, and the stock market itself.

In his opinion banks manage resources for their own benefit, and not for the market. He affirms, for example, that funds are not the best instrument to get into the capital market because they always reap benefits for themselves through management fees, instead of focusing on the interests of their clients. And that brokers and managers recommend investing in them because, unlike with stocks, it is possible to buy and sell funds without being taxed. “Real estate funds are a confidence game. So are funds in general. Private pension is another one. Run away from funds. You make the fund owners rich. They charge you management fees, success fees, performance fees, and I don’t know anyone who has made money with funds besides bankers”.

“Brazilians have an aversion to paying taxes. I love paying tax because it’s a sign that I won, you know?”, he says. Nevertheless, he is against a tax on dividends: “Not that one!”

And his advice to all the investors who are just starting to invest?

“My greatest legacy will be to get people to invest in wealth generation. If you are going to buy stocks in the market now, the first thing is to define a focus, a guideline, and be aware that they will only make money in the medium and long term. The other thing is to create criteria. My most important criterion is that of priority. If someone comes to me saying that he wants to sell me a Mercedes, I will say no, because it is not my priority. My priority is to grow my monthly income portfolio. I go on exorcising everything that is not my priority. I don’t do anything on impulse.

And in the market you will only win if you don’t consider yourself a minority shareholder. Consider yourself a small owner, because the minority shareholder can sell the shares, the small owner won’t sell, because the bigger owner won’t sell either. In 1970-71 I thought I should be the owner of Banco do Brasil. Today I am not the owner, but I am the biggest individual shareholder. It was the criteria. This is the lesson I would like to leave”.

Books that piqued our interest over the past week

Invention and Innovation: A Brief History of Hype and Failure

by Vaclav Smil

The world is never finished catching up with Vaclav Smil. In his latest and perhaps most readable book, Invention and Innovation, the prolific author—a favorite of Bill Gates—pens an insightful and fact-filled jaunt through the history of human invention. Impatient with the hype that so often accompanies innovation, Smil offers in this book a clear-eyed corrective to the overpromises that accompany everything from new cures for diseases to AI. He reminds us that even after we go quite far along the invention-development-application trajectory, we may never get anything real to deploy. Or worse, even after we have succeeded by introducing an invention, its future may be marked by underperformance, disappointment, demise, or outright harm. Drawing on his vast breadth of scientific and historical knowledge, Smil explains the difference between invention and innovation.

Amazon


Palo Alto: A History of California, Capitalism, and the World

by Malcolm Harris

In PALO ALTO, the first comprehensive, global history of Silicon Valley, Malcolm Harris examines how and why Northern California evolved in the particular, consequential way it did, tracing the ideologies, technologies, and policies that have been engineered there over the course of 150 years of Anglo settler colonialism, from IQ tests to the “tragedy of the commons,” racial genetics, and “broken windows” theory. The Internet and computers, too. It’s a story about how a small American suburb became a powerful engine for economic growth and war, and how it came to lead the world into a surprisingly disastrous 21st century. PALO ALTO is an urgent and visionary history of the way we live now, one that ends with a clear-eyed, radical proposition for how we might begin to change course.

Amazon


For Blood and Money: Billionaires, Biotech, and the Quest for a Blockbuster Drug

by Nathan Vardi

In the multibillion-dollar business of biotech, where pharmaceutical companies, the government, hedge funds, and venture capitalists have spent billions on funding, experimentation, and treatments, a single molecule can stop cancer in its tracks―and make the people who find that rare molecule astonishingly rich. For Blood and Money follows a small team at a biotech start-up in California, who have found one of these rare molecules. Their compound, known as a BTK inhibitor, seems to work on a vicious type of leukemia. When patients start rising from their hospice beds, the team knows they’re onto something big. What follows is a story of genius, pathos, and drama, in which vivid characters navigate a world of corporate intrigue and ambiguous morality. Vardi’s narrative immerses readers in the recent explosion of biotech start-ups. He describes the scientists, doctors, and investors who are risking everything to develop new, life-saving treatments, and introduces suffering patients for whom the stakes are life-or-death. A gripping nonfiction read, For Blood and Money illustrates why it’s so hard to bring new drugs to market, explains why they are so expensive, and examines how profit-driven venture capitalists are shaping the future of medicine.

Amazon


Unscripted: The Epic Battle for a Media Empire and the Redstone Family Legacy

by James B. Stewart and Rachel Abrams

The shocking inside story of the struggle for power and control at Paramount Global, the multibillion-dollar entertainment empire controlled by the Redstone family, and the dysfunction, misconduct, and deceit that threatened the future of the company, from the Pulitzer Prize–winning journalists who first broke the news. Unscripted is an explosive and unvarnished look at the usually secret inner workings of two public companies, their boards of directors, and a wealthy, dysfunctional family in the throes of seismic changes, from the Pulitzer Prize-winning journalists James B. Stewart and Rachel Abrams. Through the microcosm of Paramount, whose once victorious business model of cable fees and ticket sales is crumbling under the assault of technological advances, and whose workplace is undergoing radical change in the wake of #MeToo, Black Lives Matter, and a distaste for the old guard, Stewart and Abrams lay bare the battle for power at any price—and the carnage that ensued.

Amazon

Videos that piqued our interest over the past week

Fusion power: how close are we? | FT Film


Satya Nadella: Microsoft’s Products Will Soon Access
Open AI Tools Like ChatGPT | WSJ


Reid Hoffman | Talking AI with AI


StrictlyVC in conversation with
Alfred Lin of Sequoia Capital


India’s Plan to Stop China’s Belt & Road Money


The Failing Economy of Sri Lanka


The Disturbing Story of Coco Chanel


Taiwan’s Ultra-Convenient Convenience Stores


Sydney’s $5BN Tunnel U-Turn


This Facial Recognition Tool Could Be the End of Privacy


THOUGHTS ON AI ART

Dispatch №12

Korean companies have for years sought orders for more expensive vessels such as LNG carriers. Construction of LNG carriers is also a segment where Korean shipyards have a technological edge over rivals. In 2021 Korea’s LNG carrier market share was 93%. For Korean shipbuilders, LNG carriers accounted for 65% of their shipbuilding contracts in 2022. Now China is treading on Korea’s heels and trying to get its share of the pie, but it’s a long way to go. OK. Korea is fully booked for years to build LNG carriers. And what is the integral part of LNG carrier? Engines.

Trends and Companies

STX Heavy Industries and the engines for LNG carriers

War in Ukraine has impacted global gas markets. In the spring of 2022 US was talking about establishing “virtual transatlantic gas pipelines” to Europe and in the time of energy crisis liquefied natural gas (LNG) shipping capabilities become the matter of utmost importance. The consequence of war is partial exclusion of Russia from global energy markets and in theory it may lead to a total exclusion of Russian gas and oil from Western energy market. In circumstances like that you need more gas from US, Australia and Qatar. Maritime routes are mainly used to transport LNG.

The United States only began shipping LNG overseas in 2016 but has became the world’s largest LNG exporter during the first half of 2022, according to data from CEDIGAZ, surpassing longtime export leaders Qatar and Australia. Three export facilities under construction on the USA eastern coast are set to further cement American dominance of the sector when they are fully operational by 2025. Germany is planning five LNG import terminals, of 25 new floating import plants that S&P Global expects to be installed across the European Union in coming years. Greece, Italy, Ireland and the Netherlands also have planned terminals, as well as France, Finland, Estonia, Cyprus and Poland.

The crisis in Ukraine has helped several LNG companies record bumper profits this year. The export company Cheniere earned $3.8bn more in cash from its operations in the first half of 2022 compared to the same period last year, while Sempra, a gas liquifying company, has enjoyed an eightfold increase in LNG sales to Europe. LNG flows to Europe from Australia and Qatar as well.

China in its turn tries to ensure future energy supplies. In November Qatar and China agreed to a $60 billion, twenty-seven-year deal for liquefied natural gas (LNG).

Asia in general is seen as the key engine of gas and LNG demand growth. Shell expects global LNG demand to reach 700 MT by 2040. The primary driver has been growing demand in Asia; Shell predicted in 2021 that Asian countries could absorb as much as 70% of the new LNG volumes coming to the market over the next two decades.

Current policies of the Association of Southeast Asian Nations (ASEAN) member states preserve an important role for natural gas in these countries’ energy supply mix. Natural gas plays a significant role in the ASEAN economy, representing 23 percent of the overall energy supply mix and 31 percent of total installed electricity generation capacity. The industrial sector is the main driver of economic growth and gas demand growth in the region. Existing policies suggest that in 2025 natural gas will still play a major role in the energy supply mix and, consequently, the region will become a net gas importer, with imports reaching 130 bcm by 2050.

To transfer so much LNG you need more LNG carriers. And here they come.

The LNG carrier market is expected to record a compound annual growth rate, or CAGR, of approximately 3.6% from 2022-2027. Last year Qatar Energy signed its first LNG carrier charter contract with Japan’s MOL. MOL placed an order to build four LNG carriers with Hudong-Zhonghua Shipbuilding in China. The Japanese company will lease these carriers to Qatar Energy. It became the first company to sign a charter contract with Qatar Energy with regard to Qatar’s LNG project. Qatar is the world’s largest LNG producer and is in the process of dialing up LNG production at the Northfield gas field. The Middle East nation plans to expand its LNG production capacity from 77 million tons to 126 million tons by 2027.

Earlier Qatar Energy signed non-binding slot contracts for building more than 100 LNG carriers with the three Korean shipbuilders — Korea Shipbuilding & Offshore Engineering (KSOE), Samsung Heavy Industries, and Daewoo Shipbuilding & Marine Engineering (DSME). In September 2022 South Korea’s Samsung Heavy Industries (SHI) and Daewoo Shipbuilding & Marine Engineering Co (DSME) revealed a combined real order for 11 LNG carriers worth approximately $2.35 billion.

Korean companies have for years sought orders for more expensive vessels such as LNG carriers. Construction of LNG carriers is also a segment where Korean shipyards have a technological edge over rivals. In 2021 Korea’s LNG carrier market share was 93%. For Korean shipbuilders, LNG carriers accounted for 65% of their shipbuilding contracts in 2022. Now China is treading on Korea’s heels and trying to get its share of the pie, but it’s a long way to go.

OK. Korea is fully booked for years to build LNG carriers. And what is the integral part of LNG carrier? Engines.

That finally brings us to Korean company called STX Heavy Industries.

STX Heavy Industries

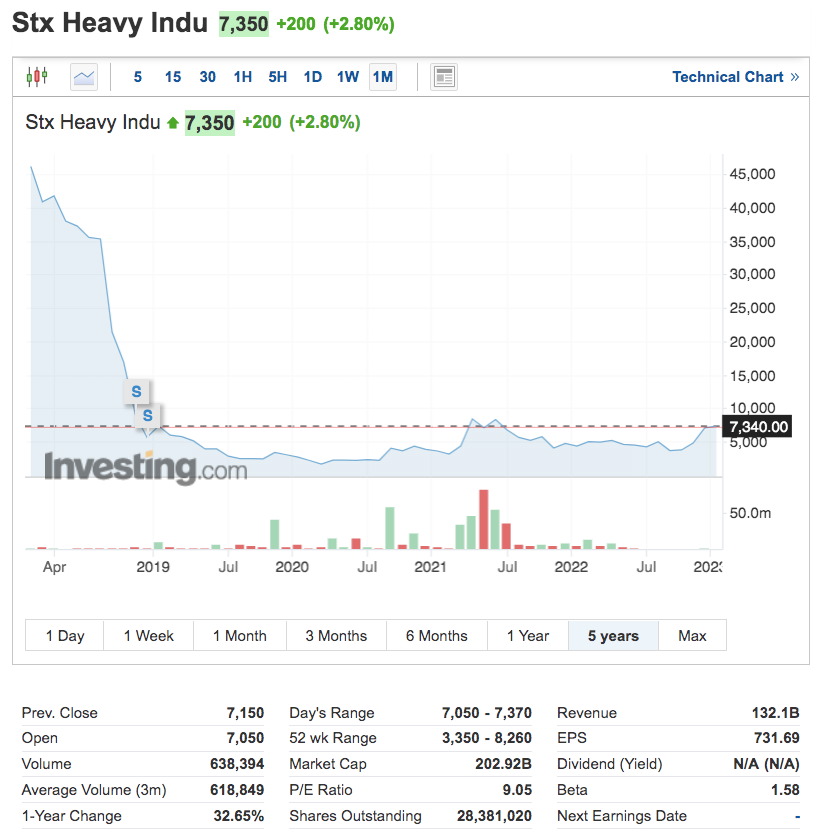
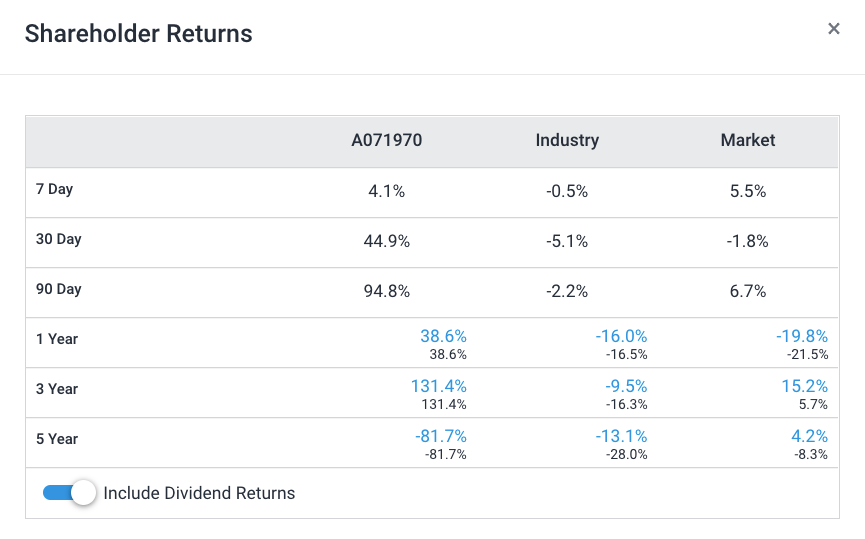
STX Heavy Industries Co Ltd is engaged in plant design and the manufacturing of low-speed engines, core materials, and equipment for ships in South Korea. Its products include crankshafts, cylinder liners, turbochargers, and cargo pumps. Its shipbuilding material segment provides cargo oil pump systems, liquefied natural gas carrier insulation boxes, heavy fuel oil supply system units and purifier units.

The company’s top clients include Daewoo Shipbuilding & Marine Engineering (DSME) and K Shipbuilding, among others. Later in 2022 the company announced that it signed a contract to supply marine engines worth 13.9 billion won (about 10 million US dollars) to a Chinese shipbuilder.

  • Name: STX Heavy Industries Co., Ltd.
  • IPO: May 2009
  • Ticker: A071970
  • Exchange: KOSE
  • Founded: 1976 (STX Corporation)
  • Industry: Industrial Machinery
  • Sector: Capital Goods
  • Market Cap: $164m
  • Shares outstanding: 28.38m
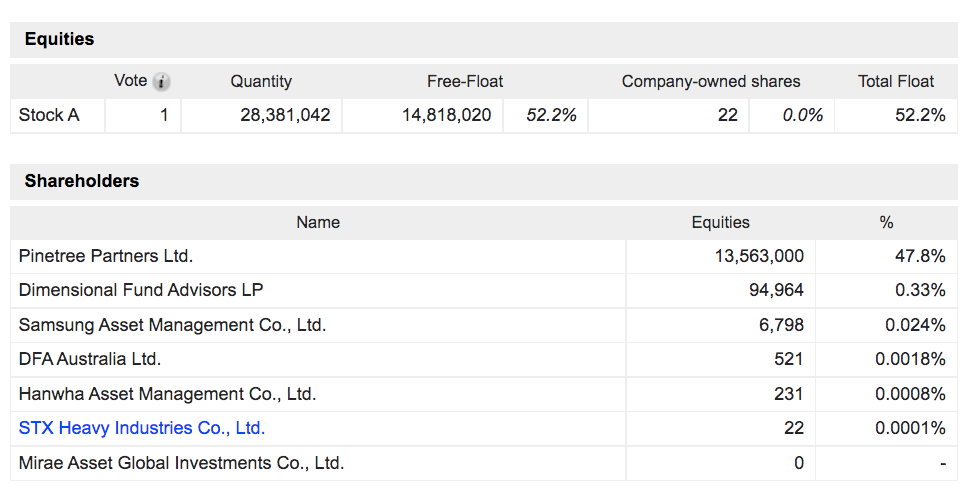
  • Free-Float: 52.2%
  • Free-Float capitalization: $85.5m
  • CEO: Sun Pil Choi (since March 2020)
  • Employees: 146
  • Website: https://www.stxhi.co.kr

STX Heavy Industry is a subsidiary of the former STX Group. It was established in February 2004 and is mainly engaged in marine engines, land-use power generation engines and ship supporting business. The company was formerly known as STX Enpaco and STX Metal Co., Ltd. and finally changed its name to STX Heavy Industries Co., Ltd. in January 2013. After the disintegration of STX Group, STX Heavy Industry entered the restructuring process in August 2016.

In March 2018, STX Heavy Industries selected South Korean private equity fund (PEF) operating companies PineTree Partners and GlobalSeAH as preferred bidders respectively. Subsequently, PineTree Partners acquired its OEM business unit for 98.7 billion won (about 92.6 million U.S. dollars), accounting for about 66.1% of STX Heavy Industries’ total shares, by acquiring new shares and corporate bonds issued by STX Heavy Industries. In a later development the PE firm has reduced the shareholding rate through block deals, over-the-counter transactions with a large number of securities, and trading on the stock exchange.

Pine Tree Partners announced earlier last year that it would sell its overall remaining 47.8 percent stake in STX through a tender process. The first round, expressing interest in the company was due by December 14. STX Heavy Industries will choose a preferred bidder by February 2023, and after the final bidding, a stock purchase agreement is expected to be completed in the first quarter of 2023.

Based on a current market valuation of approximately $160+ million, the implied value of the shares of STX being sold is approximately $78.7 million.

As we can see it’s rather small company with modest market cap, but what is interesting in current global circumstances is the attention this company hets from Korean major shipbuilding players.

And we have two large competitors here.

Korea Shipbuilding and Offshore Engineering (KSOE) made a preliminary bid to acquire a controlling stake of STX Heavy Industries, a local ship engine maker. KSOE, the intermediate sub-holding company of HD Hyundai, submitted a letter of intent to buy 47.81 percent of STX Heavy Industries. Hyundai currently has an engine manufacturer within its group but said it was interested in STX to meet the rising demand for engines as part of its strong shipbuilding orderbook.

“KSOE will be able to afford the cost of acquisition with its cashable assets,” said Kang Kyung-tae, analyst at Korea Investment and Securities. “The goal of the takeover deal will be expanding its share in the growing ship engine equipment market,” explained Kang. According to Kang, Hyundai Heavy Industries, a shipyard 78.02 percent owned by KSOE, has an engine production capacity of 12 million horsepower a year, and STX Heavy Industries’ annual capacity stood at 1.3 million. “We believe that the acquisition will help meet the growing demand for ship engines, and therefore participated in the preliminary bidding,” said a spokesperson for KSOE. “By combining Hyundai Heavy Industries’ engine technology, we will be able to extend our line-up into small- and mid-sized engines.”

Following the media reports, STX Heavy Industries’ share price skyrocketed by nearly 30 percent.

Immediately after that the market learned that Hanwha Group is also entering the bidding process. South Korea’s Hanwha Group appears to be moving quickly to consolidate its position in the shipbuilding industry with reports that it joined the bidding for marine engine manufacturer STX Heavy Industries. Hanwha did not confirm that it was interested in STX, but the Korean media is reporting that Hanwha has begun a due diligence for the engine business.

Reports that Hanwha has entered the bidding for STX sent the price of the company’s stock soaring as much as 15 percent in Korea.

The expression of interest in the engine manufacturer came two days before Hanwha completed the agreement to recapitalize Daewoo Shipbuilding & Marine Engineering (DSME) assuming control from the Korea Development Bank (KDB). Hanwha, Korea’s seventh largest conglomerate said it planned to integrate DSME and expand its capabilities after the pending deal closes in early 2023. KDB had previously said the shipyard required private management and investments to expand its capabilities and technologies to meet the emerging challenges in shipbuilding. DSME is said to be one of the largest customers of STX Heavy Industries. DSME reportedly relies on STX Heavy Industries and several other engine manufacturers.

There are more bidders. Other bidders are believed to include rival Korean company HSD Engine (formerly Doosan Engine), an unknown foreign bidder as well as several private equity funds.

Why the major Korean shipbuilders are after modest STX Heavy Industries?

STX is reported to be one of only three Korean manufacturers of low-speed diesel engines, including Hyundai’s internal capability, and a third independent company, HSD Engine. Basically, it’s the only remaining small player on the market of engines of that type for Korean companies that make LNG carriers. And keep in mind that Korean manufactures hold more than 90% of that global market.

What more important is that STX builds not only a line of diesel marine engines but it is as well having grown its position in dual-fuel engines which are experiencing a rapid rise in demand.

STX Heavy Industries produces large low-speed engines for ships and power plants, and the company has a technical partnership with German engine heavyweight MAN Energy Solutions enabling it to also build and sell dual-fuel engines running on LNG and LPG.

The business is extremely attractive from a strategic point of view as shipbuilders in South Korea seek investment opportunities to bolster their marine engine-building capacity to meet the anticipated demand for greener ships.

STX Heavy Industries became the first licensee to localize a licensed 51/60DF engine, a dual fuel engine mounted on LNG (liquefied natural gas) carriers:

…As an alternative to stricter IMO environmental regulations, we succeeded in commissioning the world’s first LPG dual-fuel engine (LGIP) for G-Type ships with MAN-ES in January 2020, producing engines as demand for VLGC increases. At the current bridge point of transition to the next-generation fuel that meets the environmental regulations of IMO 2050, we are leading and responding to the radical market change by providing suitable engines such as GI and LGIP produced by our company.

In December 2019, STX Heavy Industries and MAN-ES successfully commissioned the world’s first LPG dual-fuel engine for ship propulsion (LGIP-Liquid Gas Injection Propane). The two companies signed an MOU for the LPG dual-fuel engine retrofit project, built an LPG engine production facility, and conducted R&D and type approval tests for the 6G60ME-C9.5-LGIP engine.

STX Heavy Industries has accumulated production/start-up experience and know-how in production/testing LPG engines for ships for the first time in the industry and has completed preparations for mass production of ME-LGIP. ME-LGIP engines emit 80% less harmful exhaust gas such as nitrogen oxides (NOx), sulfur oxides (SOx), and fine dust (PM) than existing ship oil, HFO (Heavy Fuel Oil), so it is possible to respond to IMO2050 environmental regulations even without installing scrubbers. Thus, firstly the application to LPG carriers is becoming standardized. The advantages of LPG fuel are eco-friendly, convenient bunkering due to easy storage and transfer, and a worldwide well-equipped fuel supply and demand infrastructure. In addition to these advantages, ME-LGIP that uses LPG can also reduce CO2 by 20 to 25%, enabling EEDI regulatory response as a bridge fuel.

The ME-LGIP engine is expected to be easier to convert into an ammonia engine (to be released in 2024), which is considered a carbon-neutral fuel in the future, than an LNG propulsion engine. So, LPG propulsion ships can also be regarded as a representative supplement to prepare for strengthened IMO2050 environmental regulations…

Investments in ships with dual-fuel engines are soaring as shipowners look at ways to future-proof their vessels while cutting their emissions at the same time. Furthermore, marine engine manufacturers are racing against the clock to develop engines that can run on alternative low-carbon and zero-carbon fuels such as ammonia and hydrogen.

More than that, there is a need to make alteration to the already sold engines. In May 2022 MAN Energy Solutions has signed a cooperation agreement with STX Heavy Industries Co., Ltd., to deliver its three EEXI (Energy Efficiency eXisting ship Index) solutions to MAN B&W-branded low-speed engines manufactured by STX HI. The goal behind the agreement is to provide STX HI customers with an EEXI solution to help accelerate the pace for EEXI compliance.

Thomas Leander, Vice President – Head of Solutions & Site Manager, MAN Energy Solutions, said: “I am happy we have reached an agreement with STX HI that will help customers become EEXI-compliant. This also means a lot to us given our commitment to helping customers meet market demands regarding decarbonisation.”

Chun-Dong Kim, Senior Vice President and Head of Engine Components & Retrofit Service Division, STX HI Said: “We are very pleased to take this opportunity to reach an agreement with MAN Energy Solutions who will provide the relevant solution for EEXI regulation while STX HI will provide a reliable solution for decarbonisation to customers. Starting with this agreement, we look forward to futher cooperation with MAN in the future to respond to environmental regulations.” IMO’s MEPC 335(76) regulation that come into force from January 2023 requires vessels already in service to become EEXI (Energy Efficiency eXisting ship Index) compliant. Products of MAN Energy Solutions meet the vast majority of shipowners’ request for a simple, economical solution that complies with the impending regulation. MAN Energy Solutions products reduces carbon emissions by restricting the maximum power – and thus, fuel consumption – produced by prime movers to a lower value than what was originally designed and certified for.

And the analysts believed it was inevitable that Hanwha and Hyundai would emerge as rivals in the industry and will try to obtain all the available on the market “greener” engine production capacities as soon as possible.

STX Heavy Industries overview of available financial results and stocks

STX, listed on the main bourse Kospi, posted 169.3 billion won in revenue and 10.9 billion won in operating losses in 2021. From January to September of this year, it had 132.1 billion won in revenue and 32 billion won in operating profit.

For the third quarter, the company reported sales was KRW 53,010.37 million compared to KRW 38,757.11 million a year ago. Net income was KRW 12,429.72 million compared to net loss of KRW 505.62 million a year ago. Basic earnings per share from continuing operations was KRW 438 compared to basic loss per share from continuing operations of KRW 18 a year ago.

For the nine months, sales was KRW 132,101.48 million compared to KRW 116,982.11 million a year ago. Net income was KRW 11,516.67 million compared to net loss of KRW 17,066.9 million a year ago. Basic earnings per share from continuing operations was KRW 406 compared to basic loss per share from continuing operations of KRW 602 a year ago.

The results may not impress much now, but keep in mind, that the company went through turbulent times and restructuring. It ended it’s ”rehabilitation” procedures only in 2019, released it’s spin-off (STX Energy Solution) in 2021 and fully engaged in “greener”engines with it’s German partner just in a past couple of years. News about Hanwha and Hyundai showing an interest in bidding for 47.81 percent of STX Heavy Industries made the stock jump 15% and 30%. Demand for LNG carriers and the “greener”engines for those ships is growing. The future looks bright for the company after the deal will be closed in February this year.

The Person

At the end of 2022 we heard the news: Berggruen Prize Jury announced its selection of preeminent Japanese philosopher and literary critic Kojin Karatani as the winner of the 2022 Berggruen Prize for Philosophy & Culture.

The $1 million award is given annually to thinkers whose ideas have profoundly shaped human self-understanding and advancement in a rapidly changing world. Karatani is the first Asian laureate of the Berggruen Philosophy & Culture Prize, a rare thinker whose ideas move across philosophy, literary theory, aesthetics, linguistics, economics, and politics — East and West; past and present. The Berggruen Prize Jury has selected Kojin Karatani for his “radically original contributions to modern philosophy, the history of philosophy, and political thinking — making Karatani’s work particularly valuable in the current era of troubled global capitalism, crisis in democratic states, and resurgent but seldom self-critical nationalism.” “Kojin Karatani is one of the most remarkable philosophers of our time. He has produced new philosophical concepts that delve into the nature of democracy, nationalism, and capitalism in an impressive ensemble where the notions of reciprocity and fairness loom large as the unifying links,” said Berggruen Jury Prize Chair Antonio Damasio.

Wow! $1 million award is given annually to philosophers!

Who is the person behind that idea?

Nicolas Berggruen is a US-based billionaire ($3.1bn) investor and philanthropist. Born in Paris, France, he is a dual American and German citizen. He is the founder and president of Berggruen Holdings, a private investment company and the co-founder and chairman of the Berggruen Institute, a non-profit, non-partisan think tank that works to address global governance issues.

Interesting people often have interesting parents, and Berggruen’s were fascinating. His father was a journalist who fled Germany in 1936 when his editor informed him that, due to his Jewish surname, he could no longer use his byline. Settling in San Francisco, Heinz Berggruen started writing art criticism for the San Francisco Chronicle, then enlisted in the American military and was stationed in Europe. When the war was over, he opened an art gallery in Paris, became close friends with Picasso. Nicolas’ mother was the German actress Bettina Moissi, who in 1948 starred in Long is the Road, the first German film to deal with the Holocaust; she married Heinz in 1960, and Nicolas was born in 1961. Before he died in 2007, Heinz donated 90 works by Klee to the Metropolitan Museum of Art in New York and sold more than 100 paintings by Picasso, as well as works by Alberto Giacometti, Henri Matisse and Klee, to the Berlin State Museums for the below-market price of $120 million. Art was the passion of Heinz Berggruen but also his vocation, and Nicolas inherited his father’s business acumen. Oliver, Nicolas’ brother, recalls playing bartering games when they were kids: “I always wondered a few hours later, ‘How did my brother end up with all these possessions?’”

Nicolas attended elementary school at the École alsacienne in Paris. He was raised Catholic, his mother’s faith. Growing up in Paris in the 1970s, Berggruen spent his time reading. He was particularly drawn to the work of French philosopher Jean-Paul Sartre and the issues of political governance. Berggruen attended high school at Le Rosey in Switzerland. He became interested in Marxism and by 15 had written a constitution for a utopian country. Berggruen refused to learn English at the time because he thought it was “the language of imperialism.” Berggruen had a rebellious nature, frequently challenging teachers on intellectual matters and eventually, he was expelled from the school for sedition. At 16, Berggruen passed his state exams in Paris before completing a baccalauréat in Paris as a candidat libre. In 1978, Nicolas moved to London, where he became fluent in English and trained under property developer and philanthropist Lord Max Rayne at London Merchant Securities, known today as LMS Capital Plc.

In 1979, 17-year old Berggruen moved to New York to attend New York University, where he obtained a bachelor’s degree in Finance and International Business in 1981. “In my teens I was interested in photography. Then I decided that I should learn something about the world of commerce. And I came to America at age 17 to escape Europe. I went to NYU—nothing better than being 17 years old and coming to New York.”

With his own savings and a modest trust fund — modest, at least, compared to what it could have been — he began investing in real estate, stocks and bonds. His father then lent him $250,000 to kick-start his investing career, and made it clear he expected to be repaid. Berggruen did well, and in 1984 he founded Berggruen Holdings, which invests internationally in real estate, media and retail. In 1988 he co-founded a fund of hedge funds which also did well; Alpha Investment Management in New York grew to about $2 billion under management before the founders sold it for an undisclosed sum to Safra Bank. Among his largest holdings today are hefty stakes in the German department store Karstadt and Burger King. He’s famous for buying bankrupt Karstadt for 1 euro in 2005, immediately injecting over 65 million euros into to the company ($83 million) and saving over 25,000 jobs. He then spent 400 million euros over the next five years on the company and brought it out of bankruptcy in 2010.

Over three decades, the investor has gotten rich by tapping his worldwide network of business contacts to find mostly small, beaten-down companies to buy, expand and sell. He negotiates many of the buyouts himself, looks for companies loaded with debt or with family owners who are looking to retire. The firms also need to have strong cash flows and defensible business models. After restructuring the company’s debt and investing in expansion, he’ll often hold it for a decade or more before selling. Berggruen has also made money with four blank-check companies: shell companies that go public and then use cash or shares to acquire an operating business. The eccentric investor has stumbled plenty too, particularly when taking detours from his buyout specialty. A foray into hedge funds produced lackluster results before he chucked the venture. And several investments in faddish businesses such as ethanol were a bust. “You make mistakes,” Berggruen says. “You learn”.

Berggruen, who has made a fortune — $3.1bn — investing mainly in real estate, for years was known as the homeless billionaire, jetting around the globe in his Gulfstream while living and working out of the world’s finest hotels. Berggruen hopscotched around the world carrying a small bag of clothing, toiletries, books and his iPhone, staying entirely in hotels: The Peninsula in Beverly Hills, Claridge’s in London, Hotel Cipriani in Venice… In an interview with Bloomberg, Berggruen stated: “I’m not that interested in material things. As long as I find a good bed that I can sleep in, that’s enough”. He says his decision to live a rootless existence wasn’t a means of dodging taxes; he says he pays them in the United States.

But eventually he did settle down having children following the 2016 births (from the same egg donor and two surrogates) of Olympia and Alexander, biological sister and brother, who are barely three weeks apart.

OK. This guy made couple of billions investing in real estate. Nothing new. And yes, of course, as many other billionaires Berggruen has signed Buffett’s giving pledge, promising to give away more than half his fortune when he dies. So why he is an outstanding and interesting billionaire?

What may be unusual about Berggruen is what exactly he has decided to do with his life and his wealth: undertake a global campaign to reform democracy and promote economic prosperity.

In the late 2000s, dissatisfied with his career in finance, Berggruen began privately studying philosophy and political theory with a couple of UCLA. professors: “Well, I started meeting with two professors at UCLA, Brian Copenhaver in philosophy and Brian Walker in political theory. And that’s how the whole thing started. The professors gave me a reading list, I read it, and then we discussed it. We spent a lot of time talking about this concept of governance, and then I thought, “Let’s take some of these concepts and apply them to the real world”.

Brian Copenhaver and Nicolas would meet on Friday afternoons, in Berggruen’s suite at the Peninsula Hotel, and they focused on three works: Aristotle’s “Nicomachean Ethics,” Nietzsche’s “On the Genealogy of Morals” and Sartre’s “Existentialism Is a Humanism.” Copenhaver says that the discussions typically lasted three or four hours and that it was “philosophical conversation as it is meant to be.” He told me that Berggruen was eager to engage with the texts but also wanted to understand why some ideas gained traction and others did not. “It’s one thing to have a theory,” Copenhaver says. “It’s another thing to have a theory that might make its way in the world.”

Copenhaver says he wasn’t paid but did ask Berggruen to donate to UCLA.

For Berggruen, the tutorials were a springboard to a new role and a new life; he now wanted to use his fortune to make a mark in the realm of ideas. The primary goal was not to promote his own thinking but, rather, to provide the money and space for others to ponder the major issues of our time. Colleagues and associates say that to the extent there was any self-interest at play, it was in Berggruen’s desire to surround himself with smart people and to have stimulating conversations. Reid Hoffman, a founder of LinkedIn and a member of the Berggruen Institute’s board of directors, says that some ultrawealthy individuals have a tendency to be “in broadcast mode,” as he describes it — they really just want to hear themselves talk and have others validate their opinions. That’s not the case with Berggruen. “Nicolas wants to have a discussion,” Hoffman says.

In 2010 donating over $100 million he founded Nicolas Berggruen Institute with the mission to develop “new ideas to shape political, economic and social institutions in an era of Great Transformations”. “We are totally independent, we can think very long term, and we can focus on key ideas that will improve humanity,” he says of the institute. “We may never get there but we are willing to take the risk”. To address these issues subsequently provided Berggruen Institute with an additional US$500 million in 2016. Berggruen has recruited so many prominent names to the institute’s roster of supporters and advisers — Eric Schmidt, Reid Hoffman, Arianna Huffington and Fareed Zakaria are among those listed on the organization’s website — that it has been described as his own personal Davos. “There’s no question that we have tried to put together a group far away from the day to day political debates, of people who may have constituencies but no longer have to get elected. They are able to discuss things privately and come up with solutions. It is very undemocratic in a classic sense in that it is elitist. But it’s not like our group suddenly has superpowers and we can do whatever we want. All we can do is have the power to suggest. That’s all we have”.

The institute employs around 30 people, has some 40 fellows worldwide and maintains offices in Los Angeles, Beijing and Venice. It publishes a magazine, Noema (ancient Greek for “thinking”), that covers politics, technology, climate change, culture and much else.

Among its many activities, Berggruen Institute puts up a $1m purse — similar to that of a Nobel Prize — every year to somebody whose work in the area of philosophy and culture have “profoundly shaped human self-understanding”. Berggruen says that the purpose of his prize is to fill a void left by the Nobel Prizes, which include the Peace Prize as well as honors for literature, medicine, chemistry and physics but not philosophy. Berggruen says his prize is “a signal that philosophy is equally important,” a point underscored by the $1 million given to the winner, approximately the same amount awarded to Nobel recipients. Antonio Damasio, a professor of neuroscience, psychology and philosophy at the University of Southern California and the chair of the Berggruen Prize jury, points that money couldn’t buy prestige and acceptance. Instead, the power of the ideas they celebrate is what gives intellectual prizes their currency. “There’s a lot of commonality,” he said. The aim of the prize, he added, was to honor philosophy in “a broad sense, not the narrow, continental sense,” and to celebrate “love of knowledge, critical knowledge.”

Berggruen is not a member of the Berggruen Prize jury. “I actually don’t think I’m qualified”. “I have a very philosophical view on this, which is a very Eastern way,” Berggruen said. “I almost feel like we humans are just vessels. I feel that way. I’m just a vessel.”

Nicolas explains his motives: “I did a lot of things that were practical but maybe not that thoughtful. After a while, I wanted to get back to my real interests—politics and philosophy. I regret I didn’t get back to them earlier. By not only learning but then by investing in the world of ideas, in the world of new ideas, I could not only learn something for me, but hopefully contribute.”

Berggruen says that he wants to “empower ideas,” with an emphasis on “courageous or creative thinking.” Tobias Rees, a German American philosopher whose work has been supported by the Berggruen Institute, suggests that Berggruen might best be thought of as a kind of latter-day Medici. He is, Rees says, a wealthy patron trying to stimulate a “philosophical and artistic renaissance or spring for our times.” In 2021, Berggruen signed a preliminary agreement to purchase the Casa dei Tre Oci on the Giudecca island in Venice, with plans to use the space to host symposia, workshops and exhibitions in partnership with major museums. In 2022, he also bought the Palazzo Diedo in the Cannaregio district, which is to focus primarily on dedicated artist commissions; the first artist-in-residence is Sterling Ruby.

Berggruen Institute stands apart from many other think tanks in that it lacks an explicit ideology and is not necessarily looking to put its own people in government. Nathan Gardels, a veteran California political figure and foreign-affairs commentator who co-founded the institute with Berggruen and serves as Noema’s editor in chief, says the organization is “more sympathetic to the left than the right” but strives to be “post-ideological.” It wants to help make democratic governments more effective and responsive.

Dawn Nakagawa, the institute’s executive vice president, says the mission of Berggruen Institute has evolved in recent years; the institute is now “a lot more unique and philosophical. The new horizon of our work is really to try to poke our nose into the unknown.” Nakagawa cites something called the Transformations of the Human project, which developed as part of the institute. ToftH, as it is known, was initially conceived by Tobias Rees, who believed that artificial intelligence and biotechnology were redefining what it meant to be human and who wanted to foster conversations among technologists, philosophers and artists about where all of this innovation is taking us as a species.

According to Nakagawa, the emphasis these days is on nurturing revolutionary ideas. “If we develop one idea that actually changes and shifts the way the world thinks, that is success,” she says. “But success may not come until long after we’re dead,” she adds, noting that “this work requires patient capital.” Berggruen, the source of that capital, seems to be very patient. He says it can take decades, even centuries, for ideas to catch on and that he is fine waiting. Transformative insights are often not “obvious or popular” at first, and some of the greatest thinkers were persecuted. “Socrates was poisoned,” Berggruen says. “Jesus Christ ended up on a cross, right? Karl Marx was exiled. Spinoza exiled. Confucius, in effect, exiled.” He says the institute needed to show some concrete achievements or otherwise “we won’t be able to engage people.” There are, however, no near-term metrics for gauging the efficacy of what he sees as its most consequential work. We live in a “super result-oriented society,” Berggruen says, but “the one area you cannot measure” is that of fundamental ideas.

Given his passion for the really big questions, it seems reasonable to wonder what Berggruen thinks of proposals to rein in the wealthy. Concerns about inequality are “very legitimate and relevant,” he says. In his view, capitalism has proved to be highly effective at raising living standards, but it is a system that gives people an incentive to excel, and a few are always going to prosper to a disproportionate degree. Rather than punishing these “outliers,” a better solution would be to let the rest of society benefit directly from their success. Specifically, he believes that the public, through a sovereign wealth fund, should be given a substantial equity stake in start-up companies. It is a form of “predistribution,” a concept popular among center-left policy wonks, and one that the Berggruen Institute endorses; the idea is to share the wealth up front, rather than trying to redistribute it after the fact. “As opposed to taking away from the outliers,” Berggruen says, “you’re giving everyone else a stake in the success of these outliers.”

Berggruen’s own beliefs on renewing democracy include a stable US-China relationship, participation without populism, addressing climate change, and instituting “universal basic capital” to ensure adequate living conditions for everyone regardless of employment status. His views of democracy call for an inclusive political culture and positive nationalism. Berggruen states: “Democracy is really about giving individuals a place in society, a voice—respect, in some ways—equality as humans. It’s also a system. It’s not every individual for themselves; it has to be society as a whole.”

Tao Ruspoli talks to Nicolas Berggruen

In 2012, Berggruen and Nathan Gardels published the book Intelligent Governance for the 21st Century: A Middle Way Between West and East. The book’s central argument is that populism and short-term thinking have hindered the Western democracies’ progress, while many authoritarian Eastern nations, China, in particular, would benefit from strengthening their meritocratic systems with the popular legitimacy that is typical of Western governments. Published in English, the book was later translated into Spanish, Portuguese, and other languages. The Financial Times named it as one of their “Best Books of 2012”. In 2019, Berggruen and Gardels published their second book, Renovating Democracy: Governing in the Age of Globalization and Digital Capitalism. The authors advocate for the restructuring of democratic government frameworks to ensure adequate living conditions for everyone. They argue that in a time where jobs are being replaced by technology, employment should not determine if a person’s basic needs are accounted for.

I don’t feel lonely or isolated. Sometimes it just feels frustrating. You don’t know what results you’re going to get. The mountains are big. Humanity has a way of progressing, but not in a linear way. If I don’t get results, at some point I may get exhausted. And if I do, I’d be happy to be doing more reading, writing and studying philosophy. At the end, the key thing is you’ve got to live with yourself. That’s the real test. Everything else is fleeting.

Berggruen acknowledges that his wealth makes him an imperfect messenger: People will simply assume that he’s just another plutocrat looking to avoid higher taxes. (He claims he is not opposed to paying more in taxes — he just doesn’t think redistributive policies will do enough to ameliorate economic inequality.) He says that because he is a billionaire, his motives tend to be viewed with suspicion and that it is hard to get his ideas judged solely on their merits. “I’ve created my own curse, and it’s my own fault.”

Billionaire that gives money to philosophers and studies philosophy himself. How about that for a change?

Books that piqued our interest over the past week

Power and Progress: Our Thousand-Year Struggle Over Technology and Prosperity

by Daron Acemoglu and Simon Johnson

A thousand years of history and contemporary evidence make one thing clear. Progress depends on the choices we make about technology. New ways of organizing production and communication can either serve the narrow interests of an elite or become the foundation for widespread prosperity. The wealth generated by technological improvements in agriculture during the European Middle Ages was captured by the nobility and used to build grand cathedrals while peasants remained on the edge of starvation. The first hundred years of industrialization in England delivered stagnant incomes for working people. And throughout the world today, digital technologies and artificial intelligence undermine jobs and democracy through excessive automation, massive data collection, and intrusive surveillance. It doesn’t have to be this way. Power and Progress demonstrates that the path of technology was once—and may again be—brought under control. The tremendous computing advances of the last half century can become empowering and democratizing tools, but not if all major decisions remain in the hands of a few hubristic tech leaders.

Amazon


Inside Vanguard: Leadership Secrets From the Company That Continues to Rewrite the Rules of the Investing Business

by Charles D. Ellis

One of the world’s largest and most trusted investing institutions, Vanguard serves over 30 million clients, manages more than eight trillion dollars, and is an influential industry disruptor. Now, Charles D. Ellis―referred to by Money magazine as “Wall Street’s wisest man”―reveals the story behind Vanguard’s rise to the top of the investing world. Provided unprecedented access to Vanguard’s leaders, Ellis explains why Jack Bogle started Vanguard and how he and his successors developed it into an investment industry disrupter that became the global leader. Ellis includes in-depth interviews with the executives and key leaders of Vanguard, clear takeaways and lessons from their experiences, a primer on ETFs, and Jack Brennan’s Leadership Principles. From the emergence of index funds to the success of exchange-traded funds, Inside Vanguard is a near-Shakespearian drama of individual human struggle and triumph.

Amazon


A Random Walk Down Wall Street: The Best Investment Guide That Money Can Buy

by Burton G. Malkiel

In a time of rampant misinformation about ways of growing your money, Burton G. Malkiel’s gimmick-free investment guide is more necessary than ever. Whether you’re considering your first 401k contribution or contemplating retirement, the fully updated, fiftieth anniversary edition of A Random Walk Down Wall Street remains the best investment guide money can buy. Drawing on his experience as an economist, financial adviser, and successful investor, Malkiel shows why an individual who saves consistently over time and buys a diversified set of index funds can achieve above-average investment results. He addresses current investment fads and critically analyzes cryptocurrencies, NFTs, and meme stocks. Malkiel reveals how to be a tax smart investor and how to make sense of recently popular investment management techniques, including factor investing, risk parity, and ESG portfolios.

Amazon


Power Failure: The Rise and Fall of an American Icon

by William D. Cohan

No company embodied American ingenuity, innovation, and industrial power more spectacularly and more consistently than the General Electric Company. GE once developed and manufactured many of the inventions we take for granted today, nearly everything from the lightbulb to the jet engine. GE also built a cult of financial and leadership success envied across the globe and became the world’s most valuable and most admired company. But even at the height of its prestige and influence, cracks were forming in its formidable foundation. In a masterful re-appraisal of a company that once claimed to “bring good things to life,” pre-eminent financial journalist William D. Cohan argues that the incredible story of GE’s rise and fall is not only a paragon, but also a prism through which we can better understand American capitalism. Beginning with its founding, innovations, and exponential growth through acquisitions and mergers, Cohan plumbs the depths of GE’s storied management culture, its pioneering doctrine of shareholder value, and its seemingly hidden blind spots, to reveal that GE wasn’t immune from the hubris and avoidable mistakes suffered by many other corporations.

Amazon


Billionaires: The Lives of the Rich and Powerful

by Darryl Cunningham

In Billionaires: The Lives of the Rich and Powerful, Darryl Cunningham offers an illuminating analysis of the origins and ideological evolutions of four key players in the American private sector–Amazon founder and CEO Jeff Bezos, media mogul Rupert Murdoch, and oil and gas tycoons Charles and David Koch. What emerges is a vital critique of American capitalism and the power these individuals have to assert a corrupting influence on policy-making, political campaigns, and society writ large. Cunningham focuses on a central question: Can the world afford to have a tiny global elite squander resources and hold unprecedented political influence over the rest of us? The answer is detailed through hearty research, common sense reasoning, and astute comedic timing. Billionaires reveals how the fetishized free market operates in direct opposition with the health of our planet and needs of the most vulnerable — how Murdoch’s media mergers facilitated his war-mongering, how Amazon’s litigiousness and predatory acquisitions made them “The Everything Store,” and how the Kochs’ father’s refineries literally fueled Nazi Germany.

Amazon


Shrimp to Whale: South Korea from the Forgotten War to K-Pop

by Pacheco Pardo

South Korea has the most remarkable of histories. Born from the ashes of colonialism, partition and a devastating war, back in the 1950s there were real doubts about its survival as an independent state. Yet South Korea did survive, and first became known globally for the export of cheap toys, shoes and clothing. Today, South Korea is a boisterous democracy, a vibrant market economy, a tech powerhouse, and home to the coolest of cultures. In just seventy years, this society has grown from a shrimp into a whale. What explains this extraordinary transformation? For some, it was ordinary South Koreans who fought to change their country, and still strive to continue shaping it. For others, it was all down to forward-looking political and business leaders, who had the vision that their country would one day be different. Whichever version you prefer, it’s clear that, at its core, South Korea’s is the story of a people who dreamt big, and saw their dreams coming true.

Amazon


Strangers to Ourselves: Unsettled Minds and the Stories That Make Us

by Rachel Aviv

Strangers to Ourselves poses fundamental questions about how we understand ourselves in periods of crisis and distress. Drawing on deep, original reporting as well as unpublished journals and memoirs, Rachel Aviv writes about people who have come up against the limits of psychiatric explanations for who they are. She follows an Indian woman celebrated as a saint who lives in healing temples in Kerala; an incarcerated mother vying for her children’s forgiveness after recovering from psychosis; a man who devotes his life to seeking revenge upon his psychoanalysts; and an affluent young woman who, after a decade of defining herself through her diagnosis, decides to go off her meds because she doesn’t know who she is without them. Animated by a profound sense of empathy, Aviv’s gripping exploration is refracted through her own account of living in a hospital ward at the age of six and meeting a fellow patient with whom her life runs parallel―until it no longer does.

Amazon


Die With Zero: Getting All You Can from Your Money and Your Life

by Bill Perkins

Die with Zero presents a startling new and provocative philosophy as well as practical guide on how to get the most out of your money—and out of your life. It’s intended for those who place lifelong memorable experiences far ahead of simply making and accumulating money for one’s so-called Golden Years. In short, Bill Perkins wants to rescue you from over-saving and under-living. Regardless of your age, Die with Zero will teach you Perkins’ plan for optimizing your life, stage by stage, so you’re fully engaged and enjoying what you’ve worked and saved for. You’ll discover how to maximize your lifetime memorable moments with “experience bucketing,” how to convert your earnings into priceless memories by following your “net worth curve,” and find out how to navigate whether to invest in, or delay, a meaningful adventure based on your “spend curve” and “personal interest rate.”

Amazon

Videos that piqued our interest over the past week

Tiananmen Square Leader to Wall St Legend – Li Lu


Expert AI as a Healthcare Superpower


Crony Capitalism Built Indonesia’s Biggest Business Empire


Is There a Better Economic System than Capitalism?


1984 by George Orwell | Lex Fridman


How Semiconductors Ruined East Germany


MrBeast: Future of YouTube, Twitter,
TikTok, and Instagram


Steve Wozniak on inventors vs engineers and the early days of Apple


How Adobe Became One of America’s Most Valuable Tech Companies